

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ferrochrome Powder Market Reaches USD 505.5 Million in 2025, Set to Grow at a 4.85% CAGR During 2026–2032

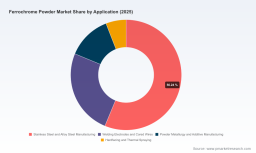
Ferrochrome Powder Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting’s new market study on Ferrochrome Powder (base year 2025; forecast period 2026–2032) positions senior executives and deal teams to make higher-confidence decisions as the sector navigates decarbonization, energy volatility and customer premiumization. Our high-level market model shows the ferrochrome powder market expanded from approximately USD 385.12 Million in 2020 to USD 505.5 Million in 2025, and—at a compound annual growth rate (CAGR) of 4.85%—is projected to reach roughly USD 704.21 Million by 2032. This briefing distills the strategic implications for 2026 decision cycles while reserving the segment-level tables, supplier scorecards and scenario workbooks for the full report.
Ferrochrome Powder Market
Why this report matters for 2026 corporate decisions
- Procurement and cost strategy: Quantifies exposure to feedstock (chromite) volatility and energy price swings, enabling procurement teams to design hedging and contractual protections tailored to powder grades and carbon profiles.
- Capex and plant planning: Provides a decision framework for investments in low‑emission smelting, enrichment and powder atomization facilities linked to payback sensitivity under carbon price regimes.
- Product and commercial strategy: Maps the premiumization pathways for low‑carbon and high‑purity powders across welding, powder metallurgy and additive manufacturing (AM) applications.
- M&A and partnerships: Identifies the value levers private equity and strategic corporates should seek—vertical integration, energy-secured assets, and specialty powder capability.
- Regulatory and market access: Translates incoming carbon policy (notably CBAM) into actionable supplier selection criteria and cost-to-serve models for imports and exports.
Macro dynamics reshaping the ferrochrome powder market
- Transition economics and CBAM: The European Union’s Carbon Border Adjustment Mechanism came into force in January 2026. Importers of ferrochrome products now face certificate obligations tied to embedded emissions, materially altering landed cost calculus for high-emission powder imports into Europe. For buyers and suppliers competing in or exporting to markets with carbon adjustments, carbon intensity is now as commercially salient as micron distribution or carbon-content grade.
- Feedstock supply concentration: Ferrochrome production remains closely tied to chromite ore availability. South Africa, Kazakhstan and India continue to command outsized upstream influence; supply disruptions or price spikes in ore markets transmit quickly to producer margins and to downstream powder pricing.
- Energy and decarbonization: Smelting energy intensity, grid reliability and access to low‑carbon power are determinative for future competitive advantage—particularly for players pursuing low-carbon, high‑purity powders targeted at premium stainless and specialty steelmakers.
- Shifts in Chinese production: Recent capacity additions and regional restart dynamics have led to notable shifts in high‑carbon ferrochrome output year‑on‑year. These movements affect global freight flows and short‑term price arbitrage opportunities for powder purchasers and traders.
- Demand bifurcation: End markets are polarizing—large-volume stainless mills prioritize cost and stable supply, while rapidly growing niches (additive manufacturing, powder metallurgy, surface engineering) demand tighter quality controls and traceable low‑carbon credentials.
Competitive landscape — structure and strategic postures
The market shows moderate concentration: the top-three producers account for roughly 42% of market share, while the top-five approach close to 59%. This concentration profile creates an environment where scale, integration and energy security confer durable advantages, but specialist powder producers retain pricing power in premium niches.
Ferrochrome Powder Market
- Outokumpu Oyj (Helsinki): Leveraging the Kemi chrome mine and the Tornio smelter, Outokumpu is positioning itself as a vertically integrated supplier of low‑carbon ferrochrome and enriched chromium materials. Its announced pilot plant investment in the U.S. (late‑2025) signals an intent to scale high‑purity, low‑emission powder capabilities for third‑party sales—a strategic play to capture premiums in markets where carbon and origin matter.
- Glencore / Glencore‑Merafe Chrome Venture (Baar / South Africa): A major supplier into stainless steel value chains, Glencore’s scale is complemented by strategic moves toward energy collaboration in South Africa. Their MoU for sustainable energy solutions suggests an industry pivot to secure lower‑carbon power for smelting, an essential step to defend competitiveness under carbon pricing.
- Samancor Chrome (Johannesburg): One of the largest integrated producers, Samancor’s volume and logistics clout underpin supply security for high‑carbon specialties and metallurgical demand—important for buyers prioritizing throughput and cost.
- Tata Steel Limited (Mumbai): Beyond scale, Tata is differentiating on sustainability credentials—issuing an Environmental Product Declaration in the ferrochrome segment—thereby improving access to European and sustainability-driven buyers.
- Specialist powder groups (e.g., Metal Powder Group, Stanford Advanced Materials) and Chinese producers (multiple regional manufacturers): These players focus on product quality, consistency and competitive factory-gate pricing across carbon grades. Their technical know‑how and flexible supply models make them go‑to partners for welding consumables, AM feedstock and tailored metallurgy.
- Mid‑tier and regional players: Producers in Kazakhstan, India and China provide important capacity buffers and offer partnership opportunities for offtake and tolling arrangements that can be structured to manage carbon and feedstock risks.
What PW Consulting’s full report delivers (practical, transaction‑ready content)
- Market sizing and forecast models (2020–2032) with scenario layers for carbon-pricing, ore shocks and energy cost pathways—includes dynamic dashboards that allow users to re-run the model under alternate assumptions.
- Supplier scorecards and due‑diligence templates covering quality controls, traceability, emissions intensity, energy mix, logistics resilience and counterparty ratings.
- Capex & project tracker: a monitored registry of announced brownfield and greenfield investments, pilot plants and atomization lines—mapped by expected ramp timelines and strategic intent.
- Price and cost build‑ups: atomized cost models for representative powder grades (energy, reductant, ferroalloy inputs, labor, freight) to support margin and negotiation scenarios.
- Regulatory impact matrices: CBAM exposure matrices, customs & tariff sensitivities, and compliance playbooks for European access.
- Commercial playbooks: buyer segmentation, go‑to‑market pricing frameworks for premium low‑carbon powder, and sample specification sheets for welding, AM and metallurgical customers.
- M&A and partnership shortlist: targets and valuation cushions for strategic acquirers and private equity, including integration risk checklists and synergies templates.
- Operational checklists: recommended retrofits and digital controls for improving yield and reducing emissions in existing powder production lines.
Note: The report reserves segment‑level numerical breakdowns, regional tables and supplier-specific financials behind the full analysis package; the above is designed to communicate practical value without disclosing the granular tables that underpin our models.
Ferrochrome Powder Market
Practical 90/180/360‑day playbook for 2026
- 0–90 days: Rapid carbon exposure audit. Map your powder sourcing by embedded emissions and landed cost into target markets (especially EU). Secure short-term offtake or tolling arrangements with suppliers that can provide traceability and provisional low‑carbon certificates. Run stress tests against a CBAM‑plus-energy‑spike scenario.
- 90–180 days: Selective supply chain de‑risking. Negotiate flexible contracts with volume bands and emergency allocation clauses. Evaluate tolling or JV options with regional low‑carbon smelters. Begin technical trials with specialist powder suppliers for AM and powder metallurgy applications to capture premium demand.
- 180–360 days: Capital and commercial moves. Finalize capex or retrofit plans where IRR is resilient under carbon price forecasts. Pursue targeted M&A or minority investments in powder specialists that have two‑to‑three year scale-up visibility or proprietary low‑carbon process IP. Launch certified low‑carbon product lines for customers willing to pay a premium.
Scenario framing and recommended responses
- Baseline (CAGR ~4.85%): Steady stainless steel demand with gradual premiumization for low‑carbon powders. Recommended response—invest selectively in low‑emission product capability and sign multi‑year procurement contracts with carbon-adjusted pricing floors.
- Carbon‑constrained (accelerated CBAM & stricter import measures): Risk of premiuming low‑carbon powder and penalizing high‑emission imports. Recommended response—fast‑track certification, partner with energy-secured smelting projects and consider localizing production to regulated markets.
- Supply shock (ore or energy disruption): Tightening volumes and spot price spikes. Recommended response—activate contingency inventory, ramp supplier diversification, and assess tolling/prefinance deals that convert feedstock into powder without immediate capital outlay.
Key takeaways for executives and investors
- The market is growing and re‑pricing along carbon and quality dimensions—our top‑line forecast to 2032 reflects that structural shift as well as cyclical influence.
- Energy availability and chromite feedstock access are the twin operational levers that will determine which producers can sustainably capture premium margins in low‑carbon powder segments.
- Companies that combine traceable low‑carbon production, technical powder expertise and flexible commercial structures will outperform peers in the emerging CBAM era.
For procurement leaders, operations heads, corporate strategists and investors preparing 2026 budgets and M&A pipelines, PW Consulting’s full Ferrochrome Powder Market Report delivers the models, supplier intelligence and actionable playbooks needed to convert market insight into measurable outcomes. The deep segmentation tables, supplier financials, and scenario workbooks referenced above are available in the complete report.
For detailed analysis of this topic, please visit the official page: Ferrochrome Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com