

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
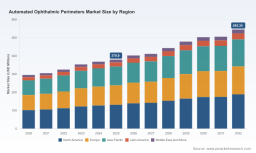
PW Consulting: Automated Ophthalmic Perimeters Market to Grow from USD 379.9 Million in 2025 to USD 545.34 Million by 2032 at a 5.31% CAGR — North America Leading with USD 131.48M

Automated Ophthalmic Perimeters Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting is pleased to release a strategic briefing drawn from our full market research report on the Automated Ophthalmic Perimeters market. As senior strategy advisors and the firm’s chief industry analysts, we prepared this executive preview to articulate why healthcare executives, product leaders, investors, and hospital procurement teams should recalibrate strategies in 2026. The market for automated perimetry is neither static nor niche—overall industry revenues expanded from roughly USD 295.4 Million in 2020 to about USD 379.9 Million in 2025, and our base-case forecast projects growth to approximately USD 545.3 Million by 2032 at a 5.31% CAGR. These headline dynamics matter: they reflect durable demand driven by aging populations, expanding glaucoma diagnostics, and rapid feature-led substitution across clinical workflows.
Automated Ophthalmic Perimeters Market
Why this briefing matters for 2026
-
Timing: 2026 is a pivotal inflection year. Capital equipment cycles in hospitals, shifting reimbursement bandings, and the maturation of objective and VR-based perimetry converge to create opportunity windows for new entrants and incumbent expansion. Decisions made in 2026—on product roadmaps, clinical evidence investments, and channel realignment—will determine share trajectories into the next funding and procurement cycle.
Automated Ophthalmic Perimeters Market -
Momentum: The market’s medium-term trajectory shows a steady climb from a mid‑2020s baseline to a materially larger opportunity by 2032. That trajectory supports multi-year commercialization investments, but only where companies align innovation with adoption frictions faced by end users.
Automated Ophthalmic Perimeters Market -
Concentration: Market concentration remains meaningful. Our analysis shows the top three players account for a strong majority of revenue, and the top five amplify that dominance—an important input when modeling competitive responses, price elasticity, and partnership leverage.
Key market dynamics shaping strategy
-
Technology integration and workflow efficiency: Buyers increasingly prize perimeters that integrate imaging, active retinal tracking, AI-driven progression algorithms, and faster test protocols. Vendors advertising measurable workflow gains—reduced patient chair-time, parallel imaging plus perimetry, or binocular testing modes—are gaining traction in high-volume settings. Expect acceleration of hybrid offerings combining traditional static perimetry with VR and portable modalities for outreach and screening workflows.
-
Regulatory and evidence thresholds: Market access remains gated by device clearance regimes. In the U.S., 510(k) clearance is required for many perimetry systems and CE Mark under the EU Medical Device Regulation is the baseline for Europe. Notably, objective perimetry systems have begun to clear both pathways, increasing the bar for clinical claims and creating differentiation via evidence-backed, objective endpoints.
-
Reimbursement and commercialization economics: Visual field testing is supported by established CPT codes that cover automated threshold perimetry. Typical payment schedules provide a predictable technical and professional revenue stream in many markets, with fee levels that influence acquisition payback calculations for hospitals and clinics. Procurement models are therefore sensitive to test throughput, technician time, and the ability to deliver measurable improvements in operational KPIs.
-
Hospital capital cycles: Hospitals remain a central end-user and primary commercial channel for capital perimeters. Their CapEx decisions are influenced by overall hospital budgets, competing diagnostic priorities, and demonstrable ROI tied to disease management pathways like glaucoma clinics. Vendors that can quantify per-device throughput gains, reduced downstream costs through earlier detection, or service simplifications are advantaged.
-
Pricing and tiering: The market bifurcates between full-featured premium platforms and lean, portable/virtual screening solutions. A pragmatic commercial playbook requires a clear tiered offering, bundled service options, and flexible financing to align with buyer procurement rhythms.
Competitive landscape—what to watch in 2026
The competitive map includes established optical and ophthalmic device leaders, specialized perimetry manufacturers, and several agile new entrants leveraging VR or objective retinal-tracking technologies. Key firms in the ecosystem have complementary strengths that define likely competitive moves and partnership opportunities:
-
Carl Zeiss Meditec AG (Jena, Germany) —a foundational platform player known for its Humphrey Field Analyzer series and extensive installed base; strength lies in clinician trust, validated progression analysis tools, and broad service networks.
-
Haag-Streit AG (Köniz, Switzerland) —offers projection-based systems with a reputation in both static and kinetic perimetry and robust progression analytics aimed at clinical users requiring flexible testing paradigms.
-
Topcon Corporation (Tokyo, Japan) —competes on speed and workflow integration with compact and binocular solutions; claims of substantive time savings in testing translate directly into procurement arguments for high-volume practices.
-
NIDEK Co., Ltd. (Gamagori, Japan) and Heidelberg Engineering GmbH (Heidelberg, Germany) —both pursue integration of imaging and perimetry, pushing toward unified diagnostic suites that facilitate single‑visit comprehensive glaucoma assessments.
-
Centervue/iCare (Padua/Finland) —notable for combining retinal tracking with confocal fundus imaging, positioning itself at the intersection of imaging and functional testing.
-
Konan Medical USA, Inc. (Irvine, CA) —a pivotal recent development: objectiveFIELD (OFA) achieved regulatory milestones that validate objective perimetry with retinal tracking for major markets. This regulatory progress accelerates adoption conversations around objective endpoints and will pressure incumbents to articulate comparative evidence strategies.
-
Additional regional players and new technology providers (including VR-focused entrants and several established instrument OEMs) create a competitive set where niche innovation, regional channels, and cost positioning matter.
Strategic implications and recommended moves
-
For incumbents: defend share through evidence and service economics. Prioritize clinical validation that demonstrates superiority on adoption-relevant metrics (time-per-test, reproducibility, progression detection sensitivity), strengthen installed-base service contracts, and consider platform modularity to accommodate hybrid imaging/perimetry workflows.
-
For challengers and startups: target clear use-cases where incumbents are weakest—portable screening, outreach programs, and objective perimetry for populations that struggle with subjective testing. Secure regulatory pathways early and design pricing models that lower procurement friction (e.g., OPEX-based contracts, pay-per-use, or bundled screening programs).
-
For hospital systems and large eye-care networks: leverage purchasing power by specifying workflow and interoperability requirements; include throughput and outcome KPIs in procurement contracts; and pilot VR/portable solutions in community outreach before broader rollouts.
-
For private equity and strategic investors: prioritize targets with defensible clinical data, recurring consumables or service revenue, and access to distribution channels that can scale. Given the market’s concentration and steady growth, bolt-on consolidation in regions with fragmented supply remains a practical route to expand share.
What our full report delivers (practical, actionable content)
The full PW Consulting Automated Ophthalmic Perimeters report is structured to be deployment-ready for 2026 planning cycles. Highlights include:
-
Market model and forecast (2020–2032) with scenarios—base, upside, and conservative—anchored to macro drivers and tested against sensitivity levers such as reimbursement shifts and hospital CapEx trends.
-
Competitive playbooks—detailed profiles of incumbent and emerging players, product positioning matrices, likely go-to-market tactics, and M&A target shortlists mapped to strategic themes.
-
Commercial adoption maps—buyer personas, procurement cycles, and decision criteria across hospitals, ophthalmic clinics, and diagnostic centers with pragmatic sales scripts and ROI templates.
-
Regulatory and reimbursement navigators—step-by-step pathways for market entry in major jurisdictions, plus clinical evidence checklists tailored to claim substantiation for objective perimetry and hybrid imaging-perimetry solutions.
-
Pricing and contracting toolkit—recommended tiered pricing, service bundling, and financing constructs designed to shorten procurement approval times and protect margins.
-
Scenario-based investment cases—three investment roadmaps for investors and corporate development teams with expected payback horizons under different adoption assumptions.
How to use this briefing in 2026 planning
-
Begin by stress‑testing your product roadmap against the report’s scenarios. If your R&D timeline crosses the next two procurement cycles, adjust feature prioritization toward clinically validated workflow gains and interoperability.
-
Calibrate go-to-market resources to hospital and high-volume specialty clinic behaviors: prioritize pilot sites that can generate peer-reviewed evidence and broadcaster testimonials for scaling procurement approvals.
-
Where regulatory milestones have recently shifted (e.g., objective systems achieving dual-market clearances), re-run ROI models to capture new premium pricing or faster uptake in certain payer systems.
-
Use the report’s commercial templates to simulate pricing with your local reimbursement realities in mind; in many jurisdictions visual field CPT equivalents provide a stable baseline for payback calculations.
Next steps and where to find the full intelligence
This executive preview is intended to inform 2026 strategic choices and to highlight the operationally relevant intelligence contained in the full PW Consulting market study. The comprehensive report contains the granular segmentation, region‑level demand drivers, and downloadable datasets that senior leaders and deal teams require to execute. We intentionally hold back detailed segment and regional allocations in this briefing to protect the actionable modeling embedded in the primary research.
To engage PW Consulting for a tailored briefing—where we map the market analysis directly to your balance sheet, product roadmap, or M&A thesis—please contact our Industry Practice. Access to the full dataset and segmentation tables is available through the report landing page and via a direct request to our research team.
Closing perspective
The Automated Ophthalmic Perimeters market is evolving into a higher‑value, evidence-driven arena where product differentiation, regulatory credibility, and service economics are the principal drivers of competitive advantage. A mid-single-digit CAGR and expanding absolute market size make this a compelling sector for disciplined investment. However, the winners in 2026 will be those who translate technological novelty into verifiable clinical and operational outcomes, align pricing with procurement realities, and navigate regulatory gateways proactively. PW Consulting’s full report equips you to take those next steps with precision; this briefing is your roadmap to why 2026 is the year to act.
For detailed analysis of this topic, please visit the official page: Automated Ophthalmic Perimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com