

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Military Ammonium Perchlorate Market to Grow at a 5.48% CAGR Through 2032

Military Ammonium Perchlorate Market — Strategic Intelligence for 2026 Decisions
Executive snapshot
PW Consulting today releases an executive primer drawn from our forthcoming Military Ammonium Perchlorate Market research. The study consolidates five years of historical observation (2020–2025) with a forward-looking forecasting horizon (2026–2032) and is designed to support board-level and business-unit decisions in 2026. At the macro level, the global market measured approximately USD 921.54 Million in the base year 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window, reaching an estimated USD 1,338.76 Million by 2032. The market remains highly concentrated (CR3 ≈ 78.45%; CR5 ≈ 91.12%), underscoring the strategic importance of supplier relationships, capacity security, and regulatory compliance for defense and space programs.
Military Ammonium Perchlorate Market
Why 2026 is an inflection year for AP strategy
-
Demand signal intensification: Defense modernizations, allied integration on missile and solid-rocket motor programs, and a steady cadence of civil launch activity are collectively increasing requirements for high-spec ammonium perchlorate (AP) grades. Even modest annual growth compounds quickly in a concentrated supplier market.
Military Ammonium Perchlorate Market -
Supply-side reconfiguration: Recent capacity investments and targeted expansions are reshaping available supply. Notably, a major U.S. producer has received board-level approval for a material-capex expansion—approximately a USD 100 million program to add a new production line, with more than 50% capacity uplift targeted for completion in 2026—an action with clear implications for domestic sourcing and allied supply assurance.
Military Ammonium Perchlorate Market -
Regulatory tightening and trade controls: AP and its precursors are subject to export-control regimes and munitions-list designations. In early 2025–2026 we have observed heightened enforcement and scrutiny on certain perchlorate precursors, increasing compliance overheads and creating strategic incentives for onshore or allied-sourced inventory and dual-sourcing strategies.
-
Cost volatility drivers: AP production economics are tightly coupled to upstream feedstocks—principally ammonia and perchloric chemistry—and logistics. Recent price behavior across production centers has driven benchmark pricing upward, creating a renewed focus on cost-to-deliver, indexation clauses, and feedstock hedging for long-term contracts.
What the PW Consulting report delivers (practical, decision-ready content)
Our full study is organized to convert market intelligence into executable decisions for 2026. The deliverables include:
-
An integrated market model (historical 2020–2025; forecast 2026–2032) that supports scenario testing across demand shocks, regulatory shifts, and feedstock price swings.
-
Supply-chain mapping down to primary feedstocks, critical intermediates, and logistic pinch points, with a supplier concentration heatmap that highlights single-source risk exposures.
-
Regulatory and export-control matrix—detailing jurisdictional constraints, licensing timelines, and mitigation levers for program planners and export-control teams.
-
Unit-cost build-ups and margin sensitivity analyses that quantify the impact of ammonia and chemical feedstock swings on producer economics and bid competitiveness.
-
Supplier scorecards and procurement playbooks—covering quality certifications, security-of-supply evidence, capacity ramp profiles, and negotiation levers for long-lead purchases.
-
Capex and M&A decision frameworks tailored to strategic investors, incumbent producers, and defense contractors evaluating vertical integration versus contracting strategies.
-
Operational risk and contingency templates for program managers to size inventory buffers, expedite-insurance needs, and fallback sourcing routes in the event of export-control escalation.
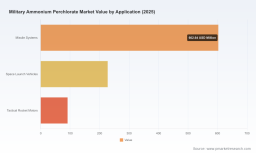
We intentionally withhold granular regional and application-level splits in this press release to preserve the report’s commercial value. The report itself contains the full segmentation, tables, and downloadable model available to subscribers and licensed users.
Competitive landscape — what incumbents and challengers are signaling
The AP market is dominated by legacy producers with deep process know-how and defense-grade certifications. Leading players combine long production pedigrees, specialist process capabilities, and proximity to defense ecosystems. Key strategic observations:
-
Domestic anchoring and compliance credentials matter: Producers that operate under sustained government oversight and hold long-term DoD/NASA or national defense certifications retain positional advantage for sensitive programs. Certification footprints (e.g., MIL-A spec compliance, ISO regimes, and REACH where applicable) are a gating factor for program-level procurement.
-
Capacity expansions are not neutral: Announcements of large-scale investments materially change procurement calculus—reducing some premium-on-security pricing but introducing risk around qualification timelines, first-off quality, and ramp reliability. Buyers should insist on staged acceptance criteria tied to production audits and sample qualification runs.
-
Regional diversification is increasing: Newer and regional suppliers in Asia and Europe supply defense and civil programs but face higher barriers for transfer into U.S.-controlled programs due to export-control regimes and qualification hurdles. For allied programs, however, reciprocal arrangements and bilateral approvals can lower these barriers subject to political dynamics.
-
Non-transparent seller economics: The concentration metrics indicate that three to five suppliers dominate supply. This elevates negotiation asymmetries, especially for non-standard grades and ultra-fine particles used in high-performance motors.
Regulatory, feedstock, and price dynamics that will shape supplier strategies
-
Export-control overlay: AP is frequently captured under munitions-list and missile-control regimes, which impacts cross-border flows, licensing timelines, and the viability of certain procurement routes. Precursor shipments have seen heightened enforcement and selective denial policies that require legal and compliance functions to be tightly integrated into sourcing decisions.
-
Feedstock sensitivity: AP production is a chemistry-driven process built on ammonia and perchloric-acid derivatives. Price direction and availability of these feedstocks directly influence producer margins and contract pricing. Our modelling shows that even modest upward moves in upstream costs can materially compress supplier margins absent pass-through mechanisms.
-
Benchmark pricing behavior: Recent market checks indicate upward pressure on AP benchmark levels across major production locales during Q1–Q2 2026. Buyers negotiating multi-year supply agreements should incorporate indexed pricing, performance-based volume commitments, and cadence-linked escalators.
Strategic imperatives for corporate and program leaders in 2026
Based on PW Consulting’s integrated analysis, organizations should prioritize the following actions this year to convert market intelligence into operational advantage:
-
Lock in qualification windows early: For defense and space programs with fixed launch or production milestones, start material qualification cycles in 2026. The supplier-base concentration and recent capacity projects mean that lead times for qualified production can be the critical path for schedule adherence.
-
Adopt a multi-layer sourcing strategy: Blend long-term offtake from certified incumbents with contingent contracts from regional suppliers who can step in for non-sensitive applications. Ensure all contracts include clear traceability, audit access, and reciprocal quality clauses.
-
Hedge feedstock exposure: Work with suppliers to embed feedstock-hedging clauses or develop joint-buying pools for ammonia and perchlorate intermediates where appropriate. This reduces cost volatility exposure and aligns incentives for continuous supply.
-
Integrate compliance into procurement KPIs: Export-control and licensing risks are now procurement risks. Add regulatory compliance, licensing cycle time, and export footprint to supplier scorecards to reduce program-level surprises.
-
Evaluate strategic investments selectively: For firms contemplating vertical integration or minority stakes in production assets, our capex sensitivity modelling highlights the scale and timeline needed to realize facility-level security benefits. Not every program requires ownership; in many cases, secured long-term contracts with escalation and capacity reservation outperform greenfield builds.
How this report supports executable 2026 decisions
PW Consulting’s report is structured as a hands-on toolkit rather than a descriptive narrative. It provides the financial model and regulatory playbooks procurement, program managers, strategy teams, and corporate development functions need to:
-
Stress-test procurement strategies against realistic price and regulatory scenarios;
-
Prioritize supplier audits and MRO/qualification milestones to match program timelines;
-
Quantify the trade-offs between onshore capacity, allied sourcing, and inventory carrying costs;
-
Identify M&A targets and partnership structures that close critical capability gaps with minimal program risk.
Next steps — where to get the full intelligence
This press release is a strategic extract intended to orient executives and program leaders to the actionable value within PW Consulting’s Military Ammonium Perchlorate Market report. To preserve commercial sensitivity and the practical edge it provides, we have intentionally withheld the granular regional and application-level tabulations and unit-level forecasts. Licensed users of the full report receive the underlying data model, supplier worksheets, regulatory heatmaps, and a set of bespoke scenario outputs aligned to program and investor questions.
For subscription access, corporate licensing, or to request a tailored briefing for your procurement, compliance, or M&A team, please contact PW Consulting through our website or client services desk to arrange a secure briefing and data delivery.
For detailed analysis of this topic, please visit the official page: Military Ammonium Perchlorate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com