

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Palm Kernel Shell (PKS) Market to Grow at 6.0% CAGR, Reaching USD 1,879.5 Million by 2032 as Asia‑Pacific Dominates

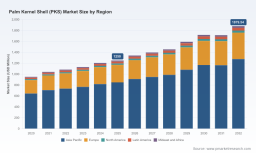
Palm Kernel Shell (PKS) Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s latest Palm Kernel Shell (PKS) Market report — based on a 2025 base year and a historical window covering 2020–2025, with a forecast period of 2026–2032 — provides pragmatic, board-level and operational intelligence for energy buyers, biomass processors, trading houses, and strategic investors preparing decisions in 2026. Our model values the global PKS market at USD 1,250.0 Million in 2025 and anticipates growth to approximately USD 1,879.5 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.0% over the forecast window. The market exhibits moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 58.2%), creating both competitive tensions and opportunities for scale plays.
Palm Kernel Shell (PKS) Market
Why this matters for 2026 decision-makers
PKS is shifting from a residual-byproduct to a traded bioenergy commodity with role-specific pricing dynamics, certification complexity, and logistics-driven margins. In 2026, energy transition targets, tightening procurement requirements in key importing markets, and trade/regulatory moves in supply countries are converging to create discrete windows for differentiated strategy. PW Consulting’s brief synthesizes macro sizing, market structure, supply-side readiness, and regulatory inflection points into a pragmatic playbook: the base math is established (steady mid-single-digit CAGR), the competitive map is observable, and the levers that will determine who captures value in 2026 are actionable.
Palm Kernel Shell (PKS) Market
Market dynamics — what’s changing right now
-
Demand trajectory: The global PKS market has demonstrated resilient expansion through 2025 and our forecast anticipates continued steady growth at roughly 6.0% CAGR to 2032. This is driven by ongoing demand from biomass power generation and industrial thermal applications as operators seek lower-carbon, cost-competitive fuel blends.
Palm Kernel Shell (PKS) Market -
Certification & market access: Importer-side environmental verification is now a procurement gate. Notably, Japan’s market has tightened third-party certification requirements for feed-in-tariff eligibility, elevating the commercial value of certified PKS and increasing the premium for suppliers who can demonstrate chain-of-custody compliance under recognized schemes.
-
Supply-side policy: Export taxation and levies in key producing countries are shaping trade flows and landed costs. Policy packages introduced into 2026 have a measurable effect on arbitrage and sourcing optimization for buyers and traders.
-
Industrialization of processing: Suppliers are investing in staged processing (screening, drying, pelletizing) and port-centric covered stockyards to reduce moisture/contaminant risk and provide consistent calorific quality — an operational differentiation increasingly rewarded by buyers focused on boiler reliability and emissions compliance.
Competitive landscape — practical takeaways
The PKS supply ecosystem includes integrated palm groups, specialist biomass processors, and trading aggregators. The competitive fabric blends upstream control (mill-by-mill sourcing) with midstream processing and downstream logistics capability. Our analysis of market participants yields three strategic archetypes:
-
Integrated originators: Major palm groups leverage mill networks to recover PKS as an energy feedstock. Their advantages are scale, visibility into raw availability, and the option to internalize use in captive power plants. These players are attractive partners for off-take arrangements where reliability and sustainability disclosures matter.
-
Specialist processors and exporters: Companies that invest in drying, screening, pelletization, and port-side facilities can deliver a more commoditized, quality-assured product to premium markets. Recent facility launches and MOUs point to an industry pivot where processed PKS commands higher access to the Japanese and other certified markets.
-
Regional aggregators and traders: Firms that stitch supplies across mills and geographies by offering flexible delivery, blended quality profiles, and third-party compliance documentation are increasingly critical for markets with complex regulatory regimes.
Representative companies span these archetypes and include vertically integrated palm producers, specialist biomass suppliers with port-side handling and quality-control capabilities, and global traders that facilitate flows to thermal power and industrial consumers. The report provides company-by-company profiles, recent strategic moves, and a comparative assessment of capability gaps — all framed to help buyers and investors prioritize counterparties for 2026 engagements.
Recent developments that change the 2026 playing field
-
Trade promotion and market demand signals: Industry association participation in major biomass expos and bilateral forums has reinforced Japan’s role as a high-volume importer and a trendsetter on certification demand.
-
Capital projects: New biomass processing capacity brought online in 2026 — including medium-to-large capacity processing plants located close to export ports — materially strengthens exportable quality PKS supply and shortens order-to-delivery lead times for premium markets.
-
Policy tailwinds and headwinds: Export levy structures in origin markets affect landed price models, while importer-side certification rules create differentiation for suppliers who have invested ahead of regulatory curves.
Operational implications and tactical playbook for 2026
Below are practical steps we advise by role to capture value and manage risk in 2026:
-
For energy buyers and utilities:
- Prioritize counterparties with third-party certification capability and documented calorific/moisture quality assurance; this materially reduces boiler operational risk and protects tariff eligibility in certified markets.
- Structure flexible multi-sourcing contracts with port-centric delivery options and short-notice volume adjustments to hedge origin-policy shocks.
-
For biomass processors and suppliers:
- Invest selectively in staged processing (screening, low-moisture stockyards, modular drying) near port hubs to capture premium differentials. Operational improvements often yield outsized margin uplift relative to incremental CAPEX.
- Obtain and actively maintain recognized sustainability certifications — the market for certified PKS will command better pricing and lower commercial friction in key import markets.
-
For trading houses and aggregators:
- Develop logistics and financing packages that address payment terms, quality guarantees, and documentary compliance for certifications; bundling these services de-risks transactions for large buyers.
-
For investors and strategic acquirers:
- Target assets that combine origin control (sourcing) with processing and port-handling capabilities — these horizontally integrated models are likely to capture the margin between raw recovery and premium certified product supply.
- Assess exposure to origin policy risk and the elasticity of demand in key importing markets; value-accretive acquisitions are those that shorten the certification and logistics pathway to premium buyers.
Key risks and how to mitigate them
-
Policy risk: Export levies and changing tariff regimes in origin countries can compress arbitrage. Mitigation: diversify sourcing across suppliers and negotiate contract clauses that share policy-change impacts.
-
Certification and market access risk: Tighter importer certification requirements can morph demand patterns quickly. Mitigation: invest early in recognized certifications and traceability systems; prioritize counterparties with established third-party verification.
-
Quality & logistics risk: Moisture, foreign materials, and inconsistent sizing increase boiler downtime and penalties. Mitigation: specify strict acceptance testing, insist on port-side covered storage where feasible, and adopt moisture-hedging clauses in contracts.
What the PW Consulting report contains (practical utility)
The full PW Consulting PKS report is designed as an operational playbook for 2026 decision cycles. It includes:
- Time-series market sizing and a transparent model of demand drivers (historical 2020–2025 plus forecast 2026–2032).
- Concentration analysis and an assessment of competitive dynamics across supplier archetypes.
- Company profiles with capability matrices covering sourcing, processing, certification, port handling, and commercial reach.
- Trade-flow and landed-cost scenarios under alternative policy and cost shocks.
- Actionable procurement templates, due-diligence checklists for counterparties, and a 12–36 month strategic roadmap keyed to different corporate objectives (cost leadership, secured supply, certified supply for premiums).
To preserve the strategic value of proprietary segmentation and transaction-level pricing, this brief intentionally omits the granular regional and application-level breakdowns that are in the full report. Those detailed splits, including modeled scenarios and supplier-level exposures, are available in the complete PW Consulting package.
Concluding recommendation — a 90-day decision agenda
- Immediate (0–90 days): Audit your PKS exposure, confirm certification needs for your target markets, and run a supply continuity stress test under origin levy scenarios.
- Near-term (3–12 months): Secure medium-term offtake or call-off arrangements with suppliers who can demonstrate certified chain-of-custody and port-based moisture control; consider minority investments in processing capacity where strategic.
- Medium-term (12–36 months): Consolidate supplier relationships, integrate traceability systems, and, if pursuing growth, evaluate M&A targets that close sourcing-to-port capability gaps.
Next steps
PW Consulting’s PKS Market report equips commercial leaders with the quantitative sizing, concentration metrics, and tactical playbooks to make informed procurement, investment, and partnership decisions in 2026. For stakeholders who require the full regional and application segmentation, supplier exposure tables, and scenario-modeled price impacts, please consult the complete report on our website or contact our team to arrange a briefing and tailored scenario run.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shell (PKS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com