

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 22.46% CAGR for Three-Dimensional Topological Insulator Market, Fueling a Quantum Computing and Spintronics Boom

Three Dimensional Topological Insulator Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an executive preview of our forthcoming Three Dimensional (3D) Topological Insulator Market report, a practical intelligence product designed to inform high-stakes corporate decision-making in 2026. Built on a rigorous historical series (2020–2025) and a detailed forecast to 2032, this analysis synthesizes market sizing, technology maturation, supplier dynamics, and regulatory shocks to deliver decision-ready guidance for materials suppliers, device OEMs, investors, and advanced research organizations.
Three Dimensional Topological Insulator Market
Market Trajectory at a Glance
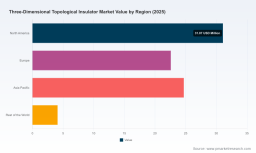
Our base-year assessment shows the 3D topological insulator market as an emerging but rapidly scaling segment of the broader quantum-materials economy. Measured in USD Million, the market expanded notably during 2020–2025 and, based on our deterministic scenario, is projected to grow at a compound annual growth rate (CAGR) of 22.46% over the 2026–2032 forecast horizon. Under the central projection, the market transitions from a niche, research-dominated space in 2025 toward a more commercially actionable market by the end of this decade, reflecting accelerating commercialization in quantum computing, spintronics, thermoelectric overlaps, and specialized optoelectronic modules.
Three Dimensional Topological Insulator Market
Two structural observations are critical for 2026 strategy: first, the market is not winner-take-all; it is moderately concentrated with the top three suppliers accounting for roughly 44% of identifiable commercial activity and the top five nearing the mid-60s percentile in aggregate concentration. Second, this concentration coexists with a diversified set of specialized suppliers — ranging from single-crystal producers to target and film providers — creating both partnership and competitive-play opportunities.
Three Dimensional Topological Insulator Market
Why 2026 Is a Strategic Inflection Point
- Technology-to-product handoffs: Several device classes dependent on 3D topological insulators reach critical maturity for prototype-to-pilot transitions in 2026–2028, compressing timelines for supply agreements and qualification.
- Supply-side stressors: Raw-material shocks and export controls experienced in 2025 materially change procurement economics and risk profiles for bismuth/telluride-based chemistries — altering cost, lead times, and contracting practices.
- Consolidation and specialization: With moderate market concentration, 2026 presents opportunistic windows for selective M&A, vertical integration, and strategic partnerships to secure IP, fabrication capability, or materials feedstock.
Supply Chain, Raw Materials and Regulatory Dynamics
Our analysis identifies tellurium and related chalcogenide precursors as the single most consequential supply-side variable for topological-insulator module economics and project timelines. In 2025 the market experienced pronounced price volatility and sourcing friction driven by changes in primary refining dynamics and export/licensing policies. For procurement and sourcing teams, this translates into three immediate operational needs: tightened visibility into feedstock origin, contractual clauses to mitigate shipment timing and licensing uncertainty, and scenario-based sourcing roadmaps that include material substitutions and inventory buffering.
Regulatory developments — notably export licensing practices that lengthened approval workflows in major refining hubs — are already changing lead-time assumptions. Companies that treat access to precursor chemistry as a strategic asset (not just a commodity procurement item) will gain short-term advantage in project execution and long-term lead on cost curves.
Competitive Landscape: Profiles and Strategic Postures
Our competitive analysis synthesizes product portfolios, go-to-market models, and technology moats across the active supplier base. The market comprises specialized crystal growers, materials manufacturers, thin-film and deposition suppliers, and distribution channels that serve both academic and industrial R&D customers.
- HQ Graphene (Groningen, Netherlands): Recognized for high-quality single crystals of prototypical 3D topological insulators and quaternary alloys used in foundational research. Their value proposition centers on material quality control for physics-driven device programs.
- American Elements (Los Angeles, USA): Operates at the manufacturing and distribution junction, supplying high-purity chalcogenide chemistries across crystal, powder, and sputtering-target formats. Their scale and breadth position them as a reliable sourcing partner for applied R&D and pilot manufacturing.
- Stanford Advanced Materials (Lake Forest, USA): Combines CVD film offerings and crystal products to serve device developers pushing toward prototype demonstrations. Their film capability is particularly relevant for firms transitioning to device integration.
- Kurt J. Lesker Company (Jefferson Hills, USA): A key supplier of sputtering targets and evaporation materials, addressing thin-film deposition pathways critical for device manufacturability and process repeatability.
- MSE Supplies LLC (Tucson, USA): Functions as an important distribution channel, aggregating specialty crystals and films for academic and industrial labs where reproducibility and logistic convenience matter.
- 2D Semiconductors / Nuevogen LLC (Phoenix, USA): Differentiates on guaranteed topological properties in single-crystal materials and specialized layered chalcogenides, catering to device developers who require verified performance baselines.
Strategically, these firms illustrate three archetypal plays: (1) vertical suppliers that emphasize material purity and reliability; (2) scale manufacturers that optimize format diversity (powders, targets, films); and (3) channel/distribution specialists that accelerate market access for small-scale adopters. Each archetype presents different partnership, investment, and competitive defense implications for corporate strategists.
Report Contents — Practical Tools Included
The full PW Consulting report is structured to be directly actionable for leadership teams preparing 2026 budgets and strategic programs. Key deliverables include:
- Comprehensive market model (historical and forecasted USD Million series, 2020–2032) with built-in scenario toggles for high/low adoption and raw-material shock paths.
- Supplier risk matrix and mitigation playbook highlighting critical nodes in the materials/value chain and practical contractual language templates for supply agreements and co-development arrangements.
- Technology readiness mapping and device-route decision framework, enabling product teams to prioritize materials/formats by commercialization risk, scaleability, and integration cost.
- Go-to-market and procurement playbooks tailored to four buyer archetypes (materials manufacturers, device OEMs, R&D institutions, and system integrators), including sample short- and mid-term KPIs.
- An M&A and partnership checklist identifying value-creation levers for rapid inorganic expansion and non-dilutive collaboration models. Note: the report provides anonymized target archetypes and due-diligence scorecards rather than named transaction advice.
- Data annex with vendor mapping, supplier capability matrices, and an executive dashboard for board-level briefings.
We deliberately package granular datasets behind the full report to preserve the commercial utility of detailed segmentation and supplier share tables. This preview intentionally avoids publishing segment-by-segment percentages and deal-level finance metrics so that decision-makers obtain maximum value from the original report deliverable.
Strategic Recommendations for 2026 Decision Cycles
Combining market growth, supplier concentration, and near-term material risks, PW Consulting advises three immediate priorities for 2026 planning:
- Secure material optionality: Establish multi-tiered supply agreements that balance long-term offtake with optionality for substitute chemistries and secondary suppliers. Where feasible, structure contracts with price-hedging or indexation clauses tied to validated raw-material benchmarks.
- Invest in scale-ready process capability: For device OEMs and integrators, prioritize development paths that de-risk deposition, integration, and testing at pilot scale — particularly for thin-film routes that offer manufacturability advantages.
- Partner early with materials specialists: Consider co-development arrangements with crystal growers and target manufacturers to accelerate qualification timelines and lock in proprietary process tolerances that translate directly into product differentiation.
For investors and corporate development teams, a targeted approach that combines minority equity in materials innovators with strategic supply or IP agreements reduces downside risk while preserving option value as the market scales. For procurement leaders, treating tellurium and bismuth-supply strategies as strategic initiatives — complete with quarterly risk reviews and scenario rehearsals — will materially reduce program slippage in 2026.
How PW Consulting’s Report Supports 2026 Decisions
The value proposition of this report lies in translating high-level market momentum into discrete, executable choices. Whether a company needs to decide on capital allocation for pilot fabs, to pursue a bolt-on acquisition, or to rework supplier contracts in the face of export-controls, our modeling tools and pragmatic playbooks are calibrated for real-world procurement cycles and board-level decision timelines.
Importantly, the analysis is designed for rapid assimilation: executive dashboards summarize the forecast and supplier risk; scenario templates enable sensitivity testing against raw-material shocks; and playbooks convert strategic intent into 90/180/360-day action plans suitable for 2026 planning cadences.
Next Steps and Access
This preview outlines the strategic contours and implications for 2026 stakeholders. The complete PW Consulting Three Dimensional Topological Insulator Market report contains the full data suite — including the granular market model, supplier-level matrices, contract templates, and the bespoke scenario outputs required to operationalize the recommendations above.
Organizations that require accelerated access for procurement negotiations, investment diligence, or product roadmap prioritization can contact our research desk to arrange a briefing and to license the dataset and deliverable set. For public details and ordering information, please visit our report page on the PW Consulting website.
Methodology and Independent Rigor
Our forecast integrates primary interviews with material suppliers and device developers, price and shipment data triangulated from commodity reporting, and proprietary adoption modeling validated against pilot-program disclosures. We apply conservative adoption curves where device value chains remain unproven at scale and overlay stress-testing for material-price and regulatory scenarios consistent with 2025 market events.
For executives who require a distilled briefing that maps the report findings into an operational 2026 roadmap — including tailored supplier negotiation scripts and a pilot qualification checklist — PW Consulting offers bespoke advisory packages that couple the report’s data with hands-on implementation support.
PW Consulting — translating advanced-materials complexity into strategic clarity for the decisions that matter in 2026.
For detailed analysis of this topic, please visit the official page: Three Dimensional Topological Insulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com