

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Water-Based Acrylic Emulsion Market to Reach USD 11.08 Billion in 2025
By pmarketresearch, 2026-07-06
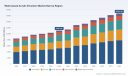
Water‑Based Acrylic Emulsion Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s latest market study on the Water‑Based Acrylic Emulsion industry synthesizes five years of historical performance (2020–2025) and a forward-looking model for 2026–2032 to equip senior executives with the actionable intelligence required for 2026 capital, product, and commercial choices. The macro story is straightforward: the addressable market expanded from roughly USD 8.45 billion in 2020 to an estimated USD 11.08 billion in 2025 and continues to accelerate under structural tailwinds. Our forecast model projects a compound annual growth rate of 6.09% across the 2026–2032 horizon, with an end‑period market value approaching USD 16.76 billion. These headline dynamics mask important tactical inflection points that will determine winners and losers in the next 18 months.
Water Based Acrylic Emulsion Market
Why this matters for 2026 decision‑makers
-
Regulatory tightening, raw‑material volatility, and evolving sustainability requirements are compressing time‑to‑market for compliant waterborne solutions; companies that act in 2026 will convert compliance obligations into market share.
Water Based Acrylic Emulsion Market -
Moderate market concentration (CR3 ~38.3%; CR5 ~54.1%) creates space for well‑executed regional scaleups, targeted product differentiation, and acquisitive consolidation—especially in specialty emulsions and customized industrial grades.
Water Based Acrylic Emulsion Market -
Margin expansion will be driven less by top‑line growth and more by raw‑material management, formulation premiumization (low‑VOC, PFAS‑free, bio‑based), and localized supply to shorten lead times for coatings and adhesives customers.
Key market dynamics shaping 2026 strategy
-
Regulatory pressure is an accelerant. Tighter VOC standards (including recent U.S. EPA aerosol coating rules and mounting state‑level limits) have made waterborne acrylics a compliance imperative for many customers. PFAS‑free and APE‑free formulations are quickly becoming market entry criteria rather than differentiators.
-
Raw‑material complexity is increasing. Acrylic acid—a primary upstream feedstock—has shown regionally divergent price behavior and periodic volatility. Our modelling shows that price moves at the acrylic acid level transmit quickly to producer margins unless mitigated by hedging, local integration, or formula redesigns.
-
Product innovation is the new battleground. Demand is bifurcating between standard architectural grades and premium high‑performance emulsions (durability, dirt resistance, lower VOC, bio‑content). R&D and application engineering capabilities are becoming equivalent to manufacturing scale as determinants of share gains.
-
Supply architecture is regionalizing. Customers increasingly prize short lead times and regulatory assurance; this favors mid‑sized players that can deploy regional reactors and service models close to end markets, while large global producers pursue strategic capacity additions.
Competitive landscape — what to watch in 2026
The market remains a mix of global chemical majors, regional specialists, and agile niche formulators. Leading incumbents are pursuing a three‑pronged go‑to‑market playbook: (1) capacity and geographic expansion to meet construction and industrial demand; (2) portfolio moves toward low‑VOC and bio‑based grades; and (3) targeted partnerships and product launches that accelerate time‑to‑market for compliant systems.
-
BASF continues to extend its broad water‑borne portfolio and has prioritized low‑VOC and bio‑based grades with capacity investments in Asia—an example of integrated multi‑market scale strategy.
-
Dow has combined product launches with North American capacity increases to serve construction and automotive value chains; its recent next‑generation emulsion launch (Sept 2025) underscores a strategy focused on performance plus regulatory compliance.
-
Arkema is moving toward low‑carbon routes via partnerships to commercialize bio‑based resins, reflecting an industry trend where “sustainable” technology alliances accelerate commercialization.
-
Lubrizol, Celanese, Synthomer, and other established suppliers are balancing investments in innovation and regional capacity to protect existing customer relationships while pursuing specialty niches.
-
Regional specialists and formulators (for example, long‑tenured U.S. and European players and agile vendors in Turkey, Japan, and beyond) are targeting rapid wins in specialty adhesives, industrial coatings, and non‑woven applications where customization commands premiums.
Recent industry moves bear watching for strategic knock‑on effects: product launches focused on reduced VOC and enhanced durability (Sept 2025), bio‑based partnerships (Sept 2025), and ongoing capacity investments (2024–2025) that materially alter local supply/demand balances. PW Consulting’s proprietary timeline maps these events against price and demand indicators to expose 6–12 month windows of opportunity.
Operational playbook — five priority actions for 2026
-
Rebalance portfolios to emphasize compliant premium grades. Prioritize development and commercialization of PFAS‑free, fluorosurfactant‑free, low‑VOC formulations and certified bio‑content where customers will pay a premium or require compliance evidence.
-
Hedge and localize feedstock exposure. Implement systematic acrylic‑acid exposure hedging and assess backward integration or tolling contracts in key regions to stabilize margin. Scenario analyses in our model show that a sustained 5–10% swing in acrylic acid costs can materially compress EBITDA for unprotected plants.
-
Accelerate regional capacity and service points. Shorter lead times and regulatory assurance are decision drivers for coatings formulators and distributors. A focused regional expansion program—paired with digital order orchestration—delivers outsized commercial returns.
-
Prioritize fast, reversible capital. In a market evolving with regulation and raw material swings, invest in modular reactors, flexible formulary capability, and toll manufacturing arrangements to change course quickly without long stranded assets.
-
Use M&A tactically. Given the mid‑tier concentration and the presence of high‑value niche specialists, acquisitive buyers should prefer targets that add formulation IP, regulatory dossiers, or regional customer networks rather than just incremental capacity.
What PW Consulting’s report delivers — practical, executable modules
This is not a high‑level overview; the report is engineered for decision execution in 2026. Core deliverables include:
-
A detailed market model (2020–2032) with base‑case and three alternative scenarios that quantify the impacts of acrylic acid price swings, regulatory tightening, and faster uptake of bio‑based grades.
-
Supplier scorecards and strategic heatmaps highlighting capability gaps, capacity timelines, and technology differentiators across the competitive set—covering product development velocity, regulatory readiness, and regional supply footprints.
-
Commercial playbooks for coatings, adhesives, and industrial customers with pricing elasticity estimates, channel strategies, and sample commercial KPIs for 90/180/360‑day rollouts.
-
CapEx decision framework and ROI calculator that incorporates raw‑material volatility and regulatory compliance costs—designed to stress‑test plant expansion and retrofit choices.
-
A prioritized M&A and partnership shortlist built on complementary capabilities (formulation IP, regional access, sustainability credentials) plus modelled integration scenarios and expected synergies.
To preserve commercial value for subscribers while demonstrating domain depth, this briefing intentionally highlights strategic levers and market geometry. The report contains the full segmented datasets, regional and application breakdowns, price curve histories, and downloadable spreadsheets required to execute the above recommendations; these granular elements are available via the report landing page.
Final takeaways for the 2026 planning cycle
Water‑based acrylic emulsions are transitioning from a compliance solution to a strategic growth platform. For growth‑oriented executives, 2026 is the year to convert regulatory and sustainability pressures into durable competitive advantage by combining portfolio upgrade, feedstock risk management, and selective regional investments. The market’s mid‑single digit CAGR masks pockets of accelerated opportunity for companies that align product innovation, regional supply, and commercial execution within the next 12 months.
PW Consulting’s full Water‑Based Acrylic Emulsion Market report provides the detailed inputs, scenario tools, and deal frameworks that procurement, R&D, and corporate development teams require to act decisively in 2026. Access the complete dataset and implementation playbooks on our website to move from strategy to execution with confidence.
For detailed analysis of this topic, please visit the official page: Water Based Acrylic Emulsion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.79% CAGR for Commercial Small Batteries Market Through 2032
By pmarketresearch, 2026-07-06
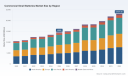
Commercial Small Batteries Market — Strategic Outlook for 2026: Practical Guidance for Executive Decision-Making
PW Consulting’s new Commercial Small Batteries Market report offers a forward-looking, execution-focused view designed to inform board-level choices, procurement strategies, product roadmaps, and M&A decisions in 2026. Built on a robust historical base (2020–2025) and a detailed forecast horizon (2026–2032), the study integrates market modeling, regulatory intelligence, and supplier benchmarking to convert market signals into operational moves.
Commercial Small Batteries Market
Executive summary: a concise market view you can act on
After steady expansion through 2020–2025, the commercial small batteries market recorded an estimated market size of approximately USD 14.58 billion in 2025. Our baseline forecast projects a compound annual growth rate (CAGR) of 6.79% over 2026–2032, bringing the market to roughly USD 23.11 billion by 2032 under central assumptions. Market concentration is moderate: the top three suppliers account for roughly 43% of the market, while the top five capture just under 59%—a structure that supports both incumbent margin preservation and discrete opportunities for challengers with focused value propositions.
Commercial Small Batteries Market
This release highlights the strategic implications embedded in those headline numbers—without disclosing the full, segment-level dataset. PW Consulting follows a “trailer” approach: we present the analytical framework and actionable recommendations here and invite decision-makers to access the complete model and granular splits through the full report.
Commercial Small Batteries Market
Why this work matters for 2026 decisions
- Procurement and cost planning: price volatility in key raw materials directly affects sourcing strategies, contract tenors, and hedging behavior.
- Product and R&D roadmaps: safety and regulatory trends are reshaping product specifications for coin, button, and small-format batteries used in medical and IoT devices.
- M&A and partnership screening: concentration metrics point to consolidation potential—especially for firms seeking rapid access to specialized chemistries or footprint expansion.
- Go-to-market differentiation: channel mixes and commercial service propositions (warranty, extended producer responsibility compliance) will determine near-term share shifts.
Key dynamics shaping 2026
- Raw material volatility: Lithium carbonate prices rebounded sharply in 2025 (moving from about ¥59,000/ton mid-year to over ¥130,000/ton by year-end), and industry consensus expects 2026 trading in a broad ¥80,000–150,000/ton range. That volatility magnifies input-cost risk for lithium-based small batteries and increases the value of long-term supplier agreements, tolling options, and alternative chemistry hedges.
- Regulatory tightening and safety standards: The EU Batteries Regulation (Reg. 2023/1542) continues to impose substance restrictions, labeling, and extended producer responsibility requirements that materially affect packaging, traceability, and compliance costs. Complementary standards—UL 4200A and IEC 60086-4:2025—raise safety-testing and ingestion-mitigation requirements for button and coin cells. Companies that treat compliance as a product differentiator (and not just a cost center) will win commercial trust in regulated markets.
- Product-level safety innovation: The recent introduction of taste-aversion (“bitter”) coatings by a major coin-cell supplier exemplifies how small, manufacturable changes can materially reduce product liability risk and unlock adoption in medical and child-sensitive applications.
- Technology and portfolio shifts: Lithium-based formats continue to grow in relevance for high-value commercial use cases (medical devices, IoT, backup power), but legacy chemistries remain important where total cost, recyclability, or regulatory regimes favor alternatives. Strategic portfolio balance—rather than single-chemistry bets—remains the resilient option for most commercial OEMs.
- Market structure and competition: Moderate concentration provides incumbents pricing power in stable segments while creating ingress points for challengers that pursue narrow verticals or regional strengths. The 2025–2026 tradeshow cycle and product launches signaled renewed interest from large lithium players and diversified battery manufacturers seeking small-format exposure.
Competitive landscape: how leading players are positioned
PW Consulting’s competitive analysis profiles established and specialty players across chemistry types, channel focus, and application depth. Highlights:
- Energizer Holdings (St. Louis): Broad commercial portfolio across alkaline, lithium, and coin cells—strong channel relationships in retail and industrial supply. Strengths are brand equity and scale; opportunities are deeper industrial OEM penetration and services-led propositions for B2B buyers.
- Duracell Inc. (Bethel): Iconic battery brand with recent safety innovations (bitter coating on selected coin sizes). Duracell’s brand and consumer-trust advantage can be leveraged into commercial medical and safety-critical applications with appropriate certification playbooks.
- Panasonic (Osaka): Technology breadth across lithium coin cells and rechargeable chemistries; deep OEM relationships in electronics and medical devices. Competitive edge comes from integrated manufacturing and materials know-how.
- VARTA (Ellwangen) & Maxell (Tokyo): Specialist strengths in micro and hearing-aid segments, with industrial positioning in medical and precision instruments. Their selective focus allows premium pricing in regulated niches.
- GP Batteries (Hong Kong): Regional manufacturing footprint serving both consumer and light-commercial segments—well-positioned for fast-turn procurement and regional rollouts.
- EnerSys, GS Yuasa, Power-Sonic: These firms emphasize sealed lead-acid and small-format VRLA/lithium products for standby, UPS, and industrial backup—critical for commercial sites where runtime and safety certifications matter.
- Murata, Renata, Toshiba: Suppliers that concentrate on coin and button cells for precision electronics and medical devices. Their value rests in miniaturization, consistency, and compliance documentation.
Across the board, we observe three strategic playbooks: (1) scale-and-reach incumbency (brand/channels), (2) niche-specialist premiumization (medical, hearing aids), and (3) supply-driven entry (raw-material or cell-technology integrators expanding into small formats). Each requires different commercial KPIs and investment timelines.
Five practical moves for executives in 2026
- Lock in diversified raw-material pathways: Combine multi-year purchase agreements for critical salts with spot exposure limits and a vendor-agnostic engineering bill of materials (EBOM) to permit chemistry substitutions where feasible.
- Design-to-regulation: Integrate EU Batteries Regulation and IEC/UL safety tests into product development sprints. Early regulatory qualification shortens time-to-contract for healthcare and public-sector customers.
- Operationalize safety as a commercial feature: Specify ingestion mitigation, tamper-proof packaging, and taste-aversion coatings in commercial tenders—convert safety into a price-justifiable service.
- Supplier scorecards and scenario clauses: Deploy scorecards that combine on-time delivery, compliance documentation, and life-cycle cost; include escalation and make-whole clauses for material-price shocks.
- Targeted M&A and partnerships: Pursue tuck-ins that add missing chemistries or regional footprints, and structure earn-outs tied to regulatory approvals and supply continuity milestones.
Scenario planning and sensitivity analysis
Our forecast model includes three policy-relevant scenarios: baseline (central macro assumptions), raw-material stress (prolonged high lithium carbonate pricing), and regulatory-constrained (accelerated EU/IEC/UL compliance costs). For each scenario we model top-line, gross margin sensitivity, and capex implications on a rolling 18–36-month planning horizon. Practical application: procurement teams can translate scenario outputs into specific contract tenors and inventory targets; product teams can use scenario triggers to defer or accelerate chemistry transitions.
What the full PW Consulting report delivers (practical, operational content)
- Detailed market model (2020–2032) with interactive scenario toggles and bottom-up volume/value build-ups.
- Regulatory and standards matrix (EU, UL, IEC) with compliance checklists and implementation timelines tailored to button/coin and small-format cells.
- Supplier benchmarking and scorecards across manufacturing footprint, testing capability, cost base, and EPR readiness.
- Cost build-up templates that convert raw-material price moves into SKU-level margin impacts.
- Procurement playbook and commercial contract templates (supplier KPIs, price-adjustment formulas, force-majeure clauses for raw-material shocks).
- Go-to-market playbooks by vertical (healthcare, industrial IoT, retail/PoS, security/alarms), including sales-handoff checklists and compliance qualification pathways.
- M&A screening tool with target profiles and valuation heuristics for strategic acquirers and financial sponsors.
Final note: how to use this intelligence in 90 days
Leaders should prioritize three actions in the coming quarter: (1) run a 90-day procurement stress-test using our raw-material stress scenario; (2) audit product portfolios against the IEC/UL/EU compliance matrix and prioritize safety-certification for top-revenue SKUs; (3) convene a shortlist of potential tuck-in targets or supply partnerships that fill chemistry or regional gaps. These steps convert PW Consulting’s strategic insights into measurable operational outcomes.
The summary here intentionally omits the granular segment-level numbers and regional/application splits that many transaction and procurement decisions require. PW Consulting’s full Commercial Small Batteries Market report contains the complete datasets, interactive forecast model, and all templates described above. Visit PW Consulting’s report page to access the comprehensive analysis, download the model, and schedule a briefing with our industry leads to translate the findings into a 2026 action plan.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Household Solid‑State Relay Market to Grow at a 7.66% CAGR, Reaching USD 721.25 Million by 2032
By pmarketresearch, 2026-07-06
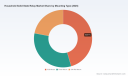
Household Solid State Relay Market 2026: Strategic Playbook for Executives — PW Consulting Release
Executive summary
PW Consulting today publishes its definitive industry outlook, Household Solid State Relay Market: Strategic Opportunities and Risks, providing senior executives, product leaders, and procurement teams with the market intelligence required to make high‑stakes decisions in 2026. Our analysis shows the household solid state relay (SSR) market has expanded rapidly over the past half‑decade — rising from approximately USD 305 million in 2020 to an estimated USD 430 million in our 2025 base year — and is projected to sustain healthy momentum through the 2026–2032 forecast window. We model a compound annual growth rate (CAGR) of 7.66% for 2026–2032, taking the market toward roughly USD 721 million by 2032 under our baseline scenario.
Household Solid State Relay Market
Why this matters for 2026 decision‑making
- Timing and scale: The market is no longer nascent — established suppliers and new entrants are competing across a widening set of household use cases. 2026 will be a pivotal year for locking in supplier relationships that will influence cost, reliability, and product feature roadmaps through the next product cycle.
- Supply chain concentration risk: Macro policy and raw material dynamics have elevated the strategic importance of supplier selection, qualification timelines, and inventory strategy. Executives who defer supply‑chain resilience efforts in 2026 risk production delays or cost escalation.
- Product differentiation: Silent operation, thermal management, and integration into home energy management systems are migrating from “nice‑to‑have” to procurement gatekeepers for appliance OEMs. Choosing the wrong SSR architecture or failing to validate lifecycle endurance can increase warranty exposure and brand risk.
What the PW Consulting report delivers — practical, transaction‑grade intelligence
This research is built for corporate action. We translate market dynamics into tools and frameworks that teams can deploy immediately:
Household Solid State Relay Market
- Scenario planning models that quantify the P&L impact of supply disruptions, tariff shocks, or component‑level material shortages across low‑, medium‑, and high‑adoption trajectories.
- Supplier heatmaps and qualification scorecards that speed vendor selection while scoring on reliability, technical fit, cost competitiveness, and geopolitical exposure.
- Technology readiness and substitution matrix to evaluate optocoupler, MOSFET, and other SSR architectures against household application requirements (noise, inrush handling, thermal footprint, and lifecycle).
- Regulatory and trade risk tracker tailored to SSR value chains — enabling procurement and government affairs teams to prioritize mitigation actions.
- Commercial playbooks (procurement negotiation templates, multi‑year hedging strategies, and inventory buffers calibrated to lead‑time volatility).
- A roadmap for product engineering teams including thermal test profiles, validation checklists, and recommended instrumentation for accelerated SSR qualification.
Competitive landscape — established players and strategic implications
The household SSR market is moderately concentrated. Our concentration analysis indicates leading vendors collectively hold meaningful share while leaving room for mid‑market specialists and component innovators to win niches. Key industry participants profiled in the report and their strategic positions are summarized below — each entry spotlights go‑to‑market implications for OEMs and suppliers evaluating partnerships in 2026.
Household Solid State Relay Market
- Omron Corporation (Kyoto, Japan): Offers compact PCB‑mount and panel‑mount SSRs suitable for temperature control and lighting. Omron’s depth in control electronics and brand recognition makes it a primary candidate for appliance makers seeking proven product lifecycle support and extensive global distribution.
- Panasonic Corporation (Osaka, Japan): Known for PhotoMOS and low‑power SSR variants optimized for consumer electronics. Panasonic’s strength is in miniaturized, low‑noise switching — attractive for premium appliance lines and integrated consumer devices.
- Carlo Gavazzi Holding AG (Steinhausen, Switzerland): Focuses on DIN‑rail and panel solutions targeting building automation and HVAC. Their mechanical form‑factor expertise and integrated thermal management suit OEMs that prioritize installation simplicity in retrofit and smart‑building contexts.
- Sensata Technologies (Crydom) (Attleboro, USA): Supplies industrial‑grade SSRs adaptable for high‑reliability household applications, including zero‑cross switching for noise‑sensitive environments. Sensata is a strategic partner for high‑end appliance lines where resilience and electrical performance are differentiators.
- Schneider Electric SE (Rueil‑Malmaison, France): Positions SSRs within modular home and building automation portfolios, offering systems integration benefits for customers pursuing energy‑management propositions.
- Siemens AG (Munich, Germany): Delivers SIRIUS series SSR/contactors for residential and light commercial HVAC applications, leveraging its strong channel and systems integration capabilities.
- ABB Ltd (Zurich, Switzerland): Integrates SSRs into power distribution solutions and energy management systems for the home, offering scale advantages to appliance OEMs seeking bundled energy‑management propositions.
- TE Connectivity (Schaffhausen, Switzerland): Provides vibration‑resistant SSRs for high‑cycle applications — suited to appliances with demanding mechanical environments.
- Vishay Intertechnology (Malvern, USA): Supplies optocoupler‑based and MOSFET SSRs for low‑power switching, attractive for compact consumer electronics and cost‑sensitive appliance segments.
- Littelfuse, Inc. (Chicago, USA): Offers high‑endurance SSR series for HVAC and appliance control, favoring customers emphasizing lifecycle durability.
- Celduc Relais (Sorbiers, France): Specializes in heating, lighting, and motor control SSRs for household and building automation — a contender for OEMs seeking tailored thermal control solutions.
- Fujitsu Limited (Tokyo, Japan): Targets compact SSRs for consumer electronics and home appliance circuits, aligning with manufacturers of space‑constrained products.
Recent industry developments that should influence 2026 planning
- Trade show activity in early 2026 saw vendors highlight semiconductor‑driven SSR innovations with increasing emphasis on thermal performance and integration — signaling ongoing product maturation and the emergence of differentiated features that will matter in procurement cycles.
- Product refreshes in 2024–2025 from select vendors focused on thermal performance improvements and electrical isolation, underscoring a supplier push to reduce field failures and improve installation flexibility.
- Regulatory and materials shocks — notably policy actions on critical semiconductor inputs and tariff adjustments — are already affecting component costlines and supplier risk profiles.
Industry context and risk factors
Two structural themes dominate the near‑term risk landscape:
- Raw material concentration: Production of certain gallium grades, a feedstock used in optoelectronic and power semiconductor components relevant to SSRs, is highly concentrated geographically. This creates asymmetric supply risk when export controls or licensing regimes tighten.
- Trade and policy volatility: Recent tariff escalations and executive actions targeting processed critical minerals and derivative products have materially increased the probability and potential impact of import restrictions. These dynamics can raise component costs, extend lead times, and force requalification of alternative parts.
For 2026, risk mitigation should be treated as a business‑critical investment, not a cost center: prioritizing alternative sourcing, creating qualified second‑source lists, and accelerating component requalification programs can materially reduce downside exposure.
Actionable strategies for market leaders and challengers in 2026
- Procurement playbook: Implement a two‑tier sourcing strategy combining long‑term strategic suppliers for core components and smaller, agile partners for capacity buffering; couple this with indexed short‑term contracts to hedge tariff volatility.
- Engineering and product strategy: Reassess SSR architecture choices against supply risk and lifecycle cost, and fast‑track design validation labs to compress qualification timelines to under 6 months where possible.
- Manufacturing and localization: Evaluate near‑shoring and assembly localization options to mitigate cross‑border logistics and tariff exposure; run cost‑benefit pilots that incorporate nonrecurring engineering and certification costs.
- Partnerships and M&A: Consider targeted partnerships or minority investments in component specialists to secure preferred access to critical technologies and inputs without full vertical integration.
- Regulatory and public affairs: Develop an evidence‑based advocacy posture and multi‑stakeholder strategy to influence import policy and critical minerals negotiations where national security dialogues intersect with commercial supply chains.
Methodology and data integrity
Our findings combine bottom‑up revenue modeling, primary vendor interviews, trade flow analysis, and a proprietary component‑level cost model. Historical series cover 2020–2025 with a 2025 base year; forward projections are presented across multiple scenarios to reflect demand elasticity, technology substitution, and potential policy shocks. Market concentration metrics and company profiles are based on observable shipment and revenue indicators supplemented by vendor disclosures and industry trade data.
Next steps — how to use this intelligence
PW Consulting’s Household Solid State Relay Market report is written for executives who must translate uncertainty into action in 2026. Use the report to:
- Inform supplier qualification and CAPEX decisions for the next generation of household appliances.
- Prioritize R&D and product roadmaps based on quantified market growth and risk scenarios.
- Construct a defensible procurement strategy that balances cost, resilience, and time‑to‑market.
Accessing the full intelligence
This publication is a strategic preview. To preserve the tactical advantage for subscribers, detailed regional and application segmentation, proprietary vendor scorecards, and the full financial tables are reserved for the complete report. To obtain the full dataset, interactive models, and the procurement playbook, please visit PW Consulting’s report page at pwconsulting.com/reports/household-solid-state-relay-market or contact our client services team for an executive briefing.
About PW Consulting
PW Consulting is a strategic advisory firm specializing in industrial electronics and supply‑chain resilience. We provide executive teams with decision‑ready research, scenario analyses, and implementation toolkits that bridge market foresight and operational execution.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intelligent Automatic Warehouse & Logistic Equipment Market Set to Expand at a Robust 12.04% CAGR During 2026–2032
By pmarketresearch, 2026-07-06
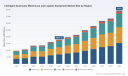
Intelligent Automatic Warehouse and Logistic Equipment: Strategic Imperatives for 2026 — PW Consulting Market Brief
As supply chains enter a new phase of digitization and capital-intensive modernization, executives must choose where and how to invest to capture productivity gains while managing cost, risk and regulatory exposure. PW Consulting’s latest market study on Intelligent Automatic Warehouse and Logistic Equipment synthesizes five years of historical performance and a seven-year forecast to 2032, delivering the operational intelligence leaders need to set 2026 strategy with confidence.
Intelligent Automatic Warehouse And Logistic Equipment Market
Market Trajectory — What the headline data tell us
The global intelligent automatic warehouse and logistics equipment market has roughly doubled in scale over the 2020–2025 period, reflecting accelerating adoption across fulfillment, manufacturing and omnichannel retail. Building on that momentum, our model projects continued high-growth through 2032 — a compound annual growth rate (CAGR) of 12.04% across the 2026–2032 forecast window, and a market poised to exceed USD 78 billion by the end of the decade.
Intelligent Automatic Warehouse And Logistic Equipment Market
For 2026 specifically, the market enters the year as a sizable and expanding opportunity: organizations that move early to validate automation concepts, shore up supplier relationships, and optimize total cost of ownership (TCO) will capture outsized gains in throughput, labor substitution and energy efficiency.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this report matters to 2026 decision-makers
- Decision timing is critical: with capital project lead times and supply-chain constraints, 2026 is the year to convert pilot learnings into scalable deployments. Our report identifies readiness indicators and decision gates that CFOs and COOs should use to prioritize capital allocation.
- Risk-adjusted procurement: rising raw material volatility and tariffs have increased project cost uncertainty. The report provides procurement playbooks and contract clauses to mitigate exposure to steel and aluminum price swings and trade policy actions.
- Technology vs. process choices: not every operation benefits from the same automation mix. We map capability tiers — from incremental conveyor and sortation upgrades to transformational robotics- and software-led redesigns — helping firms match solution archetypes to business goals and ROI horizons.
- Vendor selection under fragmentation: despite the market’s growth, concentration remains moderate — the top five providers account for roughly one-quarter of industry revenue. Buyers must therefore blend the stability of incumbents with the innovation of specialist entrants; our vendor framework scores suppliers across technical reach, integration capability, and commercial flexibility.
Practical, operationally-focused contents you’ll find in the report
- Executable deployment playbooks — step-by-step guides for pilot-to-scale transitions, including scope, KPI selection, and phasing strategies that minimize disruption to day-to-day operations.
- Commercial and financing models — TCO calculators, capex/opex optimization scenarios, and leasing vs. purchase decision matrices tailored to automation investments.
- Integration and software blueprints — recommended architectures for Warehouse Management Systems (WMS), Warehouse Execution Systems (WES), robotics orchestration, and APIs that de-risk multi-vendor rollouts.
- Supplier due diligence templates — scorecards, RFP templates and negotiation playbooks that expose hidden cost drivers and post-installation obligations.
- Workforce transition plans — reskilling roadmaps, change-management sequences, and productivity benchmarks to align labor strategy with automation adoption.
- Sustainability and compliance assessment — checklists and retrofit approaches to meet emerging energy-efficiency mandates and ESG reporting requirements without eroding economic returns.
- Scenario-driven forecasts — demand sensitivity analysis across macro and micro levers, enabling portfolio managers to stress-test investment cases under alternative economic and policy conditions.
Competitive landscape — who matters and why
The report analyzes the strategic positioning of established system integrators, robotics specialists and software-first players. It profiles market leaders and innovative challengers across capability axes — hardware breadth, software depth, global delivery footprint and integration speed — so procurement teams can align selection criteria to their operational tolerance for customization and time-to-value.
- System integrators and incumbents: Companies with long histories in material handling offer end-to-end solutions that reduce integration risk for large, high-throughput sites. Their scale advantages help in complex, multi-site rollouts and long-term maintenance contracts.
- Robotics and AMR specialists: Autonomous Mobile Robot (AMR) and AI-enabled robotics vendors bring flexibility and rapid redeployability, ideal for operations prioritizing agility and modular growth over lowest unit cost.
- Software-first entrants: Firms focused on orchestration and optimization software are shifting the value equation — enabling legacy equipment to perform smarter without a full rip-and-replace.
Recent industry activity underscores these trends: leading integrators and robotics vendors demonstrated new capabilities at trade exhibitions in early 2026, while thought leaders published fresh insights on multi-agent AI systems for warehouse orchestration. These developments point to an ecosystem moving towards tighter software-hardware co-design and faster innovation cycles.
Market dynamics shaping 2026 choices
- Cost inflation and tariffs: Steel and aluminum price increases, and specific tariff actions implemented in recent policy cycles, have raised up-front project costs. Procurement teams should demand transparent materials-cost escalators and consider hybrid procurement structures to hedge exposure.
- Labor pressure: Continued worker shortages and wage inflation in many logistics markets make automation an attractive substitute. Our ROI templates quantify labor displacement timelines and net productivity gains by operation type.
- Energy and ESG mandates: Regulatory pushes for energy-efficient operations favor solutions with regenerative drives, energy-aware scheduling and software-level optimization. The report offers retrofit pathways that reconcile sustainability targets with payback constraints.
- Supply-chain and lead-time risk: Component and lead-time variability requires contingency planning. We outline inventory, supplier diversification and phased-delivery strategies to keep project schedules intact.
Actionable 90–180 day roadmap for 2026
For executives who must make or influence automation investments in 2026, we provide a concise, prioritized sequence of actions that match capital planning cycles and procurement windows:
- 90-day actions: establish cross-functional governance, run a rapid site-readiness audit using our checklist, and issue a narrowly scoped RFP to validate vendor responsiveness and commercial terms.
- 90–180 day actions: complete one or two well-scoped pilot projects tied to measurable KPIs, lock favorable long-lead-time items under conditional purchase agreements, and finalize software integration contracts with clear SLAs.
- Beyond 180 days: scale deployments by phasing across sites with established playbooks, implement workforce reskilling programs, and transition from manual scheduling to dynamic, energy-aware orchestration.
What we intentionally withhold — and why
To preserve the commercial utility of the full study and to respect the confidentiality of detailed segmentation analyses, this brief intentionally omits granular regional and end-user shares, and detailed equipment-line revenue breakdowns. The full report contains detailed segment-level forecasts, vendor share matrices and downloadable financial models that buyers, investors and planners will find essential for procurement negotiations and board-level capital approvals.
Conclusion — the strategic value of informed timing
2026 represents a tipping point where automation can move from pilot projects to strategic capability. Companies that act with a risk-aware, data-driven playbook will realize faster payback, improved operational resilience and measurable sustainability benefits. PW Consulting’s Intelligent Automatic Warehouse and Logistic Equipment market study equips leaders with the frameworks, financial tools and supplier intelligence required to make those decisions — and to defend them to boards and investors.
Next steps
To access the full dataset, vendor scorecards, model templates and detailed segment forecasts needed to operationalize these insights, visit the official PW Consulting report page. The full deliverable includes executable artifacts designed for direct use in procurement, capital planning and operations meetings throughout 2026.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Composite Enclosures Market to Climb from USD 166.7 Million in 2025 to USD 269.8 Million by 2032 at a 7.12% CAGR
By pmarketresearch, 2026-07-06
Aircraft Composite Enclosures Market — Strategic Outlook for 2026 Decision-Making
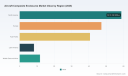
As airlines accelerate fleet renewal, avionics complexity increases, and defense platforms demand lighter, more resilient electronic housings, composite enclosures for aircraft electronics have moved from niche engineering choice to boardroom-level strategic variable. PW Consulting’s latest Aircraft Composite Enclosures Market report (base year 2025) synthesizes five years of historical trajectory and a seven‑year forecast to 2032, equipping executives with the market intelligence they need to make investment, sourcing, and partnership decisions in 2026. The market grew from under USD 100 million in 2020 to USD 166.7 million in 2025 and is projected to continue expanding to approximately USD 269.8 million by 2032 at a 7.12% CAGR (forecast period 2026–2032).
Aircraft Composite Enclosures Market
Why this market matters in 2026
-
Weight, EMI management, and environmental resilience are primary drivers. Composite enclosures deliver meaningful lifecycle advantages versus metal alternatives — not only in weight savings but in integration flexibility, corrosion resistance, and tailored RF/EMI properties.
Aircraft Composite Enclosures Market -
Supply-chain dynamics and raw-material volatility are elevating procurement risk to a strategic concern. Recent movements in epoxy resin and carbon-fiber markets are materially changing cost baselines for both OEMs and tier suppliers.
Aircraft Composite Enclosures Market -
Regulatory guidance and qualification requirements for composite avionics housings are converging with material capability, which shortens the window between prototyping and certification-ready production for firms that align engineering and compliance early.
Macro picture: growth, concentration and what it implies
PWC’s analysis shows a robust growth trajectory underpinned by aircraft modernization and electrification trends. The compound annual growth rate of 7.12% through 2032 is consistent with steady replacement cycles in commercial fleets, rising integration of electronics in cabins and cockpits, and increasing defense procurement of lighter, ruggedized systems.
Market concentration is moderate: leading suppliers hold a meaningful share but there remains room for differentiation through specialized materials, design-for-certification expertise, and integrated system solutions. This market structure creates distinct strategic pathways—scale-driven cost leadership for major suppliers, and high-margin technical niche plays for focused specialists.
What has changed since 2025 — near-term dynamics you must model now
-
Raw-material price shocks: Epoxy resin pricing in North America moved meaningfully upward in early 2026, with public reports showing a sharp quarterly rise driven by broader composite demand. Aerospace-grade carbon fiber price ranges also remain wide, underscoring the importance of supplier agreements that stabilize input costs.
-
Supply resilience via long-term agreements: Key industry actors are locking multi-year carbon-fiber contracts to protect program economics and delivery certainty. These agreements materially reduce lead-time and price volatility risk for companies that negotiate them early.
-
Regulatory clarity: Advisory circulars addressing composite structures and allowables have lowered technical ambiguity around qualification paths — a crucial enabler for turning engineered prototypes into certified avionics enclosures.
-
Strategic wins and partnerships: Recent commercial contracts and supply partnerships indicate accelerated adoption across naval and aerospace applications, validating crossover opportunities between marine gas-turbine housings and aircraft enclosure technology.
Actionable implications for 2026 corporate planning
For boards and executive teams, the 2026 planning horizon requires concrete moves in four areas:
-
Procurement and hedging: Revisit supplier mix and secure long-term raw-material agreements where cost exposure materially affects program margins. Scenario-run inputs for epoxy and carbon-fiber costs in CapEx/Opex models; sensitivity to +/- 10–20% swings changes IRR timelines on new programs.
-
Design-to-certification integration: Accelerate concurrent engineering between material scientists, structural analysts, and certification leads. The earlier FAA advisory guidance is baked into the design cycle, the lower the rework risk and time-to-market.
-
Portfolio and capability strategy: Decide whether to compete on vertically integrated solutions (materials + enclosure + systems integration) or to pursue high-value niche platforms that emphasize EMI shielding, thermal management, or high-voltage isolation. Each pathway requires different R&D and capital allocation profiles.
-
M&A and partnership focus: Given the market’s moderate concentration, targeted acquisitions—particularly of firms with validated certification packages or proprietary EMI-coating processes—can be the fastest route to differentiated capability without a multi-year internal build.
What PW Consulting’s report delivers (practical, implementable intelligence)
We designed the report as a decision-support tool for corporate leaders, procurement chiefs, and product heads. Key deliverables include:
-
Market sizing and rolling forecasts up to 2032 with scenario variations that stress-test pricing, supply disruption, and demand shocks.
-
Supplier risk matrix and a procurement playbook that translates raw-material price trajectories into contractual clauses, inventory strategies, and hedging actions.
-
Certification alignment checklist tied to FAA advisory guidance and military qualification expectations—actionable steps to reduce certification schedule risk.
-
Unit-cost build-ups and margin waterfall models for alternative material choices and manufacturing routes (autoclave cure vs. out-of-autoclave, molded vs. machined hybrid approaches).
-
Commercial go-to-market strategies for OEMs and tier suppliers, including pricing architecture, warranty exposure modeling, and service/repair economics for installed fleets.
-
M&A screening framework: scored targets based on IP strength, current certifications, customer stickiness, and geographic manufacturing risk.
Competitive landscape: who to watch and why
The competitive set includes global engineering-driven players, aerospace systems integrators, and specialty composite fabricators. A non-exhaustive strategic read on selected market participants:
-
TE Connectivity — A solutions-oriented supplier with a strong portfolio in lightweight composite enclosures and EMI shielding. Their strength is cross-domain expertise in connectors and housings, which enables integrated subsystem offers attractive to avionics OEMs focused on systems-level simplification.
-
Collins Aerospace — With deep program-level relationships across commercial and defense OEMs, Collins leverages systems engineering to embed composite enclosure solutions into larger avionics and thermal-management platforms. Their trajectory favors scale and certification muscle.
-
Carlisle Interconnect Technologies (Amphenol CIT) — Specializes in high-voltage and high-performance interconnect and enclosure applications. Their positioning is strong where enclosure design must meet demanding electrical isolation and form-factor constraints.
-
GE Aerospace — Recent contract awards in naval turbine enclosures highlight the cross-pollination of enclosure technology between maritime and aerospace platforms. Their program wins demonstrate how validated composite housings can be scaled across domains.
-
Automated Dynamics (Trelleborg) and RAMPF Group — Represent the high‑precision, custom-fabrication end of the market. These suppliers win work where EMI shielding, unique geometries, and small-batch qualification matter most.
-
AIM Aerospace and Kaman Aerospace (Vermont Composites) — Strong in structural and interior composite components; these firms can expand into enclosures where certification and production footprint are already in place.
Collectively, the market demonstrates both scale advantages for integrated suppliers and lucrative niches for materially differentiated players. Our concentration metric shows top players capture a meaningful share of the market, but not so much that a new entrant with the right certification and supply agreements couldn’t carve out a defensible position.
Risks, mitigations, and early warning signals
-
Raw-material inflation and allocation: Watch epoxy and carbon-fiber contract renewals closely. Early procurement commitments and secondary-sourcing agreements are effective mitigants.
-
Qualification delays: Track compliance milestones tied to advisory circulars and OEM validation timelines. Use staged qualification gates to limit sunk cost exposure.
-
Geopolitical and trade exposure: Diversify supply footprints and consider onshoring critical processes where program timelines or defense sensitivity require it.
-
Technology obsolescence: Monitor advances in conductive coatings, additive manufacturing for integrated enclosures, and hybrid metal-composite approaches that may disrupt traditional supply models.
How to use this intelligence in your 2026 planning cycle
-
For CEOs and CFOs — Run scenario models that include at least one high raw-material inflation case and one supply-disruption case; stress-test ROIs on new programs accordingly.
-
For CTOs and Chief Engineers — Prioritize design-for-certification and build a two-year prototype-to-qualification roadmap that maps to procurement milestones.
-
For Procurement and Strategy teams — Initiate or accelerate long-term supply agreements for carbon fiber and resins; demand contractual price-stability mechanisms and capacity reservations linked to program forecasts.
-
For M&A teams — Use our screening framework to identify targets that offer immediate certification benefits or proprietary EMI/thermal technologies that shorten time-to-revenue.
Concluding perspective: selective acceleration, not blanket investment
Composite enclosures are a high-conviction, mid-term growth opportunity for firms positioned to manage material costs and certification pathways. The market’s projected expansion through 2032 validates selective acceleration — executives should prioritize moves that de-risk supply and certification while preserving strategic optionality for future material and manufacturing innovations.
PW Consulting’s Aircraft Composite Enclosures Market report provides the practical models, supplier risk analytics, and playbooks needed to operationalize these conclusions in 2026. We intentionally present the high-level indicators and strategic implications above; the report contains detailed scenario spreadsheets, supplier scorecards, and the granular segmentation analyses that underpin these recommendations. Access to that intelligence will materially shorten your path from strategy to execution.
Next steps
-
Request the full report to obtain the detailed segmentation matrices, supplier scorecards, and executable procurement templates that are intentionally not reproduced here.
-
Contact PW Consulting to commission a tailored workshop: two days to translate report outputs into a prioritized 18‑month implementation plan specific to your fleet, supplier base, and certification roadmap.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Breaker Failure Relay Market Set to Grow at a 6.15% CAGR — Digital Relays Lead the Charge
By pmarketresearch, 2026-07-06
Breaker Failure Relay Market 2026: Strategic Insights to Inform Executive Decisions
As energy systems become more automated, interconnected, and mission-critical, the role of breaker failure protection has shifted from a niche safety function to a strategic reliability lever. PW Consulting’s latest market research — covering historical trends (2020–2025) and a forward-looking forecast (2026–2032) — delivers an evidence-based playbook for executives, product leaders, and system operators preparing decisions in 2026. This executive summary outlines why the breaker failure relay market matters to enterprise strategy, the high-level directional data you need today, and the practical actions that will preserve operational continuity and unlock commercial advantage.
Breaker Failure Relay Market
Why breaker failure relays are strategic in 2026
-
Operational resiliency is now a board-level priority. Breaker failure events, once regarded as low-frequency operational nuisances, are explicitly classified and tracked under contemporary reporting regimes. The increasing regulatory and compliance attention on abnormal clearing events elevates breaker failure protection from engineering detail to enterprise risk management.
Breaker Failure Relay Market -
Technology convergence is compressing vendor boundaries. Numerical and multifunction relays are absorbing traditional standalone breaker failure functionality, driven by digital substation standards and cybersecurity requirements. This reduces the tolerance for legacy one-function devices and reshapes procurement and lifecycle strategies.
Breaker Failure Relay Market -
Market dynamics present both stability and consolidation signals. The market demonstrates steady growth underpinned by predictable grid modernization cycles and regulatory reporting updates, while the top-tier vendors maintain significant aggregate share — creating a competitive field where differentiation is increasingly product- and services-driven.
Key macro metrics (directional, actionable)
-
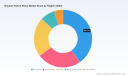
Market trajectory: The breaker failure relay market showed consistent expansion from 2020 through 2025, growing from an estimated USD 410.5 Million in 2020 to USD 541.8 Million in 2025.
-
Near-term projection: With the next planning horizon beginning in 2026, our model projects continued expansion across 2026–2032, with annualized growth consistent with a compound annual growth rate (CAGR) of approximately 6.15% across the forecast window.
-
Scale by 2032: Under base-case assumptions, the market is expected to approach the high hundreds of millions in USD by the end of the forecast period, driven by upgrades, renewals, and functional migration into multifunction platforms.
-
Concentration: Market concentration is material — the top three suppliers account for a meaningful portion of market revenue, while the top five capture a clear majority. This shapes pricing power, channel dynamics, and M&A rationale.
Competitive landscape — what matters to buyers and strategists
Our sector review profiles incumbent protection vendors and the strategic moves that matter for procurement, alliances, and R&D prioritization. Leading suppliers demonstrate two consistent behaviors: integration of breaker failure functions into broader protection platforms and sustained technical engagement with standards and operator communities.
-
Schweitzer Engineering Laboratories (SEL) — SEL’s portfolio and continued engagement with technical conferences underline a go-to-market approach focused on deep domain credibility and field-proven products. Their active presence in practitioner forums keeps them close to evolving protection philosophies and implementation practices (selinc.com).
-
Toshiba — With numerical breaker failure solutions intended for complex busbar and redundant schemes, Toshiba remains relevant for utilities and industrial operators seeking integrated relay solutions that work in varied substation topologies (global.toshiba).
-
Siemens — Siemens’ SIPROTEC family represents the multifunction trend: protection, breaker management, and automation converge into modular platform offerings suitable for medium to extra-high voltage environments (siemens.com).
-
ABB / Hitachi Energy — Their combined product strategies emphasize both standalone and embedded breaker failure functions across protection series, reflecting an approach that balances retrofit markets and greenfield automation projects (hitachienergy.com).
-
Schneider Electric, Basler Electric (Littelfuse), and GE Vernova — Each brings specific propositions: integration into power management ecosystems, compact retrofit relays for distribution segments, and multifunction relay integration strategies respectively. Collectively, these suppliers define the practical choice space for asset owners.
Regulatory and standards context shaping 2026 decisions
-
Standards evolution: IEEE guidance has broadened the scope of recommended breaker failure approaches to include generator unit breakers and non-fault initiations, encouraging architectures and test regimes that minimize single points of failure.
-
Reporting expectations: Regional transmission reporting frameworks now classify breaker failure events as a distinct event type with specified reporting requirements. This raises the cost of poor visibility and the value of precise instrumentation and logging.
-
Operational practice: The convergence of breaker failure detection into multifunction relays is driven by substation automation standards (e.g., IEC 61850) and cybersecurity regimes. For asset owners, compliance and interoperability planning must be integral to procurement and upgrade roadmaps.
Where the practical value sits in the full report
PW Consulting’s full report converts market geometry and technical dynamics into executable tools for decision-makers. Highlights include:
-
Procurement playbooks — Decision matrices that align protection requirements (speed, redundancy, logging) to vendor solution classes and total cost of ownership approaches for retrofit vs. greenfield deployment.
-
Upgrade sequencing frameworks — Prioritized pathways for replacing legacy standalones with multifunction numerical relays to balance capital intensity against risk reduction and operational benefits.
-
Vendor scorecards — Comparative assessment criteria that weigh technical capability, service footprint, standards conformance, and long-term support commitments.
-
Scenario stress-tests — Impact matrices that quantify how regulatory reporting changes, renewed inspection regimes, or a shift toward IEC 61850 could influence replacement cycles, OPEX, and incident exposure.
Strategic implications and recommended actions for 2026
-
Reframe protection investments as resilience capex. Treat breaker failure capability not merely as a functional procurement line item, but as an insurance lever tied to outage risk and regulatory exposure. Prioritize assets where single-breaker failure would cascade into high-consequence events.
-
Adopt a phased consolidation to multifunction relays. Target critical substations and generator switchgear for early migration, using a staged plan that captures interoperability gains (IEC 61850) and simplifies maintenance contracts.
-
Negotiate service-centric vendor agreements. Given the concentration among leading suppliers, secure commitments for lifecycle firmware support, event-data access, and joint testing to reduce vendor lock-in and maintain visibility for compliance reporting.
-
Strengthen event logging and analytics contracts. Regulatory reporting requires auditable event records. Investing in high-fidelity recording and analytics yields direct returns: faster root-cause analysis, lower follow-up outage risk, and better regulator interactions.
-
Pursue tactical M&A or partnerships if you are a supplier. For vendors, the path to scale and feature breadth increasingly goes through software-enabled services, strategic partnerships with sensor/C&T suppliers, or acquisitions that accelerate IEC 61850 and cybersecurity competencies.
Risk factors to monitor
-
Component and supply chain — Breaker failure relays depend on semiconductor and sensor supply chains. While our review did not identify acute shortages specific to this niche, firms should maintain supplier diversity and lifecycle inventories for critical microprocessor and CT components.
-
Standards and reporting changes — Evolving guidance and event classification practices can alter the compliance baseline rapidly; align monitoring functions to capture revisions and test compliance scenarios.
-
Technology migration pace — Overly aggressive rip-and-replace programs can be cost-inefficient; conversely, lagging on integration with digital substations can increase cyber and interoperability risk.
Recent signals worth immediate attention
-
Industry knowledge exchange remains active. Vendors and academia continue to converge through conferences and training forums where implementation best practices are exchanged. Building relationships with these knowledge hubs accelerates operational learning curves.
-
Reporting instructions have been clarified recently at regional transmission authorities, increasing the granularity and traceability required for breaker failure events. Facilities with marginal logging capabilities should prioritize upgrades.
Conclusion — What executives should do in the next 90–180 days
-
Run a prioritized inventory audit of high-consequence breakers and their protection architectures.
-
Engage shortlisted suppliers for proof-of-concept demonstrations focusing on event logging, interoperability, and lifecycle support guarantees.
-
Update risk registers and compliance roadmaps to reflect new reporting expectations and consider reallocating near-term capital toward targeted protection upgrades rather than broad, unfocused replacement programs.
PW Consulting’s full Breaker Failure Relay Market report contains the granular regional, application, and vendor-split data that informs precise budgeting and procurement strategies. This briefing is intentionally selective — offering the strategic context and high-level metrics to inform executive decisions while pointing technical teams to the full dataset for implementation planning. Visit our report page to access the comprehensive dataset, vendor scorecards, and the procurement playbook that will operationalize these insights for 2026.
For detailed analysis of this topic, please visit the official page: Breaker Failure Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fully Automatic Full‑Screen Laser Cutting Equipment Market to Grow at 7.46% CAGR, Expanding from USD 748.5 Million in 2025
By pmarketresearch, 2026-07-06
Fully Automatic Full Screen Laser Cutting Equipment Market: Strategic Outlook for 2026 Decisions
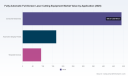
PW Consulting today releases a strategic preview of our forthcoming market research report on the Fully Automatic Full Screen Laser Cutting Equipment market. Grounded in a detailed historical review (2020–2025) and a rigorous forecast (2026–2032), this analysis is designed to equip executive teams with the foresight needed to make high-conviction decisions in 2026. The global market, measured in USD Million, recorded a base-year size of 748.5 (2025) and is projected to grow at a compounded annual growth rate (CAGR) of 7.46% across our forecast window — reaching a modeled market size of approximately 1,238.4 by 2032.
Fully Automatic Full Screen Laser Cutting Equipment Market
Why this market matters to CEOs and strategy teams in 2026
-
Transition point for industrial automation: Manufacturers across consumer electronics, displays, and precision components are accelerating investments in fully automatic full-screen laser systems to compress cycle times and improve yield.
Fully Automatic Full Screen Laser Cutting Equipment Market -
Technology-led differentiation: Advances in ultrafast and solid-state laser sources, combined with machine-level and plant-level automation, are redefining cost-to-serve and enabling new product form factors.
Fully Automatic Full Screen Laser Cutting Equipment Market -
Capital planning implications: With the market expanding from a 2025 base of USD 748.5 Million toward our 2032 projection, procurement, CAPEX timing, and financing strategies must account for a multi-year productivity and obsolescence curve.
What the report delivers — operational, actionable intelligence (high level)
-
Robust market sizing and scenario-based forecasting methodology that reconciles bottom-up equipment shipments with top-down macro drivers — presented with transparent assumptions suitable for CFO-level stress-testing.
-
Practical segmentation frameworks (by region, laser source, and application) and an operational taxonomy that aligns purchasing decision trees with production use-cases and lifetime cost of ownership (LCO).
-
Competitor benchmarking and capability maps that highlight not only market share positions but also technology stacks, automation footprints, and aftermarket service models.
-
Supply-chain risk heatmaps and mitigations — including sensitivity to raw material price volatility and component lead-time shocks — enabling procurement and operations teams to prioritize dual-sourcing and inventory strategies.
-
Go-to-market playbooks for OEMs, system integrators, and end-users: procurement timing, service bundling, retrofit pathways, and scenario-triggered investment thresholds.
-
M&A and partnership screening criteria emphasizing strategic fits based on automation IP, regional service coverage, and installed-base conversion potential.
Market dynamics that will shape 2026 strategies
-
Automation adoption and productivity demands: The industry-wide shift to higher automation is accelerating demand for fully automatic full-screen systems. For manufacturers focused on throughput and consistency, this creates a stronger economic case for replacement cycles and higher-capacity purchases.
-
Energy efficiency and regulation: Regulatory pressure and internal sustainability targets are pushing buyers toward energy-efficient fiber and solid-state laser sources. Expect procurement teams to require energy-performance metrics and lifecycle emissions profiles as part of tender evaluations.
-
Raw material and component cost variability: Fluctuations in steel, aluminum, and specialty optical components influence total cost of ownership and capital budgeting. The report provides sensitivity analyses that link raw material price scenarios to payback periods and lease-versus-buy decisions.
-
Concentration and competition: The market exhibits moderate-to-high concentration at the top. Our modeling indicates that the three largest suppliers hold a meaningful portion of available commercial demand, while the top five together represent a larger share. This structure has implications for pricing dynamics, service competition, and consolidation opportunities.
Competitive landscape — implications for 2026 positioning
Leading manufacturers and system integrators vary by technological emphasis, geographic reach, and aftermarket strategies. Below we synthesize strategic takeaways for each archetype represented by core industry players.
-
High-power fiber specialists (e.g., Farley Laserlab / HGTECH affiliate) : These firms excel in large-format, high-throughput systems and tend to win in industrial, sheet- and tube-processing environments. Their competitive edge is scale and integrated automation; however, buyers should probe service network density in their target markets and the supplier’s roadmap for energy-efficiency improvements.
-
Full-range Chinese OEMs (e.g., Han’s Yueming, Kunshan Dapeng, Beijing Torch SMT) : These suppliers offer breadth and price competitiveness across multiple applications. They are strong contenders for volume-driven programs, but strategic buyers will want to validate quality-management processes, IP ownership, and long-term support commitments.
-
Established global industrial brands (e.g., Mitsubishi Electric) : With deep R&D and reliable global service footprints, these players are preferred where precision, integration with existing MES/PLM systems, and total-cost-of-ownership predictability are priorities. Their offerings often command premium pricing aligned with lower operational risk.
-
Specialized precision system providers (e.g., Control Micro Systems, EBSO GmbH) : These companies are attractive for niche high-precision and research-intensive applications, with robust customization capabilities. They can be preferred partners for pilot projects and co-development but may require longer integration timelines.
-
Automation-first suppliers (e.g., Aurotek, ASYS GROUP) : These players integrate laser systems with upstream/downstream automation and provide compelling value for smart-factory deployments. For manufacturers pursuing Industry 4.0 trajectories, their bundled solutions can shorten implementation cycles.
Strategic recommendations for 2026 decision-makers
-
Adopt a hybrid procurement posture: Combine immediate investments in standardized high-uptime platforms with modular pilot investments in ultrafast and niche solid-state systems. This balances near-term productivity gains with optionality for emerging production requirements.
-
Prioritize aftermarket economics: Given the importance of installed-base uptime, structure supplier contracts to include performance SLAs, local spares staging, and predictive maintenance agreements. This often delivers greater ROI than marginal equipment price concessions.
-
Stress-test supply-chain exposure: Use the report’s scenario tools to model capital projects under raw material and component availability shocks. Where exposure is high, consider pre-purchasing critical subsystems or negotiating inventory-risk sharing with key suppliers.
-
Design integration-first RFPs: Ensure procurement specifications require open integration points with MES/ERP systems, energy-performance guarantees, and upgrade pathways to protect against rapid obsolescence.
-
Engage in selective partnerships: For OEMs and system integrators, prioritize partnerships that expand geographic service reach and digital maintenance capabilities rather than purely transactional supply agreements.
-
Use concentration information tactically: The market’s top-tier concentration creates both risks and opportunities — incumbent suppliers may be less price-sensitive but can be weaker at rapid customization; challenger suppliers provide agility but may lack scale. Balance vendor portfolios appropriately.
Scenario planning and investment timing
Our forecasting framework presents multiple adoption scenarios tied to macroeconomic growth, capital-availability, and the pace of automation uptake. Across scenarios, the baseline case — driven by continued automation investment and incremental efficiency mandates — supports a steady upward trajectory consistent with the stated CAGR of 7.46% from the 2025 base. For 2026 planning, the key variables to monitor are interest-rate movements affecting CAPEX financing, raw material price volatility, and the speed of regulatory shifts toward energy-efficiency standards.
How to use this preview — next steps for executive teams
-
Procurement leads: Use the report’s LCO templates and service-cost breakdowns to re-run your 3–5 year refresh plan and adjust timing to capture efficiency improvements with acceptable payback horizons.
-
R&D and product strategy teams: Map your roadmap against supplier technology stacks and identify where partnerships or acquisitions would create defensible differentiation in automation, optics, or software control systems.
-
Corporate development teams: Leverage the competitor benchmarking and concentration analysis to prioritize M&A targets and JV partners that expand installed-base service capabilities or accelerate entry into high-growth application segments.
Closing — access to the full intelligence
This briefing highlights the strategic lens PW Consulting applies to the Fully Automatic Full Screen Laser Cutting Equipment market: rigorous quantitative forecasting, deep operational analysis, and decision-ready recommendations. We intentionally present high-level findings here to demonstrate analytical rigor while preserving the detailed segment-level breakdowns, supplier scorecards, and proprietary scenario models for full-report subscribers. For companies preparing capital allocation, procurement cycles, or partnership strategies in 2026, the complete report contains the granular inputs and downloadable tools required to operationalize these insights.
To obtain the full report and unlock the detailed datasets, segmentation tables, and vendor scorecards referenced in this preview, please visit our official report page or contact PW Consulting’s industry practice team for a briefing tailored to your organization’s needs.
For detailed analysis of this topic, please visit the official page: Fully Automatic Full Screen Laser Cutting Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts ORC Waste Heat-to-Power Market to Accelerate at 10.65% CAGR, Transforming Industrial Energy Recovery Through 2032
By pmarketresearch, 2026-07-06
Organic Rankine Cycle Waste Heat to Power: Strategic Imperatives for 2026 — PW Consulting Market Brief
As energy-intensive industries confront volatile fuel markets, tightening emissions rules, and an urgent decarbonization timetable, Organic Rankine Cycle (ORC) waste heat to power (WHtP) systems have moved from niche pilots to deployable industrial solutions. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — quantifies this transition and, more importantly, translates it into concrete decision‑making guidance for corporate strategists, project developers, and investors preparing plans in 2026.
Organic Rankine Cycle Waste Heat To Power Market
Market snapshot: scale, trajectory, and what it means for corporate planning
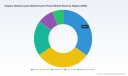
The ORC WHtP market has entered a phase of sustained expansion. Our analysis shows the market reached an estimated USD 4.8 billion (base year 2025) and is projected to grow at a compound annual growth rate (CAGR) of 10.65% through 2032, reaching close to USD 9.75 billion by the end of the forecast period. This trajectory reflects accelerating unit deployments, broader temperature-range applicability, and improved project economics driven by higher energy prices and policy incentives.
Organic Rankine Cycle Waste Heat To Power Market
For executives evaluating capital allocation in 2026, three implications flow directly from this macro trend:
Organic Rankine Cycle Waste Heat To Power Market
- Scale economies are emerging but the market remains far from consolidated — leading vendors account for a minority share of global activity. Our concentration metrics confirm a market where the top three and five vendors do not dominate, leaving ample room for new entrants, partnerships, and localized supply strategies.
- Total addressable opportunity is large enough to justify internal capability development (technical, commercial, and O&M) for industrial groups with continuous waste heat streams, but site selection and contract structures will determine which projects are attractive in 2026 vs. later years.
- Policy and fluid‑technology risks are now a core part of project underwriting. Regulatory moves to restrict certain HFC/PFAS working fluids and stronger industrial‑efficiency mandates create both upside (incentives, accelerated permitting) and transition costs (retooling, repowering).
What this PW Consulting report delivers — operational, actionable intelligence
The public summary will not replace direct engagement with the study, but the core of our offering is practical, decision‑grade content designed for use in 2026 bidbooks, CAPEX committees, and M&A diligences. Key deliverables include:
- Market forecast model (2026–2032) with scenario layers: baseline, high‑adoption, and policy‑stressed outcomes — delivered as a downloadable, editable workbook so corporate planners can run their own sensitivity analyses against electricity price, operating hours, and capital cost assumptions.
- An investment playbook and project screening toolkit that operationalizes payback thresholds, financing levers, and commercially realistic dispatch strategies for baseload vs. complementary power generation.
- Vendor benchmarking and procurement templates: capability maps, scopes of supply, and negotiation checklists tailored to ORC procurements across typical industrial EPC cycles.
- Technical deep dives into ORC sub‑systems — expander/turbine types, heat‑exchanger architectures, working‑fluid tradeoffs, and modularization — with practical guidance on lifecycle O&M and repower pathways.
- Regulatory and supply‑chain risk mapping, including scenario planning for fluid restrictions and critical‑component lead times, plus mitigation strategies (fluid transition roadmaps, dual‑supplier sourcing).
- Case studies and validated ROI models built from real industrial deployments — enabling capital committees to translate vendor quotes into board‑grade financials (IRR, NPV, simple payback under multiple tariffs and operating regimes).
Competitive landscape: who matters and how to position in 2026
The ORC vendor field is populated by a mix of pure‑plays, industrial incumbents, and specialist component suppliers. Our report profiles the leading names that are shaping industrial deployment strategies and competitive dynamics.
- Ormat Technologies Inc. (Reno, Nevada, USA; https://www.ormat.com) — a recognized leader in recovered energy generation systems. Ormat’s proprietary energy converters and integrated project capabilities make it a natural choice for customers seeking an end‑to‑end partner with track record in industrial REG applications. For buyers, Ormat represents lower integration risk but typically commands a premium for its packaged offering.
- Turboden S.p.A. (Mitsubishi Heavy Industries Group — Brescia, Italy; https://www.turboden.com) — strong in large‑scale turbogenerators and energy‑intensive sectors. Recent high‑visibility projects — including North America’s first large WHtP plant at a SAGD facility and new awards for compressor‑station deployments — highlight Turboden’s ability to scale in both heavy‑industry and oil & gas upstream contexts. Partnerships with major industrials and EPCs are a differentiator.
- Exergy International Srl (Olgiate Olona, Italy; https://www.exergy-orc.com) — noted for its Radial Outflow Turbine (ROT) technology and mid‑size units. Exergy is frequently selected where turbine efficiency and compact footprint are decisive; its solutions appeal to cement and chemical plants seeking attractive payback profiles.
- ElectraTherm Inc. (BITZER Group — Flowery Branch, Georgia, USA; https://electratherm.com) and ENOGIA SAS (Marseille, France; https://enogia.com) — both specialists in low‑temperature and micro‑ORC segments. Their modular offerings enable projects on lower‑grade heat streams that previously were uneconomic, unlocking a new tranche of small‑scale deployments.
- Orcan Energy AG (Munich, Germany; https://www.orcan-energy.com), Calnetix Technologies LLC (Cerritos, California, USA; https://www.calnetix.com), and large heat‑transfer suppliers like Alfa Laval AB (Lund, Sweden; https://www.alfalaval.com) — these players are central to system modularization, heat‑exchanger optimization, and advanced rotating‑machinery solutions. Their roles are increasingly important in integrated supply models and aftermarket service agreements.
In short, procurement strategies in 2026 should acknowledge that vendors vary not only by technology but by commercial posture: turnkey integrators, OEMs selling to EPCs, and component specialists. Our vendor scorecards in the report map these vectors against risk tolerances and CAPEX/late‑stage O&M preferences.
Technology, policy, and operational risks that will shape 2026 execution
Three risk vectors must be actively managed in project development and portfolio prioritization:
- Working‑fluid and chemical‑regulation risk. Regulatory movements in Europe and elsewhere around HFCs/PFAS can force mid‑lifecycle fluid changes, with capex and downtime implications. The report provides a transition playbook and supplier readiness matrix so project teams can pre‑emptively select fluids and hardware architectures that minimize stranded‑asset risks.
- Project economics sensitivity to operating hours and electricity tariffs. Industrial payback periods for many cement and steel applications typically cluster in the multi‑year band — our benchmarking and sensitivity tools let CFOs test tariff shocks and curtailment risk to prioritize sites with the highest risk‑adjusted returns.
- Supply chain and installation complexity. Larger ORC units and multi‑MW installations carry longer lead times and require advanced integration planning; conversely, micro‑ORC and modular packs present fast‑track opportunities. Our schedule impact templates quantify expected EPC timelines and typical schedule variance by capacity band.
Actionable 2026 playbook: five recommended moves for corporate decision‑makers
- Undertake a one‑year “heat asset audit” across manufacturing and process sites to quantify continuous vs. intermittent waste heat and prioritize sites by hours‑of‑operation, steam/economizer temperatures, and grid tariff exposure. Use the PW Consulting screening template to produce board‑grade site shortlists.
- Pursue staged procurements: pilot modular systems at 1–5 MW equivalent sites to validate operating assumptions, then scale up via framework agreements with primary vendors to capture learning‑curve cost reductions.
- Embed fluid‑transition clauses into procurement and service contracts to limit exposure from potential regulatory changes. The report provides contract language examples and vendor negotiation points for 2026 RFPs.
- Structure financing around performance guarantees and energy‑service models (ESCOs) where possible to accelerate adoption while protecting balance sheets. The financial annex includes example deal structures and indicative debt sizing approaches used in 2025‑2026 transactions.
- Design an aftermarket and repower roadmap at the outset—covering monitoring, predictive maintenance, and future fluid replacement—to preserve project value over two decades of operation.
Why PW Consulting’s study is strategically different
Beyond headline forecasts and vendor lists, PW Consulting’s ORC WHtP study is built for application: editable financial models, procurement playbooks, vendor scorecards, and legally minded procurement language. Its focus is on enabling 2026 decisions — not just measuring market size. To maintain the integrity of client engagement and commercial confidentiality, the public brief intentionally omits full regional and application split tables and certain granular unit economics; these are available in the complete report and accompanying datasets.
Next steps for executives
If your organization is evaluating WHtP options in 2026 — whether through CAPEX deployment, energy service agreements, or strategic partnerships with ORC vendors — PW Consulting’s full report provides the modeling, vendor insight, and contractual tools needed to move from concept to sanctioned project. The public summary above outlines the strategic landscape; the full deliverable contains the data‑rich annexes and executable tools required to de‑risk board decisions and accelerate deployment.
Contact PW Consulting to obtain access to the full ORC Waste Heat to Power Market report, the editable forecast model, and our procurement toolkits. For immediate priority guidance, our experienced industry advisors are available for short, targeted workshops to translate the study’s insights directly into your 2026 project pipeline and capital planning cycle.
For detailed analysis of this topic, please visit the official page: Organic Rankine Cycle Waste Heat To Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com