

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Water-Based Acrylic Emulsion Market to Reach USD 11.08 Billion in 2025

Water‑Based Acrylic Emulsion Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
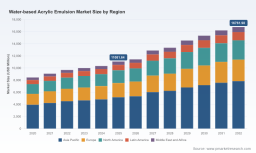
PW Consulting’s latest market study on the Water‑Based Acrylic Emulsion industry synthesizes five years of historical performance (2020–2025) and a forward-looking model for 2026–2032 to equip senior executives with the actionable intelligence required for 2026 capital, product, and commercial choices. The macro story is straightforward: the addressable market expanded from roughly USD 8.45 billion in 2020 to an estimated USD 11.08 billion in 2025 and continues to accelerate under structural tailwinds. Our forecast model projects a compound annual growth rate of 6.09% across the 2026–2032 horizon, with an end‑period market value approaching USD 16.76 billion. These headline dynamics mask important tactical inflection points that will determine winners and losers in the next 18 months.
Water Based Acrylic Emulsion Market
Why this matters for 2026 decision‑makers
-
Regulatory tightening, raw‑material volatility, and evolving sustainability requirements are compressing time‑to‑market for compliant waterborne solutions; companies that act in 2026 will convert compliance obligations into market share.
Water Based Acrylic Emulsion Market -
Moderate market concentration (CR3 ~38.3%; CR5 ~54.1%) creates space for well‑executed regional scaleups, targeted product differentiation, and acquisitive consolidation—especially in specialty emulsions and customized industrial grades.
Water Based Acrylic Emulsion Market -
Margin expansion will be driven less by top‑line growth and more by raw‑material management, formulation premiumization (low‑VOC, PFAS‑free, bio‑based), and localized supply to shorten lead times for coatings and adhesives customers.
Key market dynamics shaping 2026 strategy
-
Regulatory pressure is an accelerant. Tighter VOC standards (including recent U.S. EPA aerosol coating rules and mounting state‑level limits) have made waterborne acrylics a compliance imperative for many customers. PFAS‑free and APE‑free formulations are quickly becoming market entry criteria rather than differentiators.
-
Raw‑material complexity is increasing. Acrylic acid—a primary upstream feedstock—has shown regionally divergent price behavior and periodic volatility. Our modelling shows that price moves at the acrylic acid level transmit quickly to producer margins unless mitigated by hedging, local integration, or formula redesigns.
-
Product innovation is the new battleground. Demand is bifurcating between standard architectural grades and premium high‑performance emulsions (durability, dirt resistance, lower VOC, bio‑content). R&D and application engineering capabilities are becoming equivalent to manufacturing scale as determinants of share gains.
-
Supply architecture is regionalizing. Customers increasingly prize short lead times and regulatory assurance; this favors mid‑sized players that can deploy regional reactors and service models close to end markets, while large global producers pursue strategic capacity additions.
Competitive landscape — what to watch in 2026
The market remains a mix of global chemical majors, regional specialists, and agile niche formulators. Leading incumbents are pursuing a three‑pronged go‑to‑market playbook: (1) capacity and geographic expansion to meet construction and industrial demand; (2) portfolio moves toward low‑VOC and bio‑based grades; and (3) targeted partnerships and product launches that accelerate time‑to‑market for compliant systems.
-
BASF continues to extend its broad water‑borne portfolio and has prioritized low‑VOC and bio‑based grades with capacity investments in Asia—an example of integrated multi‑market scale strategy.
-
Dow has combined product launches with North American capacity increases to serve construction and automotive value chains; its recent next‑generation emulsion launch (Sept 2025) underscores a strategy focused on performance plus regulatory compliance.
-
Arkema is moving toward low‑carbon routes via partnerships to commercialize bio‑based resins, reflecting an industry trend where “sustainable” technology alliances accelerate commercialization.
-
Lubrizol, Celanese, Synthomer, and other established suppliers are balancing investments in innovation and regional capacity to protect existing customer relationships while pursuing specialty niches.
-
Regional specialists and formulators (for example, long‑tenured U.S. and European players and agile vendors in Turkey, Japan, and beyond) are targeting rapid wins in specialty adhesives, industrial coatings, and non‑woven applications where customization commands premiums.
Recent industry moves bear watching for strategic knock‑on effects: product launches focused on reduced VOC and enhanced durability (Sept 2025), bio‑based partnerships (Sept 2025), and ongoing capacity investments (2024–2025) that materially alter local supply/demand balances. PW Consulting’s proprietary timeline maps these events against price and demand indicators to expose 6–12 month windows of opportunity.
Operational playbook — five priority actions for 2026
-
Rebalance portfolios to emphasize compliant premium grades. Prioritize development and commercialization of PFAS‑free, fluorosurfactant‑free, low‑VOC formulations and certified bio‑content where customers will pay a premium or require compliance evidence.
-
Hedge and localize feedstock exposure. Implement systematic acrylic‑acid exposure hedging and assess backward integration or tolling contracts in key regions to stabilize margin. Scenario analyses in our model show that a sustained 5–10% swing in acrylic acid costs can materially compress EBITDA for unprotected plants.
-
Accelerate regional capacity and service points. Shorter lead times and regulatory assurance are decision drivers for coatings formulators and distributors. A focused regional expansion program—paired with digital order orchestration—delivers outsized commercial returns.
-
Prioritize fast, reversible capital. In a market evolving with regulation and raw material swings, invest in modular reactors, flexible formulary capability, and toll manufacturing arrangements to change course quickly without long stranded assets.
-
Use M&A tactically. Given the mid‑tier concentration and the presence of high‑value niche specialists, acquisitive buyers should prefer targets that add formulation IP, regulatory dossiers, or regional customer networks rather than just incremental capacity.
What PW Consulting’s report delivers — practical, executable modules
This is not a high‑level overview; the report is engineered for decision execution in 2026. Core deliverables include:
-
A detailed market model (2020–2032) with base‑case and three alternative scenarios that quantify the impacts of acrylic acid price swings, regulatory tightening, and faster uptake of bio‑based grades.
-
Supplier scorecards and strategic heatmaps highlighting capability gaps, capacity timelines, and technology differentiators across the competitive set—covering product development velocity, regulatory readiness, and regional supply footprints.
-
Commercial playbooks for coatings, adhesives, and industrial customers with pricing elasticity estimates, channel strategies, and sample commercial KPIs for 90/180/360‑day rollouts.
-
CapEx decision framework and ROI calculator that incorporates raw‑material volatility and regulatory compliance costs—designed to stress‑test plant expansion and retrofit choices.
-
A prioritized M&A and partnership shortlist built on complementary capabilities (formulation IP, regional access, sustainability credentials) plus modelled integration scenarios and expected synergies.
To preserve commercial value for subscribers while demonstrating domain depth, this briefing intentionally highlights strategic levers and market geometry. The report contains the full segmented datasets, regional and application breakdowns, price curve histories, and downloadable spreadsheets required to execute the above recommendations; these granular elements are available via the report landing page.
Final takeaways for the 2026 planning cycle
Water‑based acrylic emulsions are transitioning from a compliance solution to a strategic growth platform. For growth‑oriented executives, 2026 is the year to convert regulatory and sustainability pressures into durable competitive advantage by combining portfolio upgrade, feedstock risk management, and selective regional investments. The market’s mid‑single digit CAGR masks pockets of accelerated opportunity for companies that align product innovation, regional supply, and commercial execution within the next 12 months.
PW Consulting’s full Water‑Based Acrylic Emulsion Market report provides the detailed inputs, scenario tools, and deal frameworks that procurement, R&D, and corporate development teams require to act decisively in 2026. Access the complete dataset and implementation playbooks on our website to move from strategy to execution with confidence.
For detailed analysis of this topic, please visit the official page: Water Based Acrylic Emulsion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com