

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Composite Enclosures Market to Climb from USD 166.7 Million in 2025 to USD 269.8 Million by 2032 at a 7.12% CAGR

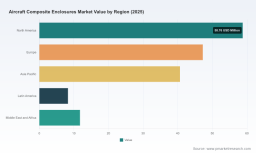
Aircraft Composite Enclosures Market — Strategic Outlook for 2026 Decision-Making
As airlines accelerate fleet renewal, avionics complexity increases, and defense platforms demand lighter, more resilient electronic housings, composite enclosures for aircraft electronics have moved from niche engineering choice to boardroom-level strategic variable. PW Consulting’s latest Aircraft Composite Enclosures Market report (base year 2025) synthesizes five years of historical trajectory and a seven‑year forecast to 2032, equipping executives with the market intelligence they need to make investment, sourcing, and partnership decisions in 2026. The market grew from under USD 100 million in 2020 to USD 166.7 million in 2025 and is projected to continue expanding to approximately USD 269.8 million by 2032 at a 7.12% CAGR (forecast period 2026–2032).
Aircraft Composite Enclosures Market
Why this market matters in 2026
-
Weight, EMI management, and environmental resilience are primary drivers. Composite enclosures deliver meaningful lifecycle advantages versus metal alternatives — not only in weight savings but in integration flexibility, corrosion resistance, and tailored RF/EMI properties.
Aircraft Composite Enclosures Market -
Supply-chain dynamics and raw-material volatility are elevating procurement risk to a strategic concern. Recent movements in epoxy resin and carbon-fiber markets are materially changing cost baselines for both OEMs and tier suppliers.
Aircraft Composite Enclosures Market -
Regulatory guidance and qualification requirements for composite avionics housings are converging with material capability, which shortens the window between prototyping and certification-ready production for firms that align engineering and compliance early.
Macro picture: growth, concentration and what it implies
PWC’s analysis shows a robust growth trajectory underpinned by aircraft modernization and electrification trends. The compound annual growth rate of 7.12% through 2032 is consistent with steady replacement cycles in commercial fleets, rising integration of electronics in cabins and cockpits, and increasing defense procurement of lighter, ruggedized systems.
Market concentration is moderate: leading suppliers hold a meaningful share but there remains room for differentiation through specialized materials, design-for-certification expertise, and integrated system solutions. This market structure creates distinct strategic pathways—scale-driven cost leadership for major suppliers, and high-margin technical niche plays for focused specialists.
What has changed since 2025 — near-term dynamics you must model now
-
Raw-material price shocks: Epoxy resin pricing in North America moved meaningfully upward in early 2026, with public reports showing a sharp quarterly rise driven by broader composite demand. Aerospace-grade carbon fiber price ranges also remain wide, underscoring the importance of supplier agreements that stabilize input costs.
-
Supply resilience via long-term agreements: Key industry actors are locking multi-year carbon-fiber contracts to protect program economics and delivery certainty. These agreements materially reduce lead-time and price volatility risk for companies that negotiate them early.
-
Regulatory clarity: Advisory circulars addressing composite structures and allowables have lowered technical ambiguity around qualification paths — a crucial enabler for turning engineered prototypes into certified avionics enclosures.
-
Strategic wins and partnerships: Recent commercial contracts and supply partnerships indicate accelerated adoption across naval and aerospace applications, validating crossover opportunities between marine gas-turbine housings and aircraft enclosure technology.
Actionable implications for 2026 corporate planning
For boards and executive teams, the 2026 planning horizon requires concrete moves in four areas:
-
Procurement and hedging: Revisit supplier mix and secure long-term raw-material agreements where cost exposure materially affects program margins. Scenario-run inputs for epoxy and carbon-fiber costs in CapEx/Opex models; sensitivity to +/- 10–20% swings changes IRR timelines on new programs.
-
Design-to-certification integration: Accelerate concurrent engineering between material scientists, structural analysts, and certification leads. The earlier FAA advisory guidance is baked into the design cycle, the lower the rework risk and time-to-market.
-
Portfolio and capability strategy: Decide whether to compete on vertically integrated solutions (materials + enclosure + systems integration) or to pursue high-value niche platforms that emphasize EMI shielding, thermal management, or high-voltage isolation. Each pathway requires different R&D and capital allocation profiles.
-
M&A and partnership focus: Given the market’s moderate concentration, targeted acquisitions—particularly of firms with validated certification packages or proprietary EMI-coating processes—can be the fastest route to differentiated capability without a multi-year internal build.
What PW Consulting’s report delivers (practical, implementable intelligence)
We designed the report as a decision-support tool for corporate leaders, procurement chiefs, and product heads. Key deliverables include:
-
Market sizing and rolling forecasts up to 2032 with scenario variations that stress-test pricing, supply disruption, and demand shocks.
-
Supplier risk matrix and a procurement playbook that translates raw-material price trajectories into contractual clauses, inventory strategies, and hedging actions.
-
Certification alignment checklist tied to FAA advisory guidance and military qualification expectations—actionable steps to reduce certification schedule risk.
-
Unit-cost build-ups and margin waterfall models for alternative material choices and manufacturing routes (autoclave cure vs. out-of-autoclave, molded vs. machined hybrid approaches).
-
Commercial go-to-market strategies for OEMs and tier suppliers, including pricing architecture, warranty exposure modeling, and service/repair economics for installed fleets.
-
M&A screening framework: scored targets based on IP strength, current certifications, customer stickiness, and geographic manufacturing risk.
Competitive landscape: who to watch and why
The competitive set includes global engineering-driven players, aerospace systems integrators, and specialty composite fabricators. A non-exhaustive strategic read on selected market participants:
-
TE Connectivity — A solutions-oriented supplier with a strong portfolio in lightweight composite enclosures and EMI shielding. Their strength is cross-domain expertise in connectors and housings, which enables integrated subsystem offers attractive to avionics OEMs focused on systems-level simplification.
-
Collins Aerospace — With deep program-level relationships across commercial and defense OEMs, Collins leverages systems engineering to embed composite enclosure solutions into larger avionics and thermal-management platforms. Their trajectory favors scale and certification muscle.
-
Carlisle Interconnect Technologies (Amphenol CIT) — Specializes in high-voltage and high-performance interconnect and enclosure applications. Their positioning is strong where enclosure design must meet demanding electrical isolation and form-factor constraints.
-
GE Aerospace — Recent contract awards in naval turbine enclosures highlight the cross-pollination of enclosure technology between maritime and aerospace platforms. Their program wins demonstrate how validated composite housings can be scaled across domains.
-
Automated Dynamics (Trelleborg) and RAMPF Group — Represent the high‑precision, custom-fabrication end of the market. These suppliers win work where EMI shielding, unique geometries, and small-batch qualification matter most.
-
AIM Aerospace and Kaman Aerospace (Vermont Composites) — Strong in structural and interior composite components; these firms can expand into enclosures where certification and production footprint are already in place.
Collectively, the market demonstrates both scale advantages for integrated suppliers and lucrative niches for materially differentiated players. Our concentration metric shows top players capture a meaningful share of the market, but not so much that a new entrant with the right certification and supply agreements couldn’t carve out a defensible position.
Risks, mitigations, and early warning signals
-
Raw-material inflation and allocation: Watch epoxy and carbon-fiber contract renewals closely. Early procurement commitments and secondary-sourcing agreements are effective mitigants.
-
Qualification delays: Track compliance milestones tied to advisory circulars and OEM validation timelines. Use staged qualification gates to limit sunk cost exposure.
-
Geopolitical and trade exposure: Diversify supply footprints and consider onshoring critical processes where program timelines or defense sensitivity require it.
-
Technology obsolescence: Monitor advances in conductive coatings, additive manufacturing for integrated enclosures, and hybrid metal-composite approaches that may disrupt traditional supply models.
How to use this intelligence in your 2026 planning cycle
-
For CEOs and CFOs — Run scenario models that include at least one high raw-material inflation case and one supply-disruption case; stress-test ROIs on new programs accordingly.
-
For CTOs and Chief Engineers — Prioritize design-for-certification and build a two-year prototype-to-qualification roadmap that maps to procurement milestones.
-
For Procurement and Strategy teams — Initiate or accelerate long-term supply agreements for carbon fiber and resins; demand contractual price-stability mechanisms and capacity reservations linked to program forecasts.
-
For M&A teams — Use our screening framework to identify targets that offer immediate certification benefits or proprietary EMI/thermal technologies that shorten time-to-revenue.
Concluding perspective: selective acceleration, not blanket investment
Composite enclosures are a high-conviction, mid-term growth opportunity for firms positioned to manage material costs and certification pathways. The market’s projected expansion through 2032 validates selective acceleration — executives should prioritize moves that de-risk supply and certification while preserving strategic optionality for future material and manufacturing innovations.
PW Consulting’s Aircraft Composite Enclosures Market report provides the practical models, supplier risk analytics, and playbooks needed to operationalize these conclusions in 2026. We intentionally present the high-level indicators and strategic implications above; the report contains detailed scenario spreadsheets, supplier scorecards, and the granular segmentation analyses that underpin these recommendations. Access to that intelligence will materially shorten your path from strategy to execution.
Next steps
-
Request the full report to obtain the detailed segmentation matrices, supplier scorecards, and executable procurement templates that are intentionally not reproduced here.
-
Contact PW Consulting to commission a tailored workshop: two days to translate report outputs into a prioritized 18‑month implementation plan specific to your fleet, supplier base, and certification roadmap.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com