

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fully Automatic Full‑Screen Laser Cutting Equipment Market to Grow at 7.46% CAGR, Expanding from USD 748.5 Million in 2025

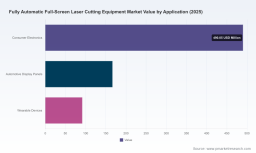
Fully Automatic Full Screen Laser Cutting Equipment Market: Strategic Outlook for 2026 Decisions
PW Consulting today releases a strategic preview of our forthcoming market research report on the Fully Automatic Full Screen Laser Cutting Equipment market. Grounded in a detailed historical review (2020–2025) and a rigorous forecast (2026–2032), this analysis is designed to equip executive teams with the foresight needed to make high-conviction decisions in 2026. The global market, measured in USD Million, recorded a base-year size of 748.5 (2025) and is projected to grow at a compounded annual growth rate (CAGR) of 7.46% across our forecast window — reaching a modeled market size of approximately 1,238.4 by 2032.
Fully Automatic Full Screen Laser Cutting Equipment Market
Why this market matters to CEOs and strategy teams in 2026
-
Transition point for industrial automation: Manufacturers across consumer electronics, displays, and precision components are accelerating investments in fully automatic full-screen laser systems to compress cycle times and improve yield.
Fully Automatic Full Screen Laser Cutting Equipment Market -
Technology-led differentiation: Advances in ultrafast and solid-state laser sources, combined with machine-level and plant-level automation, are redefining cost-to-serve and enabling new product form factors.
Fully Automatic Full Screen Laser Cutting Equipment Market -
Capital planning implications: With the market expanding from a 2025 base of USD 748.5 Million toward our 2032 projection, procurement, CAPEX timing, and financing strategies must account for a multi-year productivity and obsolescence curve.
What the report delivers — operational, actionable intelligence (high level)
-
Robust market sizing and scenario-based forecasting methodology that reconciles bottom-up equipment shipments with top-down macro drivers — presented with transparent assumptions suitable for CFO-level stress-testing.
-
Practical segmentation frameworks (by region, laser source, and application) and an operational taxonomy that aligns purchasing decision trees with production use-cases and lifetime cost of ownership (LCO).
-
Competitor benchmarking and capability maps that highlight not only market share positions but also technology stacks, automation footprints, and aftermarket service models.
-
Supply-chain risk heatmaps and mitigations — including sensitivity to raw material price volatility and component lead-time shocks — enabling procurement and operations teams to prioritize dual-sourcing and inventory strategies.
-
Go-to-market playbooks for OEMs, system integrators, and end-users: procurement timing, service bundling, retrofit pathways, and scenario-triggered investment thresholds.
-
M&A and partnership screening criteria emphasizing strategic fits based on automation IP, regional service coverage, and installed-base conversion potential.
Market dynamics that will shape 2026 strategies
-
Automation adoption and productivity demands: The industry-wide shift to higher automation is accelerating demand for fully automatic full-screen systems. For manufacturers focused on throughput and consistency, this creates a stronger economic case for replacement cycles and higher-capacity purchases.
-
Energy efficiency and regulation: Regulatory pressure and internal sustainability targets are pushing buyers toward energy-efficient fiber and solid-state laser sources. Expect procurement teams to require energy-performance metrics and lifecycle emissions profiles as part of tender evaluations.
-
Raw material and component cost variability: Fluctuations in steel, aluminum, and specialty optical components influence total cost of ownership and capital budgeting. The report provides sensitivity analyses that link raw material price scenarios to payback periods and lease-versus-buy decisions.
-
Concentration and competition: The market exhibits moderate-to-high concentration at the top. Our modeling indicates that the three largest suppliers hold a meaningful portion of available commercial demand, while the top five together represent a larger share. This structure has implications for pricing dynamics, service competition, and consolidation opportunities.
Competitive landscape — implications for 2026 positioning
Leading manufacturers and system integrators vary by technological emphasis, geographic reach, and aftermarket strategies. Below we synthesize strategic takeaways for each archetype represented by core industry players.
-
High-power fiber specialists (e.g., Farley Laserlab / HGTECH affiliate) : These firms excel in large-format, high-throughput systems and tend to win in industrial, sheet- and tube-processing environments. Their competitive edge is scale and integrated automation; however, buyers should probe service network density in their target markets and the supplier’s roadmap for energy-efficiency improvements.
-
Full-range Chinese OEMs (e.g., Han’s Yueming, Kunshan Dapeng, Beijing Torch SMT) : These suppliers offer breadth and price competitiveness across multiple applications. They are strong contenders for volume-driven programs, but strategic buyers will want to validate quality-management processes, IP ownership, and long-term support commitments.
-
Established global industrial brands (e.g., Mitsubishi Electric) : With deep R&D and reliable global service footprints, these players are preferred where precision, integration with existing MES/PLM systems, and total-cost-of-ownership predictability are priorities. Their offerings often command premium pricing aligned with lower operational risk.
-
Specialized precision system providers (e.g., Control Micro Systems, EBSO GmbH) : These companies are attractive for niche high-precision and research-intensive applications, with robust customization capabilities. They can be preferred partners for pilot projects and co-development but may require longer integration timelines.
-
Automation-first suppliers (e.g., Aurotek, ASYS GROUP) : These players integrate laser systems with upstream/downstream automation and provide compelling value for smart-factory deployments. For manufacturers pursuing Industry 4.0 trajectories, their bundled solutions can shorten implementation cycles.
Strategic recommendations for 2026 decision-makers
-
Adopt a hybrid procurement posture: Combine immediate investments in standardized high-uptime platforms with modular pilot investments in ultrafast and niche solid-state systems. This balances near-term productivity gains with optionality for emerging production requirements.
-
Prioritize aftermarket economics: Given the importance of installed-base uptime, structure supplier contracts to include performance SLAs, local spares staging, and predictive maintenance agreements. This often delivers greater ROI than marginal equipment price concessions.
-
Stress-test supply-chain exposure: Use the report’s scenario tools to model capital projects under raw material and component availability shocks. Where exposure is high, consider pre-purchasing critical subsystems or negotiating inventory-risk sharing with key suppliers.
-
Design integration-first RFPs: Ensure procurement specifications require open integration points with MES/ERP systems, energy-performance guarantees, and upgrade pathways to protect against rapid obsolescence.
-
Engage in selective partnerships: For OEMs and system integrators, prioritize partnerships that expand geographic service reach and digital maintenance capabilities rather than purely transactional supply agreements.
-
Use concentration information tactically: The market’s top-tier concentration creates both risks and opportunities — incumbent suppliers may be less price-sensitive but can be weaker at rapid customization; challenger suppliers provide agility but may lack scale. Balance vendor portfolios appropriately.
Scenario planning and investment timing
Our forecasting framework presents multiple adoption scenarios tied to macroeconomic growth, capital-availability, and the pace of automation uptake. Across scenarios, the baseline case — driven by continued automation investment and incremental efficiency mandates — supports a steady upward trajectory consistent with the stated CAGR of 7.46% from the 2025 base. For 2026 planning, the key variables to monitor are interest-rate movements affecting CAPEX financing, raw material price volatility, and the speed of regulatory shifts toward energy-efficiency standards.
How to use this preview — next steps for executive teams
-
Procurement leads: Use the report’s LCO templates and service-cost breakdowns to re-run your 3–5 year refresh plan and adjust timing to capture efficiency improvements with acceptable payback horizons.
-
R&D and product strategy teams: Map your roadmap against supplier technology stacks and identify where partnerships or acquisitions would create defensible differentiation in automation, optics, or software control systems.
-
Corporate development teams: Leverage the competitor benchmarking and concentration analysis to prioritize M&A targets and JV partners that expand installed-base service capabilities or accelerate entry into high-growth application segments.
Closing — access to the full intelligence
This briefing highlights the strategic lens PW Consulting applies to the Fully Automatic Full Screen Laser Cutting Equipment market: rigorous quantitative forecasting, deep operational analysis, and decision-ready recommendations. We intentionally present high-level findings here to demonstrate analytical rigor while preserving the detailed segment-level breakdowns, supplier scorecards, and proprietary scenario models for full-report subscribers. For companies preparing capital allocation, procurement cycles, or partnership strategies in 2026, the complete report contains the granular inputs and downloadable tools required to operationalize these insights.
To obtain the full report and unlock the detailed datasets, segmentation tables, and vendor scorecards referenced in this preview, please visit our official report page or contact PW Consulting’s industry practice team for a briefing tailored to your organization’s needs.
For detailed analysis of this topic, please visit the official page: Fully Automatic Full Screen Laser Cutting Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com