

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Household Solid‑State Relay Market to Grow at a 7.66% CAGR, Reaching USD 721.25 Million by 2032

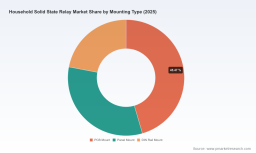
Household Solid State Relay Market 2026: Strategic Playbook for Executives — PW Consulting Release
Executive summary
PW Consulting today publishes its definitive industry outlook, Household Solid State Relay Market: Strategic Opportunities and Risks, providing senior executives, product leaders, and procurement teams with the market intelligence required to make high‑stakes decisions in 2026. Our analysis shows the household solid state relay (SSR) market has expanded rapidly over the past half‑decade — rising from approximately USD 305 million in 2020 to an estimated USD 430 million in our 2025 base year — and is projected to sustain healthy momentum through the 2026–2032 forecast window. We model a compound annual growth rate (CAGR) of 7.66% for 2026–2032, taking the market toward roughly USD 721 million by 2032 under our baseline scenario.
Household Solid State Relay Market
Why this matters for 2026 decision‑making
- Timing and scale: The market is no longer nascent — established suppliers and new entrants are competing across a widening set of household use cases. 2026 will be a pivotal year for locking in supplier relationships that will influence cost, reliability, and product feature roadmaps through the next product cycle.
- Supply chain concentration risk: Macro policy and raw material dynamics have elevated the strategic importance of supplier selection, qualification timelines, and inventory strategy. Executives who defer supply‑chain resilience efforts in 2026 risk production delays or cost escalation.
- Product differentiation: Silent operation, thermal management, and integration into home energy management systems are migrating from “nice‑to‑have” to procurement gatekeepers for appliance OEMs. Choosing the wrong SSR architecture or failing to validate lifecycle endurance can increase warranty exposure and brand risk.
What the PW Consulting report delivers — practical, transaction‑grade intelligence
This research is built for corporate action. We translate market dynamics into tools and frameworks that teams can deploy immediately:
Household Solid State Relay Market
- Scenario planning models that quantify the P&L impact of supply disruptions, tariff shocks, or component‑level material shortages across low‑, medium‑, and high‑adoption trajectories.
- Supplier heatmaps and qualification scorecards that speed vendor selection while scoring on reliability, technical fit, cost competitiveness, and geopolitical exposure.
- Technology readiness and substitution matrix to evaluate optocoupler, MOSFET, and other SSR architectures against household application requirements (noise, inrush handling, thermal footprint, and lifecycle).
- Regulatory and trade risk tracker tailored to SSR value chains — enabling procurement and government affairs teams to prioritize mitigation actions.
- Commercial playbooks (procurement negotiation templates, multi‑year hedging strategies, and inventory buffers calibrated to lead‑time volatility).
- A roadmap for product engineering teams including thermal test profiles, validation checklists, and recommended instrumentation for accelerated SSR qualification.
Competitive landscape — established players and strategic implications
The household SSR market is moderately concentrated. Our concentration analysis indicates leading vendors collectively hold meaningful share while leaving room for mid‑market specialists and component innovators to win niches. Key industry participants profiled in the report and their strategic positions are summarized below — each entry spotlights go‑to‑market implications for OEMs and suppliers evaluating partnerships in 2026.
Household Solid State Relay Market
- Omron Corporation (Kyoto, Japan): Offers compact PCB‑mount and panel‑mount SSRs suitable for temperature control and lighting. Omron’s depth in control electronics and brand recognition makes it a primary candidate for appliance makers seeking proven product lifecycle support and extensive global distribution.
- Panasonic Corporation (Osaka, Japan): Known for PhotoMOS and low‑power SSR variants optimized for consumer electronics. Panasonic’s strength is in miniaturized, low‑noise switching — attractive for premium appliance lines and integrated consumer devices.
- Carlo Gavazzi Holding AG (Steinhausen, Switzerland): Focuses on DIN‑rail and panel solutions targeting building automation and HVAC. Their mechanical form‑factor expertise and integrated thermal management suit OEMs that prioritize installation simplicity in retrofit and smart‑building contexts.
- Sensata Technologies (Crydom) (Attleboro, USA): Supplies industrial‑grade SSRs adaptable for high‑reliability household applications, including zero‑cross switching for noise‑sensitive environments. Sensata is a strategic partner for high‑end appliance lines where resilience and electrical performance are differentiators.
- Schneider Electric SE (Rueil‑Malmaison, France): Positions SSRs within modular home and building automation portfolios, offering systems integration benefits for customers pursuing energy‑management propositions.
- Siemens AG (Munich, Germany): Delivers SIRIUS series SSR/contactors for residential and light commercial HVAC applications, leveraging its strong channel and systems integration capabilities.
- ABB Ltd (Zurich, Switzerland): Integrates SSRs into power distribution solutions and energy management systems for the home, offering scale advantages to appliance OEMs seeking bundled energy‑management propositions.
- TE Connectivity (Schaffhausen, Switzerland): Provides vibration‑resistant SSRs for high‑cycle applications — suited to appliances with demanding mechanical environments.
- Vishay Intertechnology (Malvern, USA): Supplies optocoupler‑based and MOSFET SSRs for low‑power switching, attractive for compact consumer electronics and cost‑sensitive appliance segments.
- Littelfuse, Inc. (Chicago, USA): Offers high‑endurance SSR series for HVAC and appliance control, favoring customers emphasizing lifecycle durability.
- Celduc Relais (Sorbiers, France): Specializes in heating, lighting, and motor control SSRs for household and building automation — a contender for OEMs seeking tailored thermal control solutions.
- Fujitsu Limited (Tokyo, Japan): Targets compact SSRs for consumer electronics and home appliance circuits, aligning with manufacturers of space‑constrained products.
Recent industry developments that should influence 2026 planning
- Trade show activity in early 2026 saw vendors highlight semiconductor‑driven SSR innovations with increasing emphasis on thermal performance and integration — signaling ongoing product maturation and the emergence of differentiated features that will matter in procurement cycles.
- Product refreshes in 2024–2025 from select vendors focused on thermal performance improvements and electrical isolation, underscoring a supplier push to reduce field failures and improve installation flexibility.
- Regulatory and materials shocks — notably policy actions on critical semiconductor inputs and tariff adjustments — are already affecting component costlines and supplier risk profiles.
Industry context and risk factors
Two structural themes dominate the near‑term risk landscape:
- Raw material concentration: Production of certain gallium grades, a feedstock used in optoelectronic and power semiconductor components relevant to SSRs, is highly concentrated geographically. This creates asymmetric supply risk when export controls or licensing regimes tighten.
- Trade and policy volatility: Recent tariff escalations and executive actions targeting processed critical minerals and derivative products have materially increased the probability and potential impact of import restrictions. These dynamics can raise component costs, extend lead times, and force requalification of alternative parts.
For 2026, risk mitigation should be treated as a business‑critical investment, not a cost center: prioritizing alternative sourcing, creating qualified second‑source lists, and accelerating component requalification programs can materially reduce downside exposure.
Actionable strategies for market leaders and challengers in 2026
- Procurement playbook: Implement a two‑tier sourcing strategy combining long‑term strategic suppliers for core components and smaller, agile partners for capacity buffering; couple this with indexed short‑term contracts to hedge tariff volatility.
- Engineering and product strategy: Reassess SSR architecture choices against supply risk and lifecycle cost, and fast‑track design validation labs to compress qualification timelines to under 6 months where possible.
- Manufacturing and localization: Evaluate near‑shoring and assembly localization options to mitigate cross‑border logistics and tariff exposure; run cost‑benefit pilots that incorporate nonrecurring engineering and certification costs.
- Partnerships and M&A: Consider targeted partnerships or minority investments in component specialists to secure preferred access to critical technologies and inputs without full vertical integration.
- Regulatory and public affairs: Develop an evidence‑based advocacy posture and multi‑stakeholder strategy to influence import policy and critical minerals negotiations where national security dialogues intersect with commercial supply chains.
Methodology and data integrity
Our findings combine bottom‑up revenue modeling, primary vendor interviews, trade flow analysis, and a proprietary component‑level cost model. Historical series cover 2020–2025 with a 2025 base year; forward projections are presented across multiple scenarios to reflect demand elasticity, technology substitution, and potential policy shocks. Market concentration metrics and company profiles are based on observable shipment and revenue indicators supplemented by vendor disclosures and industry trade data.
Next steps — how to use this intelligence
PW Consulting’s Household Solid State Relay Market report is written for executives who must translate uncertainty into action in 2026. Use the report to:
- Inform supplier qualification and CAPEX decisions for the next generation of household appliances.
- Prioritize R&D and product roadmaps based on quantified market growth and risk scenarios.
- Construct a defensible procurement strategy that balances cost, resilience, and time‑to‑market.
Accessing the full intelligence
This publication is a strategic preview. To preserve the tactical advantage for subscribers, detailed regional and application segmentation, proprietary vendor scorecards, and the full financial tables are reserved for the complete report. To obtain the full dataset, interactive models, and the procurement playbook, please visit PW Consulting’s report page at pwconsulting.com/reports/household-solid-state-relay-market or contact our client services team for an executive briefing.
About PW Consulting
PW Consulting is a strategic advisory firm specializing in industrial electronics and supply‑chain resilience. We provide executive teams with decision‑ready research, scenario analyses, and implementation toolkits that bridge market foresight and operational execution.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com