

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts ORC Waste Heat-to-Power Market to Accelerate at 10.65% CAGR, Transforming Industrial Energy Recovery Through 2032

Organic Rankine Cycle Waste Heat to Power: Strategic Imperatives for 2026 — PW Consulting Market Brief
As energy-intensive industries confront volatile fuel markets, tightening emissions rules, and an urgent decarbonization timetable, Organic Rankine Cycle (ORC) waste heat to power (WHtP) systems have moved from niche pilots to deployable industrial solutions. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — quantifies this transition and, more importantly, translates it into concrete decision‑making guidance for corporate strategists, project developers, and investors preparing plans in 2026.
Organic Rankine Cycle Waste Heat To Power Market
Market snapshot: scale, trajectory, and what it means for corporate planning
The ORC WHtP market has entered a phase of sustained expansion. Our analysis shows the market reached an estimated USD 4.8 billion (base year 2025) and is projected to grow at a compound annual growth rate (CAGR) of 10.65% through 2032, reaching close to USD 9.75 billion by the end of the forecast period. This trajectory reflects accelerating unit deployments, broader temperature-range applicability, and improved project economics driven by higher energy prices and policy incentives.
Organic Rankine Cycle Waste Heat To Power Market
For executives evaluating capital allocation in 2026, three implications flow directly from this macro trend:
Organic Rankine Cycle Waste Heat To Power Market
- Scale economies are emerging but the market remains far from consolidated — leading vendors account for a minority share of global activity. Our concentration metrics confirm a market where the top three and five vendors do not dominate, leaving ample room for new entrants, partnerships, and localized supply strategies.
- Total addressable opportunity is large enough to justify internal capability development (technical, commercial, and O&M) for industrial groups with continuous waste heat streams, but site selection and contract structures will determine which projects are attractive in 2026 vs. later years.
- Policy and fluid‑technology risks are now a core part of project underwriting. Regulatory moves to restrict certain HFC/PFAS working fluids and stronger industrial‑efficiency mandates create both upside (incentives, accelerated permitting) and transition costs (retooling, repowering).
What this PW Consulting report delivers — operational, actionable intelligence
The public summary will not replace direct engagement with the study, but the core of our offering is practical, decision‑grade content designed for use in 2026 bidbooks, CAPEX committees, and M&A diligences. Key deliverables include:
- Market forecast model (2026–2032) with scenario layers: baseline, high‑adoption, and policy‑stressed outcomes — delivered as a downloadable, editable workbook so corporate planners can run their own sensitivity analyses against electricity price, operating hours, and capital cost assumptions.
- An investment playbook and project screening toolkit that operationalizes payback thresholds, financing levers, and commercially realistic dispatch strategies for baseload vs. complementary power generation.
- Vendor benchmarking and procurement templates: capability maps, scopes of supply, and negotiation checklists tailored to ORC procurements across typical industrial EPC cycles.
- Technical deep dives into ORC sub‑systems — expander/turbine types, heat‑exchanger architectures, working‑fluid tradeoffs, and modularization — with practical guidance on lifecycle O&M and repower pathways.
- Regulatory and supply‑chain risk mapping, including scenario planning for fluid restrictions and critical‑component lead times, plus mitigation strategies (fluid transition roadmaps, dual‑supplier sourcing).
- Case studies and validated ROI models built from real industrial deployments — enabling capital committees to translate vendor quotes into board‑grade financials (IRR, NPV, simple payback under multiple tariffs and operating regimes).
Competitive landscape: who matters and how to position in 2026
The ORC vendor field is populated by a mix of pure‑plays, industrial incumbents, and specialist component suppliers. Our report profiles the leading names that are shaping industrial deployment strategies and competitive dynamics.
- Ormat Technologies Inc. (Reno, Nevada, USA; https://www.ormat.com) — a recognized leader in recovered energy generation systems. Ormat’s proprietary energy converters and integrated project capabilities make it a natural choice for customers seeking an end‑to‑end partner with track record in industrial REG applications. For buyers, Ormat represents lower integration risk but typically commands a premium for its packaged offering.
- Turboden S.p.A. (Mitsubishi Heavy Industries Group — Brescia, Italy; https://www.turboden.com) — strong in large‑scale turbogenerators and energy‑intensive sectors. Recent high‑visibility projects — including North America’s first large WHtP plant at a SAGD facility and new awards for compressor‑station deployments — highlight Turboden’s ability to scale in both heavy‑industry and oil & gas upstream contexts. Partnerships with major industrials and EPCs are a differentiator.
- Exergy International Srl (Olgiate Olona, Italy; https://www.exergy-orc.com) — noted for its Radial Outflow Turbine (ROT) technology and mid‑size units. Exergy is frequently selected where turbine efficiency and compact footprint are decisive; its solutions appeal to cement and chemical plants seeking attractive payback profiles.
- ElectraTherm Inc. (BITZER Group — Flowery Branch, Georgia, USA; https://electratherm.com) and ENOGIA SAS (Marseille, France; https://enogia.com) — both specialists in low‑temperature and micro‑ORC segments. Their modular offerings enable projects on lower‑grade heat streams that previously were uneconomic, unlocking a new tranche of small‑scale deployments.
- Orcan Energy AG (Munich, Germany; https://www.orcan-energy.com), Calnetix Technologies LLC (Cerritos, California, USA; https://www.calnetix.com), and large heat‑transfer suppliers like Alfa Laval AB (Lund, Sweden; https://www.alfalaval.com) — these players are central to system modularization, heat‑exchanger optimization, and advanced rotating‑machinery solutions. Their roles are increasingly important in integrated supply models and aftermarket service agreements.
In short, procurement strategies in 2026 should acknowledge that vendors vary not only by technology but by commercial posture: turnkey integrators, OEMs selling to EPCs, and component specialists. Our vendor scorecards in the report map these vectors against risk tolerances and CAPEX/late‑stage O&M preferences.
Technology, policy, and operational risks that will shape 2026 execution
Three risk vectors must be actively managed in project development and portfolio prioritization:
- Working‑fluid and chemical‑regulation risk. Regulatory movements in Europe and elsewhere around HFCs/PFAS can force mid‑lifecycle fluid changes, with capex and downtime implications. The report provides a transition playbook and supplier readiness matrix so project teams can pre‑emptively select fluids and hardware architectures that minimize stranded‑asset risks.
- Project economics sensitivity to operating hours and electricity tariffs. Industrial payback periods for many cement and steel applications typically cluster in the multi‑year band — our benchmarking and sensitivity tools let CFOs test tariff shocks and curtailment risk to prioritize sites with the highest risk‑adjusted returns.
- Supply chain and installation complexity. Larger ORC units and multi‑MW installations carry longer lead times and require advanced integration planning; conversely, micro‑ORC and modular packs present fast‑track opportunities. Our schedule impact templates quantify expected EPC timelines and typical schedule variance by capacity band.
Actionable 2026 playbook: five recommended moves for corporate decision‑makers
- Undertake a one‑year “heat asset audit” across manufacturing and process sites to quantify continuous vs. intermittent waste heat and prioritize sites by hours‑of‑operation, steam/economizer temperatures, and grid tariff exposure. Use the PW Consulting screening template to produce board‑grade site shortlists.
- Pursue staged procurements: pilot modular systems at 1–5 MW equivalent sites to validate operating assumptions, then scale up via framework agreements with primary vendors to capture learning‑curve cost reductions.
- Embed fluid‑transition clauses into procurement and service contracts to limit exposure from potential regulatory changes. The report provides contract language examples and vendor negotiation points for 2026 RFPs.
- Structure financing around performance guarantees and energy‑service models (ESCOs) where possible to accelerate adoption while protecting balance sheets. The financial annex includes example deal structures and indicative debt sizing approaches used in 2025‑2026 transactions.
- Design an aftermarket and repower roadmap at the outset—covering monitoring, predictive maintenance, and future fluid replacement—to preserve project value over two decades of operation.
Why PW Consulting’s study is strategically different
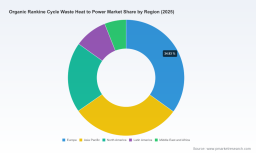
Beyond headline forecasts and vendor lists, PW Consulting’s ORC WHtP study is built for application: editable financial models, procurement playbooks, vendor scorecards, and legally minded procurement language. Its focus is on enabling 2026 decisions — not just measuring market size. To maintain the integrity of client engagement and commercial confidentiality, the public brief intentionally omits full regional and application split tables and certain granular unit economics; these are available in the complete report and accompanying datasets.
Next steps for executives
If your organization is evaluating WHtP options in 2026 — whether through CAPEX deployment, energy service agreements, or strategic partnerships with ORC vendors — PW Consulting’s full report provides the modeling, vendor insight, and contractual tools needed to move from concept to sanctioned project. The public summary above outlines the strategic landscape; the full deliverable contains the data‑rich annexes and executable tools required to de‑risk board decisions and accelerate deployment.
Contact PW Consulting to obtain access to the full ORC Waste Heat to Power Market report, the editable forecast model, and our procurement toolkits. For immediate priority guidance, our experienced industry advisors are available for short, targeted workshops to translate the study’s insights directly into your 2026 project pipeline and capital planning cycle.
For detailed analysis of this topic, please visit the official page: Organic Rankine Cycle Waste Heat To Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com