

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Intelligent Automatic Warehouse & Logistic Equipment Market Set to Expand at a Robust 12.04% CAGR During 2026–2032

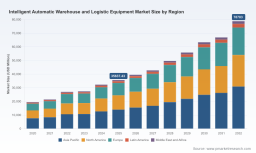
Intelligent Automatic Warehouse and Logistic Equipment: Strategic Imperatives for 2026 — PW Consulting Market Brief
As supply chains enter a new phase of digitization and capital-intensive modernization, executives must choose where and how to invest to capture productivity gains while managing cost, risk and regulatory exposure. PW Consulting’s latest market study on Intelligent Automatic Warehouse and Logistic Equipment synthesizes five years of historical performance and a seven-year forecast to 2032, delivering the operational intelligence leaders need to set 2026 strategy with confidence.
Intelligent Automatic Warehouse And Logistic Equipment Market
Market Trajectory — What the headline data tell us
The global intelligent automatic warehouse and logistics equipment market has roughly doubled in scale over the 2020–2025 period, reflecting accelerating adoption across fulfillment, manufacturing and omnichannel retail. Building on that momentum, our model projects continued high-growth through 2032 — a compound annual growth rate (CAGR) of 12.04% across the 2026–2032 forecast window, and a market poised to exceed USD 78 billion by the end of the decade.
Intelligent Automatic Warehouse And Logistic Equipment Market
For 2026 specifically, the market enters the year as a sizable and expanding opportunity: organizations that move early to validate automation concepts, shore up supplier relationships, and optimize total cost of ownership (TCO) will capture outsized gains in throughput, labor substitution and energy efficiency.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this report matters to 2026 decision-makers
- Decision timing is critical: with capital project lead times and supply-chain constraints, 2026 is the year to convert pilot learnings into scalable deployments. Our report identifies readiness indicators and decision gates that CFOs and COOs should use to prioritize capital allocation.
- Risk-adjusted procurement: rising raw material volatility and tariffs have increased project cost uncertainty. The report provides procurement playbooks and contract clauses to mitigate exposure to steel and aluminum price swings and trade policy actions.
- Technology vs. process choices: not every operation benefits from the same automation mix. We map capability tiers — from incremental conveyor and sortation upgrades to transformational robotics- and software-led redesigns — helping firms match solution archetypes to business goals and ROI horizons.
- Vendor selection under fragmentation: despite the market’s growth, concentration remains moderate — the top five providers account for roughly one-quarter of industry revenue. Buyers must therefore blend the stability of incumbents with the innovation of specialist entrants; our vendor framework scores suppliers across technical reach, integration capability, and commercial flexibility.
Practical, operationally-focused contents you’ll find in the report
- Executable deployment playbooks — step-by-step guides for pilot-to-scale transitions, including scope, KPI selection, and phasing strategies that minimize disruption to day-to-day operations.
- Commercial and financing models — TCO calculators, capex/opex optimization scenarios, and leasing vs. purchase decision matrices tailored to automation investments.
- Integration and software blueprints — recommended architectures for Warehouse Management Systems (WMS), Warehouse Execution Systems (WES), robotics orchestration, and APIs that de-risk multi-vendor rollouts.
- Supplier due diligence templates — scorecards, RFP templates and negotiation playbooks that expose hidden cost drivers and post-installation obligations.
- Workforce transition plans — reskilling roadmaps, change-management sequences, and productivity benchmarks to align labor strategy with automation adoption.
- Sustainability and compliance assessment — checklists and retrofit approaches to meet emerging energy-efficiency mandates and ESG reporting requirements without eroding economic returns.
- Scenario-driven forecasts — demand sensitivity analysis across macro and micro levers, enabling portfolio managers to stress-test investment cases under alternative economic and policy conditions.
Competitive landscape — who matters and why
The report analyzes the strategic positioning of established system integrators, robotics specialists and software-first players. It profiles market leaders and innovative challengers across capability axes — hardware breadth, software depth, global delivery footprint and integration speed — so procurement teams can align selection criteria to their operational tolerance for customization and time-to-value.
- System integrators and incumbents: Companies with long histories in material handling offer end-to-end solutions that reduce integration risk for large, high-throughput sites. Their scale advantages help in complex, multi-site rollouts and long-term maintenance contracts.
- Robotics and AMR specialists: Autonomous Mobile Robot (AMR) and AI-enabled robotics vendors bring flexibility and rapid redeployability, ideal for operations prioritizing agility and modular growth over lowest unit cost.
- Software-first entrants: Firms focused on orchestration and optimization software are shifting the value equation — enabling legacy equipment to perform smarter without a full rip-and-replace.
Recent industry activity underscores these trends: leading integrators and robotics vendors demonstrated new capabilities at trade exhibitions in early 2026, while thought leaders published fresh insights on multi-agent AI systems for warehouse orchestration. These developments point to an ecosystem moving towards tighter software-hardware co-design and faster innovation cycles.
Market dynamics shaping 2026 choices
- Cost inflation and tariffs: Steel and aluminum price increases, and specific tariff actions implemented in recent policy cycles, have raised up-front project costs. Procurement teams should demand transparent materials-cost escalators and consider hybrid procurement structures to hedge exposure.
- Labor pressure: Continued worker shortages and wage inflation in many logistics markets make automation an attractive substitute. Our ROI templates quantify labor displacement timelines and net productivity gains by operation type.
- Energy and ESG mandates: Regulatory pushes for energy-efficient operations favor solutions with regenerative drives, energy-aware scheduling and software-level optimization. The report offers retrofit pathways that reconcile sustainability targets with payback constraints.
- Supply-chain and lead-time risk: Component and lead-time variability requires contingency planning. We outline inventory, supplier diversification and phased-delivery strategies to keep project schedules intact.
Actionable 90–180 day roadmap for 2026
For executives who must make or influence automation investments in 2026, we provide a concise, prioritized sequence of actions that match capital planning cycles and procurement windows:
- 90-day actions: establish cross-functional governance, run a rapid site-readiness audit using our checklist, and issue a narrowly scoped RFP to validate vendor responsiveness and commercial terms.
- 90–180 day actions: complete one or two well-scoped pilot projects tied to measurable KPIs, lock favorable long-lead-time items under conditional purchase agreements, and finalize software integration contracts with clear SLAs.
- Beyond 180 days: scale deployments by phasing across sites with established playbooks, implement workforce reskilling programs, and transition from manual scheduling to dynamic, energy-aware orchestration.
What we intentionally withhold — and why
To preserve the commercial utility of the full study and to respect the confidentiality of detailed segmentation analyses, this brief intentionally omits granular regional and end-user shares, and detailed equipment-line revenue breakdowns. The full report contains detailed segment-level forecasts, vendor share matrices and downloadable financial models that buyers, investors and planners will find essential for procurement negotiations and board-level capital approvals.
Conclusion — the strategic value of informed timing
2026 represents a tipping point where automation can move from pilot projects to strategic capability. Companies that act with a risk-aware, data-driven playbook will realize faster payback, improved operational resilience and measurable sustainability benefits. PW Consulting’s Intelligent Automatic Warehouse and Logistic Equipment market study equips leaders with the frameworks, financial tools and supplier intelligence required to make those decisions — and to defend them to boards and investors.
Next steps
To access the full dataset, vendor scorecards, model templates and detailed segment forecasts needed to operationalize these insights, visit the official PW Consulting report page. The full deliverable includes executable artifacts designed for direct use in procurement, capital planning and operations meetings throughout 2026.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com