

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.79% CAGR for Commercial Small Batteries Market Through 2032

Commercial Small Batteries Market — Strategic Outlook for 2026: Practical Guidance for Executive Decision-Making
PW Consulting’s new Commercial Small Batteries Market report offers a forward-looking, execution-focused view designed to inform board-level choices, procurement strategies, product roadmaps, and M&A decisions in 2026. Built on a robust historical base (2020–2025) and a detailed forecast horizon (2026–2032), the study integrates market modeling, regulatory intelligence, and supplier benchmarking to convert market signals into operational moves.
Commercial Small Batteries Market
Executive summary: a concise market view you can act on
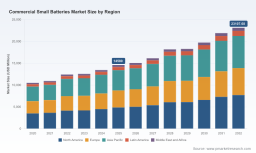
After steady expansion through 2020–2025, the commercial small batteries market recorded an estimated market size of approximately USD 14.58 billion in 2025. Our baseline forecast projects a compound annual growth rate (CAGR) of 6.79% over 2026–2032, bringing the market to roughly USD 23.11 billion by 2032 under central assumptions. Market concentration is moderate: the top three suppliers account for roughly 43% of the market, while the top five capture just under 59%—a structure that supports both incumbent margin preservation and discrete opportunities for challengers with focused value propositions.
Commercial Small Batteries Market
This release highlights the strategic implications embedded in those headline numbers—without disclosing the full, segment-level dataset. PW Consulting follows a “trailer” approach: we present the analytical framework and actionable recommendations here and invite decision-makers to access the complete model and granular splits through the full report.
Commercial Small Batteries Market
Why this work matters for 2026 decisions
- Procurement and cost planning: price volatility in key raw materials directly affects sourcing strategies, contract tenors, and hedging behavior.
- Product and R&D roadmaps: safety and regulatory trends are reshaping product specifications for coin, button, and small-format batteries used in medical and IoT devices.
- M&A and partnership screening: concentration metrics point to consolidation potential—especially for firms seeking rapid access to specialized chemistries or footprint expansion.
- Go-to-market differentiation: channel mixes and commercial service propositions (warranty, extended producer responsibility compliance) will determine near-term share shifts.
Key dynamics shaping 2026
- Raw material volatility: Lithium carbonate prices rebounded sharply in 2025 (moving from about ¥59,000/ton mid-year to over ¥130,000/ton by year-end), and industry consensus expects 2026 trading in a broad ¥80,000–150,000/ton range. That volatility magnifies input-cost risk for lithium-based small batteries and increases the value of long-term supplier agreements, tolling options, and alternative chemistry hedges.
- Regulatory tightening and safety standards: The EU Batteries Regulation (Reg. 2023/1542) continues to impose substance restrictions, labeling, and extended producer responsibility requirements that materially affect packaging, traceability, and compliance costs. Complementary standards—UL 4200A and IEC 60086-4:2025—raise safety-testing and ingestion-mitigation requirements for button and coin cells. Companies that treat compliance as a product differentiator (and not just a cost center) will win commercial trust in regulated markets.
- Product-level safety innovation: The recent introduction of taste-aversion (“bitter”) coatings by a major coin-cell supplier exemplifies how small, manufacturable changes can materially reduce product liability risk and unlock adoption in medical and child-sensitive applications.
- Technology and portfolio shifts: Lithium-based formats continue to grow in relevance for high-value commercial use cases (medical devices, IoT, backup power), but legacy chemistries remain important where total cost, recyclability, or regulatory regimes favor alternatives. Strategic portfolio balance—rather than single-chemistry bets—remains the resilient option for most commercial OEMs.
- Market structure and competition: Moderate concentration provides incumbents pricing power in stable segments while creating ingress points for challengers that pursue narrow verticals or regional strengths. The 2025–2026 tradeshow cycle and product launches signaled renewed interest from large lithium players and diversified battery manufacturers seeking small-format exposure.
Competitive landscape: how leading players are positioned
PW Consulting’s competitive analysis profiles established and specialty players across chemistry types, channel focus, and application depth. Highlights:
- Energizer Holdings (St. Louis): Broad commercial portfolio across alkaline, lithium, and coin cells—strong channel relationships in retail and industrial supply. Strengths are brand equity and scale; opportunities are deeper industrial OEM penetration and services-led propositions for B2B buyers.
- Duracell Inc. (Bethel): Iconic battery brand with recent safety innovations (bitter coating on selected coin sizes). Duracell’s brand and consumer-trust advantage can be leveraged into commercial medical and safety-critical applications with appropriate certification playbooks.
- Panasonic (Osaka): Technology breadth across lithium coin cells and rechargeable chemistries; deep OEM relationships in electronics and medical devices. Competitive edge comes from integrated manufacturing and materials know-how.
- VARTA (Ellwangen) & Maxell (Tokyo): Specialist strengths in micro and hearing-aid segments, with industrial positioning in medical and precision instruments. Their selective focus allows premium pricing in regulated niches.
- GP Batteries (Hong Kong): Regional manufacturing footprint serving both consumer and light-commercial segments—well-positioned for fast-turn procurement and regional rollouts.
- EnerSys, GS Yuasa, Power-Sonic: These firms emphasize sealed lead-acid and small-format VRLA/lithium products for standby, UPS, and industrial backup—critical for commercial sites where runtime and safety certifications matter.
- Murata, Renata, Toshiba: Suppliers that concentrate on coin and button cells for precision electronics and medical devices. Their value rests in miniaturization, consistency, and compliance documentation.
Across the board, we observe three strategic playbooks: (1) scale-and-reach incumbency (brand/channels), (2) niche-specialist premiumization (medical, hearing aids), and (3) supply-driven entry (raw-material or cell-technology integrators expanding into small formats). Each requires different commercial KPIs and investment timelines.
Five practical moves for executives in 2026
- Lock in diversified raw-material pathways: Combine multi-year purchase agreements for critical salts with spot exposure limits and a vendor-agnostic engineering bill of materials (EBOM) to permit chemistry substitutions where feasible.
- Design-to-regulation: Integrate EU Batteries Regulation and IEC/UL safety tests into product development sprints. Early regulatory qualification shortens time-to-contract for healthcare and public-sector customers.
- Operationalize safety as a commercial feature: Specify ingestion mitigation, tamper-proof packaging, and taste-aversion coatings in commercial tenders—convert safety into a price-justifiable service.
- Supplier scorecards and scenario clauses: Deploy scorecards that combine on-time delivery, compliance documentation, and life-cycle cost; include escalation and make-whole clauses for material-price shocks.
- Targeted M&A and partnerships: Pursue tuck-ins that add missing chemistries or regional footprints, and structure earn-outs tied to regulatory approvals and supply continuity milestones.
Scenario planning and sensitivity analysis
Our forecast model includes three policy-relevant scenarios: baseline (central macro assumptions), raw-material stress (prolonged high lithium carbonate pricing), and regulatory-constrained (accelerated EU/IEC/UL compliance costs). For each scenario we model top-line, gross margin sensitivity, and capex implications on a rolling 18–36-month planning horizon. Practical application: procurement teams can translate scenario outputs into specific contract tenors and inventory targets; product teams can use scenario triggers to defer or accelerate chemistry transitions.
What the full PW Consulting report delivers (practical, operational content)
- Detailed market model (2020–2032) with interactive scenario toggles and bottom-up volume/value build-ups.
- Regulatory and standards matrix (EU, UL, IEC) with compliance checklists and implementation timelines tailored to button/coin and small-format cells.
- Supplier benchmarking and scorecards across manufacturing footprint, testing capability, cost base, and EPR readiness.
- Cost build-up templates that convert raw-material price moves into SKU-level margin impacts.
- Procurement playbook and commercial contract templates (supplier KPIs, price-adjustment formulas, force-majeure clauses for raw-material shocks).
- Go-to-market playbooks by vertical (healthcare, industrial IoT, retail/PoS, security/alarms), including sales-handoff checklists and compliance qualification pathways.
- M&A screening tool with target profiles and valuation heuristics for strategic acquirers and financial sponsors.
Final note: how to use this intelligence in 90 days
Leaders should prioritize three actions in the coming quarter: (1) run a 90-day procurement stress-test using our raw-material stress scenario; (2) audit product portfolios against the IEC/UL/EU compliance matrix and prioritize safety-certification for top-revenue SKUs; (3) convene a shortlist of potential tuck-in targets or supply partnerships that fill chemistry or regional gaps. These steps convert PW Consulting’s strategic insights into measurable operational outcomes.
The summary here intentionally omits the granular segment-level numbers and regional/application splits that many transaction and procurement decisions require. PW Consulting’s full Commercial Small Batteries Market report contains the complete datasets, interactive forecast model, and all templates described above. Visit PW Consulting’s report page to access the comprehensive analysis, download the model, and schedule a briefing with our industry leads to translate the findings into a 2026 action plan.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com