

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Desktop Cloud Terminal Market Set to Expand at a 4.98% CAGR Through 2032, Report Finds
By pmarketresearch, 2026-07-07
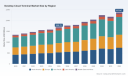
Desktop Cloud Terminal Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting today releases its authoritative Desktop Cloud Terminal Market briefing, tailored for CXOs, IT procurement leads and strategy teams preparing decisions in 2026. The global market for desktop cloud terminals has moved decisively from niche consolidation to broad enterprise adoption: by our accounting the market reached roughly USD 1.69 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 4.98% through the forecast window, driving the market toward roughly USD 2.38 billion by 2032. This report is crafted as a practical playbook — it surfaces the strategic inflection points, vendor dynamics and execution risks that will determine winners and losers next year, while reserving the granular segment-level datapacks for subscribers of the full study.
Desktop Cloud Terminal Market
Why 2026 Is a Pivotal Year
Several converging forces make 2026 an inflection year for desktop cloud terminals:
Desktop Cloud Terminal Market
- Cloud-native desktop adoption is broadening beyond early adopters. Organizations that pursued hybrid work during the pandemic are now revalidating long-term endpoint architectures under cost, security and sustainability constraints.
- Security frameworks such as zero-trust mandates and data-governance regulation are translating into specific procurement requirements for cloud endpoints and the clouds that host them.
- Data center economics are changing: rising energy costs tied to AI workloads are altering the total cost of ownership calculus for hosted desktop estates.
- Geopolitical trade controls and supply-chain constraints are forcing multinationals to rethink vendor sourcing and regional deployment models.
Each of these dynamics elevates the desktop cloud terminal from a commodity peripheral to a strategic technology choice that touches security, procurement, real estate and sustainability agendas.
Desktop Cloud Terminal Market
What the PW Consulting Report Delivers (Practical, Actionable)
The study is designed to move teams from high-level interest to executable decisions. Key deliverables include:
- Top-line market sizing and a transparent forecasting model covering 2026–2032, with scenario sensitivity to energy prices, regulatory constraints and DaaS adoption curves.
- Outcome-focused migration roadmaps — from pilot to scale — including templates for phased device refresh, service-level objectives (SLOs) and change-management milestones.
- A procurement playbook: RFP templates, evaluation scorecards and negotiation levers tailored to combinations of hardware vendors, hypervisor/platform partners and DaaS operators.
- TCO and ROI frameworks that fold in device CAPEX, lifecycle management, remote support costs, network and cloud hosting fees, plus sustainability metrics for enterprise ESG reporting.
- Risk heatmaps and contingency planning modules that quantify exposure to supply-chain disruption, export-control regimes and localized data-sovereignty requirements.
- Vendor benchmarking and competitive profiles (executive-level) that highlight strategic positioning, technical differentiators, go-to-market partnerships and recent product or certification moves.
- Strategic scenario analyses (three high-probability trajectories) to stress-test vendor selection and capacity planning decisions.
We deliberately present this output as a “trailer”: practical tools and frameworks that empower in-house teams to act now, while detailed segment matrices and the interactive model are securely accessible in the full report package.
Competitive Landscape: Who Matters and Why
The competitive field is composed of established PC OEMs, specialized thin/zero-client manufacturers and software-centric endpoint providers. Market concentration is moderate: the leading three firms account for roughly 42% of market volume, while the top five approach the mid-50s in aggregate share — a structure that combines scale advantages with room for niche and software-enabled challengers.
- Dell Technologies (Round Rock, Texas) — Strengths: broad channel footprint, Wyse portfolio optimized for Citrix, VMware Horizon and Microsoft Azure Virtual Desktop. Strategic posture: deep integration with enterprise IT stacks and multi-monitor, hybrid-work features. Recent move: launched a Wyse model in late 2025 with enhanced Windows 365 Cloud PC support and multi-display capabilities, signaling focus on DaaS compatibility.
- HP Inc. (Palo Alto, California) — Strengths: mature thin client line-up and enterprise services. Strategic posture: certification-led interoperability; delivers reliable endpoints for large-scale VDI and government deployments. Recent move: certification and compatibility updates with Citrix Horizon and Azure Virtual Desktop in late 2025, reflecting a defensive strategy built on platform trust.
- Lenovo Group (Beijing / Morrisville) — Strengths: leverages PC engineering for compact, cost-efficient thin clients and edge devices. Strategic posture: commodity-hardening with compute refresh (e.g., Ryzen-based models) to close performance gaps and appeal to performance-sensitive VDI workloads.
- IGEL Technology (Reading, UK) — Strengths: software-led differentiation through a secure, lightweight OS for cloud endpoints. Strategic posture: positioning as the secure, manageable endpoint layer with rapid protocol updates. Recent move: shipped a major OS iteration mid-2025 with native support for emerging cloud desktop protocols and zero-trust capabilities.
- 10ZiG Technology (Bristol, UK) — Strengths: specialist zero- and thin-client hardware with broad protocol support (PCoIP, Blast, RDP). Strategic posture: targeted vertical playbooks and deep VDI protocol optimization.
- Huawei Technologies (Shenzhen, China) — Strengths: strong regional presence and integrated cloud-desktop solutions compatible with local enterprise deployments. Strategic posture: competing on integrated stacks where regulatory alignment enables adoption.
- Acer (New Taipei City, Taiwan) — Strengths: value-oriented hardware and channel reach in SMB and education segments. Strategic posture: cost-effective endpoints for large-scale rollouts where price per seat remains a primary decision driver.
Across the vendor set, differentiation is amplifying along two axes: software and partnerships. Firms that pair compact hardware with a robust endpoint OS, lifecycle management and certified integrations with hyperscalers gain meaningful procurement leverage. Conversely, hardware-centric suppliers are pursuing performance upgrades and platform certifications to defend installed bases.
Regulatory, Energy and Geopolitical Headwinds
Decision-makers must plan against three non-negotiable constraints:
- Data governance and sovereignty rules — mandates in key jurisdictions require control over where and how desktop images and user data are stored and processed, creating compliance overlays for cross-border designs.
- Zero-trust and endpoint security standards — public sector and regulated firms increasingly require adherence to formal maturity models, effectively raising the bar for acceptable endpoint configurations.
- Supply-chain and export-control risks — controls on advanced compute hardware and regional supplier constraints introduce sourcing risk that can change lead times and component availability within months.
Layered on top, rising data-center energy costs—driven in part by AI workloads—alter hosted-desktop economics. Our models show sensitivity: modest increases in hosting OPEX can materially change the break-even horizon for migrating to a fully cloud-hosted desktop estate versus hybrid models.
Actionable Recommendations for 2026
PW Consulting’s operative advice for 2026 centers on a dual agenda: secure short-term wins and build optionality for disruptive shifts.
- Run targeted pilot programs that pair at least two hardware form factors with two software stacks (a hyperscaler DaaS + an on-prem VDI) to collect real performance and support-cost telemetry before committing at scale.
- Require vendor interoperability evidence as a gating criterion: certifications, independent lab results, and third-party reference sites that reflect your stack (hypervisor, protocol, identity provider).
- Embed security and compliance requirements into RFPs, including zero-trust alignment, patch cadence SLAs and supply-chain provenance clauses.
- Negotiate commercial terms that align incentives: volume-linked refresh credits, cloud-hosting discounts and warranty + remote-management bundles to reduce lifecycle support expenses.
- Quantify sustainability impact in procurement decisions: include energy consumption per seat and expected lifetime carbon metrics in vendor scoring to align with ESG goals.
- Develop a contingency sourcing plan that maps alternative suppliers and supports staged flexibility, mitigating risk from export controls or regional restrictions.
- Consider software-first contracts: where possible, separate hardware and software contracts to avoid vendor lock-in and preserve upgrade flexibility as protocols and security needs evolve.
How to Use This Study
PW Consulting designed this report for three archetypal users:
- Enterprise CIO/CTO teams who need a roadmap to replace legacy desktops while balancing security and cost pressures.
- Procurement and vendor management leaders seeking proven RFP templates, scoring methodologies and negotiation levers.
- Corporate strategy and M&A teams scanning the supplier landscape for consolidation targets or partnership opportunities supported by validated market sizing and concentration metrics.
The public briefing above highlights the most consequential insights and decision levers. The full PW Consulting Desktop Cloud Terminal Market report contains the detailed models, downloadable TCO calculators, vendor scorecards and the segmentation datasets that enterprise teams rely on when writing contracts and budgets. Those detailed spreadsheets and the interactive scenario model are available only in the subscriber package — intentionally withheld here to ensure readers engage directly with the full research platform and its validation materials.
Next Steps
For teams mapping 2026 budgets and 3–5 year endpoint strategies, our recommendation is simple: use the next 60–90 days to set a strategic working group with representation from IT ops, security, procurement and finance. Deploy the study’s pilot checklist, run at least one multivendor proof-of-concept and use the PW Consulting scorecard to convert qualitative vendor claims into quantitative procurement outcomes.
PW Consulting stands ready to brief executive teams and run bespoke workshops to apply these findings to your unique estate and risk profile. The full report, interactive financial models and the complete vendor benchmark pack can be accessed through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Desktop Cloud Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Steering Column Market to Reach USD 3,969.5 Million by 2032 on a 5.96% CAGR; Asia Pacific Leads with USD 1,188.32 Million in 2025
By pmarketresearch, 2026-07-07
Modular Steering Column Market: A 2026 Strategic Playbook — PW Consulting Industry Brief
As automotive ecosystems accelerate through electrification, advanced driver assistance systems, and materials-driven lightweighting, the modular steering column has evolved from a mechanical commodity into a systems-level strategic asset. PW Consulting’s new Modular Steering Column Market report — synthesizing historical performance (2020–2025) and forward-looking projections (2026–2032) — equips C-suite leaders, procurement strategists, and product planning teams with the pragmatic intelligence needed to make high-stakes decisions in 2026. Our market model indicates the sector is on a steady expansion path with a compound annual growth rate of 5.96%, reinforcing that the segment offers both defensive resilience and targeted growth opportunities.
Modular Steering Column Market
Why this report matters to 2026 decision makers
- Timing for roadmap commitments: With product development cycles and supplier qualification windows increasingly compressed, 2026 is the last practical year for many OEMs and Tier‑1s to lock in modular steering column strategies aligned with 2028–2030 platform launches.
- Capital allocation clarity: A clear CAGR and multi-year market sizing allow finance and strategy teams to prioritize investments in electrified adjustment mechanisms, electronic locking modules, and material substitutions where payback curves are favorable.
- Regulatory and safety alignment: Compliance requirements (including energy-absorbing performance and functional safety for electronic modules) are shifting supplier evaluation criteria — making this report essential for risk‑adjusted procurement and engineering trade-off assessments.
Macro snapshot (methodology and headline figures)
Our analysis is built on audited historical data from 2020 through 2025 and generates a base-year market synthesis for 2025, with forecasts through 2032. All financials are presented in USD (Million). The headline: the global modular steering column market demonstrated consistent expansion through the base period and, under our central scenario, will sustain near‑term growth driven by increased adoption of configurable electronic adjustment systems, greater modularization across vehicle platforms, and OEM-led consolidation of supplier footprints. The market concentration profile is meaningful — the top three suppliers command a substantial share of the industry, while the top five collectively represent an even larger portion — creating both barriers and opportunities for challengers depending on capability differentiation.
Modular Steering Column Market
Key structural trends shaping the market
- Modularity as a platform lever: OEMs are treating the column as a cross-platform module to accelerate variant proliferation while containing complexity on wiring and seat-belt integrated systems.
- Electrified adjustment & integration: Electric tilt-telescope mechanisms and integrated column control modules are migrating from premium vehicles into mainstream segments, driven by user convenience expectations and packaging efficiency on electrified architectures.
- Safety and functional-safety convergence: Crash energy management requirements and ISO 26262 implications for electronic control units make column architecture decisions a combined mechanical-electronic-safety design challenge.
- Lightweighting pressure: Materials substitution (notably magnesium and aluminum alloys) and polymer-metal hybrids are increasingly specified to shave kerb weight and support EV range objectives.
- Supplier consolidation and specialization: Strategic M&A, platform bundling, and selective vertical integration are reshaping supplier roles — from component vendors to systems integrators.
Competitive landscape — what the leaders are doing and why it matters
Our competitive analysis profiles incumbent systems suppliers, their strategic positions, and the offensive/defensive plays that matter to buyers and investors.
Modular Steering Column Market
- Nexteer Automotive (Auburn Hills, MI): Nexteer is doubling down on modular EPS suites with scalable electric-assist column variants. Their recent introduction of a High-Output Column-Assist EPS demonstrates how suppliers can leverage modular commonality to serve both light vehicles and heavier applications — a model that shortens integration time for OEMs targeting multiple segments.
- thyssenkrupp AG (Essen, Germany): Known for adaptive crash behavior and differentiated load-path designs, thyssenkrupp positions modularity as a safety differentiator. For OEMs focused on higher mass-market and premium safety positioning, suppliers with proven crash performance adaptability remain essential partners.
- Kongsberg Automotive (Kongsberg, Norway): Their in-house end-to-end capability for tailored tilt-telescopic systems suits off-highway and commercial vehicle programs, where bespoke requirements and validation burdens favor suppliers able to deliver complete engineering throughput.
- Merit Automotive Electronics Systems (Spain/global): Merit’s focus on integrating convenience and security features within modular packages reduces wiring complexity and variant count — a compelling proposition for platforms seeking both cost and manufacturability benefits.
- NSK Ltd. (Tokyo): NSK’s use of engineered plastics for impact absorption and lightweighting highlights a materials-led route to compliance and performance, attractive for OEMs pursuing mass reduction without compromising crash behavior.
- Robert Bosch GmbH (Gerlingen): Bosch brings weight-saving material mixes and modular ergonomics tailored to commercial fleets, demonstrating how component-level innovation can unlock fleet economics through reduced fuel/energy consumption.
- ZF Friedrichshafen AG (Friedrichshafen): Through integrated control modules and a safety-heavy engineering pedigree, ZF’s approach exemplifies systems-level bundling that can simplify OEM software and diagnostics strategies.
- JTEKT Corporation (Osaka), Hyundai Mobis (Seoul), Mando Corporation (Seoul): These suppliers collectively reinforce the market’s balance between global scale and regional engineering strengths — each offering modular solutions within broader EPS/HPS ecosystems.
For procurement and R&D leaders, the implication is clear: supplier selection must be evaluated on an axis of modular commonality, functional-safety capability, materials roadmap, and integration into vehicle-level electrical/electronic architecture.
Regulatory, materials and engineering headwinds/opportunities
- Safety standards drive architecture choices: Long-established frontal crash requirements for energy absorption and controlled displacement remain non-negotiable design constraints. Suppliers that can validate predictable crush behavior while integrating electronic modules have a competitive edge.
- Functional safety for electronics: ISO 26262 compliance is a gating factor for electronic column control modules. Buyers should incorporate functional-safety maturity as a procurement KPI rather than an afterthought.
- Materials trade-offs: Magnesium and aluminum alloys offer attractive weight reductions and can substitute ferrous elements at favorable ratios, but material cost volatility and manufacturing readiness create trade-offs that must be quantified in total-cost-of-ownership models.
What’s inside the PW Consulting report — practical, decision‑ready deliverables
Built for actionable use in 2026 planning cycles, the report blends strategic intelligence with operational tools:
- Market model and scenario engine: A validated market-sizing baseline for 2025 and probabilistic forecasts through 2032 that allow users to test scenarios (e.g., accelerated EV adoption, materials price shocks, supplier consolidation).
- Supplier capability matrix: Comparative evaluation across modularity, crash performance, functional-safety maturity, global manufacturing footprint, and cost-to-serve considerations.
- Technology adoption roadmaps: Timing windows for electrified adjustments, electronic locking modules, and fully integrated column control units, mapped to typical OEM platform timelines.
- Procurement playbook: RFP templates, evaluation scorecards, and recommended contractual risk allocations for warranty, software integration, and performance validation.
- Investment and M&A signal map: Criteria to identify acquisition targets and partnership archetypes that accelerate capability acquisition or market entry.
- Case studies and engineering trade-offs: Example trade-off analyses demonstrating how materials substitution, modular commonality, and electronic integration affect mass, cost, and safety outcomes.
To preserve commercial sensitivity and adhere to the “preview” principle, the report summarizes high‑level findings and frameworks while reserving detailed segment-level figures, regional splits, and vendor-specific revenue estimates for subscribers and authorized purchasers.
How to use the intelligence in 2026 — three tactical recommendations
- Start supplier dual‑sourcing with modular alignment: Use the supplier capability matrix to identify a primary integrator and a secondary specialist. Focus the primary on platform commonality and the secondary on niche capabilities (e.g., high‑output column assist, heavy‑duty crash behavior).
- Embed functional safety early: Make ISO 26262 compliance and demonstrable safety-engineering artifacts mandatory in early RFP stages to avoid costly redesigns during validation.
- Run a materials volatility stress test: Quantify P&L sensitivity to magnesium/aluminum price swings and evaluate hedging or forward sourcing strategies for critical alloy inputs.
Concluding perspective
As vehicles become more software-defined and platforms proliferate across powertrain architectures, the modular steering column sits at an intersection of mechanical design, electronic control, materials engineering, and safety regulation. For executives mapping 2026 investment plans, the core question is not whether to engage with the modular column market, but how to architect supplier relationships, technology choices, and procurement processes to convert that engagement into a competitive advantage.
PW Consulting’s Modular Steering Column Market report provides the market-sizing, supplier intelligence, engineering trade-offs, and procurement playbooks required to make those decisions with confidence. For full access to the proprietary segmentation, regional breakdowns, and supplier revenue estimates that underpin our recommendations, please follow the link on PW Consulting’s official report page.
For detailed analysis of this topic, please visit the official page: Modular Steering Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Electrode Boiler Steam Humidifier Market to Reach USD 325.25 Million by 2032, Growing at a 5.85% CAGR
By pmarketresearch, 2026-07-07
Electrode Boiler Steam Humidifier Market — Strategic Roadmap for 2026 Decision-Makers
Executive summary
As building decarbonization, electrification of HVAC systems, and stricter indoor air quality expectations converge, electrode boiler steam humidifiers have moved from niche HVAC components to strategic assets for commercial, healthcare and critical infrastructure operators. PW Consulting’s latest market study (base year 2025, historical review 2020–2025, forecast period 2026–2032) quantifies this transformation and translates it into a practical playbook for executives making resource allocation, product, and M&A decisions in 2026.
Electrode Boiler Steam Humidifier Market
Key macro takeaways: the global electrode boiler steam humidifier market is sized at approximately USD 218.45 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.85% over the forecast period, reaching roughly USD 325.25 Million by 2032. That trajectory reflects steady demand underpinned by portfolio modernization in commercial real estate, growing requirements from data centers and healthcare facilities, and supplier responses to material and energy dynamics.
Electrode Boiler Steam Humidifier Market
Why 2026 is a pivotal planning year
-
CapEx and product roadmaps synchronized with decarbonization targets: Many owners and specifiers will make three‑to‑five year procurement commitments in 2026 — these choices lock in energy profiles and integration complexity for the next decade.
Electrode Boiler Steam Humidifier Market -
Technology convergence: Electrification of humidification creates opportunities for feature differentiation (digital control, energy monitoring, hygiene diagnostics) that will influence specification lists and lifecycle economics.
-
Supply chain and materials pressure points are crystallizing: A clearer view in 2026 of stainless steel availability, tariff regimes, and component lead times will drive procurement and make-or-buy decisions.
Market trajectory and practical implications
The market’s mid-single-digit CAGR to 2032 implies a stable expansion rather than explosive disruption. For business leaders, that profile yields two strategic imperatives:
-
Focus investment on margin-enhancing differentiation (control systems, hygienic design, service models) rather than competing solely on price.
-
Use 2026 as a consolidation point: target partnerships and selective bolt‑on acquisitions that accelerate access to high-value channels (healthcare, hyperscale data centers, retrofit specialists).
Dynamics shaping demand
-
Electrification and decarbonization: The shift from fossil‑fuel dependent steam systems to electric electrode boilers aligns with broader building decarbonization goals. Buyers increasingly evaluate humidifiers on lifecycle energy and integration with building management systems.
-
Hygiene and operational simplicity: Electrode systems that operate on potable water without requiring reverse‑osmosis (RO) simplify installation and reduce operating complexity — a meaningful selling point in healthcare and education markets where uptime and infection control matter.
-
Digital and value‑added services: Smart controls, remote diagnostics, and energy analytics are accelerating from nice‑to‑have to procurement gatekeepers in specification documents.
-
Raw material volatility: Stainless steel remains a primary material for cylinders and enclosures. As of September 2025, US hot rolled stainless steel coil prices averaged around USD 1,860 per metric ton. Even modest upstream price or supply shifts materially affect OEM margins and sourcing strategies.
Competitive landscape — practical takeaways
The market shows moderate concentration: the top three players account for a significant share of installed capacity, and the top five capture a majority of commercial sales. This structure favors established brands but leaves meaningful room for specialists and value‑add entrants.
-
Condair Group AG (Switzerland) — Known for the Condair EL line, Condair emphasizes hygienic steam production, water conductivity management to extend cylinder life, and IP55-rated outdoor options for rooftop use. Recent product documentation and a 2026 catalog highlight renewed investment in touch screen controls and embedded energy analysis.
-
DriSteem (United States) — Offers the XT/XTR series and has recently redesigned its XT Series to boost reliability and user experience for commercial applications, signaling an intensified focus on serviceability and end‑user ergonomics.
-
CAREL (Italy) — Focuses on immersed electrode models (humiSteam, compactSteam) that stress precision control and potable water operation, appealing strongly to isothermal applications with tight humidity control requirements.
-
steamOvap technologies inc. (Canada) — Positions for easy maintenance and compatibility across water types; energy efficiency and retrofit flexibility are core claims.
-
Thermolec (Canada) — Targets commercial grade solutions with a straightforward electric‑element approach; competitive where operational simplicity is prioritized.
-
Armstrong International (United States) — Supplies electrode‑type humidifiers as part of a broader steam and thermal portfolio — attractive to buyers seeking integrated steam solutions.
-
Honeywell (Resideo) (United States) — Delivers whole‑home and compact unit solutions (HM750) with smart controls and self‑diagnostics; a strong play in residential and light commercial segments where integration and brand trust matter.
Recent vendor actions — product catalog updates, refreshed submittals, and redesigned product lines — indicate suppliers are leaning into enhanced controls, serviceability, and digital analytics to defend specification slots and aftermarket revenue.
Where value is being created (and captured)
-
Productized integration: Units that simplify rooftop or mechanical room installations and provide standardized control interfaces reduce commissioning time and capture higher margin service contracts.
-
Aftermarket services: Proactive maintenance subscriptions, consumables supply, and remote monitoring are recurring revenue levers that materially improve lifetime value.
-
Retrofit solutions: Given the long lifecycle of buildings, retrofit kits and modular cylinder replacements accelerate adoption without requiring full system rip‑outs.
-
Supply chain resilience: Manufacturers that diversify stainless steel sources, optimize inventory for critical components, or lock in regional coil contracts will manage gross margin volatility better.
Strategic playbook for executives in 2026
Based on our bottom‑up modeling and interviews with specification engineers, procurement leads, and OEMs, PW Consulting recommends the following priority moves for 2026:
-
Prioritize product features that buyers will pay for: remote diagnostics, hygienic cylinder design, and simple potable‑water operation are table stakes in healthcare and data center bids. Reallocate R&D budgets from marginal price improvements to these differentiators.
-
Build retrofit-led commercial channels: Develop plug‑and‑play retrofit packages and partner with MEP contractors who dominate retrofit pipelines to shorten sales cycles.
-
Hedge raw material exposure: Negotiate multi‑year stainless steel supply agreements or consider vertical partnerships to protect margins against price spikes and regional tariffs.
-
Monetize service and consumables: Design consumables (e.g., electrodes, cylinder liners) and remote monitoring plans to create recurring revenue that smooths capital cycles.
-
Use targeted M&A to plug capability gaps: Seek acquisitions that add control software, data analytics, or install/maintenance networks rather than broad product overlap.
-
Align go‑to‑market to high‑value segments: Health systems, critical data centers, and retrofit of older HVAC infrastructure offer differentiated margins — focus sales effort and channel incentives accordingly.
What PW Consulting’s report delivers — operational content for 2026
The report is structured as an execution‑oriented toolkit rather than an academic summary. Executives will find:
-
Validated market sizing and growth scenarios (base year 2025), with sensitivity tables that translate material and energy price swings into P&L and payback impacts.
-
Competitive benchmarking across product, controls, warranty and aftermarket models, including supplier scorecards that surface where each vendor wins and where they are vulnerable.
-
Procurement playbooks for OEMs and end users: supplier selection frameworks, risk scoring, and negotiation heuristics tailored to 2026 supply conditions.
-
Commercial go‑to‑market templates: channel segmentation, bid strategies for healthcare and data centers, and retrofit pricing models.
-
Case studies and implementation checklists from recent commercial and institutional installs that outline commissioning pitfalls and best practices.
-
Decision support appendices: scenario models, total cost of ownership calculators, and a prioritized roadmap for R&D and product investments.
How to use this analysis in your 2026 planning cycle
Operationalize the report in three steps:
-
Run the provided scenario models against your margins and product mix to determine whether incremental investment in controls or service infrastructure yields higher ROI than capacity expansion.
-
Use the supplier scorecards to stress‑test your vendor roster; identify single‑sourcing risks and quantify the cost of dual‑sourcing or local stocking strategies.
-
Translate the retrofit channel templates into a pilot program: select a target geography and deploy a bundled retrofit offer with defined KPIs (installation time, first‑year service revenue, NPS).
Final perspective
The electrode boiler steam humidifier market in 2026 is a pragmatic growth story: steady demand, concentrated incumbent advantage, and clear spaces for differentiation. For executives, the choice is not whether to participate — it is how to position to capture higher margin, recurring revenues while insulating operations from material and energy volatility.
PW Consulting’s full market study provides the granular segmentation, regional and application splits, supplier share tables, and downloadable financial models necessary to convert these strategic themes into concrete investment and procurement decisions. To access the complete dataset, scenario models and supplier scorecards that underpin this briefing, please visit PW Consulting’s Electrode Boiler Steam Humidifier Market page and download the report package.
For detailed analysis of this topic, please visit the official page: Electrode Boiler Steam Humidifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Special Electronic Chemicals for Photoresist Market to Reach USD 4,146.57 Million by 2032, Growing at a 5.51% CAGR
By pmarketresearch, 2026-07-07
Special Electronic Chemicals For Photoresist Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting today releases an executive synthesis of our Special Electronic Chemicals For Photoresist Market study, built on a detailed base year of 2025 and a seven-year forecast horizon through 2032. The global market for electronic chemicals used in photoresist and photolithography processes reached approximately USD 2,850.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.51% over the 2026–2032 forecast window, reaching broadly above USD 4.1 Billion by 2032. For corporate leaders making capital, sourcing, R&D and M&A decisions in 2026, this study functions as a decision-grade intelligence product: it diagnoses structural shifts, quantifies exposure to regulatory and raw-material shocks, and presents executable playbooks for suppliers, integrated device manufacturers (IDMs), fabless companies and private equity investors.
Special Electronic Chemicals For Photoresist Market
What this means for 2026 strategies — high-level takeaways
- Growth is solid but selective: the market trajectory supports incremental capacity investments AND targeted innovation plays. The headline CAGR masks pockets of rapid technology-driven demand and areas of substitution risk.
- Concentration matters: the top three suppliers account for a meaningful majority of market share, and the top five firms capture an even larger portion of industry revenue — a dynamic that shapes pricing leverage, access to advanced formulations and partner selection for scaling fabs.
- Regulatory risk is now commercial: PFAS-related reviews and evolving U.S. state-level restrictions create short- to medium-term compliance and reformulation demands for key chemistries, particularly in photoacid generators (PAGs) and fluorinated additives.
- Raw-material purity and sourcing resilience are non-negotiable for leading-edge nodes: sub-10 nm processes impose impurity thresholds at parts-per-million and below, materially constraining qualified suppliers and increasing the value of vertically integrated or strategically partnered supply chains.
- Localization and capacity redundancy will be decisive: recent factory and JV announcements signal supplier commitment to localized capacity, which will influence lead times, qualification cycles and commercial terms for 2026 procurement cycles.
Why the market is primed for strategic plays in 2026
Photoresist and related electronic chemical demand remains tightly coupled to capital intensity and node transitions in semiconductors and advanced displays. While headline growth is steady, the underlying drivers are heterogeneous: pockets of aggressive investment in leading-edge fabs and display production are increasing demand for higher-specification resists, photoacid generators and electronic-grade solvents, while legacy nodes and some PCB applications exhibit slower growth or substitution potential.
Special Electronic Chemicals For Photoresist Market
Supply-side moves in the past 24 months underline this bifurcation. Major suppliers are expanding capacity and forming regional manufacturing footprints to reduce lead times and accelerate customer qualification. Examples include capacity and site expansions announced by leading manufacturers, and joint ventures intended to place production closer to key fab clusters. These developments both respond to and reinforce buyer preferences for supply security and technical co-development.
Special Electronic Chemicals For Photoresist Market
Competitive landscape — reading the playbook of incumbents and challengers
The market is shaped by a mix of large, vertically integrated chemical firms and smaller specialty formulators focused on niche applications. The incumbents maintain competitive advantage through scale, proprietary polymer platforms, and deep co-development relationships with leading fabs. Key strategic patterns observed across the competitive set include:
- Technology leadership via formulation depth: suppliers with advanced resist chemistries for EUV and immersion ArF continue to command premium access to leading-edge fabs. Players who maintain differentiated polymer and additive IP benefit from stickier customer relationships.
- Localized capacity and capacity-as-strategy: recent land acquisitions and new manufacturing site planning reveal a clear prioritization of geographic proximity to customers. This reduces qualification friction and mitigates logistics and trade-risk exposures.
- Sustainability and regulatory-driven product development: several leading suppliers are actively developing lower-PFAS footprint chemistries and non-fluorinated alternatives for specific lithography chemistries to anticipate regulatory constraints and customer procurement mandates.
- Specialist niche defenders: smaller firms and European niche suppliers focus on high-purity specialty products for research, electron-beam lithography and custom microfabrication segments, maintaining attractive margin profiles despite limited scale.
For executives benchmarking partners or acquisition targets, the competitive indicators to prioritize are not merely revenue or facility counts, but proprietary resin portfolios, PAG roadmaps, solvent purity management capabilities, and demonstrated regulatory foresight.
Regulatory and raw-material dynamics that will shape 2026 outcomes
Regulatory attention to PFAS and related fluorinated chemistries has moved from long-term risk to near-term commercial planning. Ongoing evaluations under major regulatory frameworks, and the uneven patchwork of state-level restrictions, will impose variable compliance costs across geographies. For companies exposed to PAGs and fluorochemical precursors, active scenario planning is required: reformulation timelines, customer acceptance cycles, and regulatory-driven supply chain reporting will all affect margin and time-to-market.
On raw materials, the industry faces two intersecting constraints: purity thresholds that tighten dramatically for advanced nodes, and concentrated supply of key monomers and specialty solvents. Our field research and supplier audits show that ultra-high-purity solvents and polymer resins operate at impurity ceilings measured in single-digit parts-per-million or lower for critical applications — a technical boundary that increases supplier qualification time and raises the value of in-house analytical capabilities and solvent-recovery programs.
What the PW Consulting report contains — practical, decision-ready modules
- Market-sizing and scenario model: 2020–2025 historical baseline and a 2026–2032 forecast with alternative demand scenarios and sensitivity to node adoption rates and display demand shocks.
- Competitive benchmarking: granular supplier capability mapping (technology, capacity posture, geographic footprint, customer concentration) and a CR-based concentration risk dashboard.
- Technology and formulation matrix: assessment of polymer platforms, PAG families, solvent systems, and hardmask/spin-on technologies with IP and reformulation risk scoring.
- Regulatory impact and mitigation playbooks: PFAS/TSCA scenarios, state-restriction implications, recommended product stewardship responses and contractual protections for buyers and sellers.
- Supply-chain stress-testing: procurement levers, dual-sourcing templates, inventory policies, and purchase-offtake structuring for capacity-constrained chemistries.
- Value-creation templates for investors: due-diligence checklists, margin improvement levers, bolt-on acquisition targets, and JV structuring examples tailored to high-barrier specialty chemistries.
- Operational toolkits: supplier scorecards, qualification timelines, analytical method checklists, and sample contractual clauses to manage raw-material substitution and regulatory change.
Priority actions for executive teams in 2026
- Re-evaluate supplier qualification timelines: build six- to twelve-month cushions for first-article approvals when qualifying alternate high-purity solvent and resin suppliers.
- Invest in regulatory-forward R&D: accelerate development of non-fluorinated or low-PFAS photoacid chemistries and build customer acceptance plans before hard mandates appear.
- Pursue strategic capacity partnerships: where capital intensity is high, consider JVs, capacity reservation agreements or local tolling arrangements to secure supply without full greenfield exposure.
- Operationalize purity and analytics: upgrade in-house impurity analytics and in-process monitoring to reduce qualification friction and support faster crash-repair during contamination events.
- Embed concentration risk into commercial planning: use supplier concentration metrics in pricing, inventory and renegotiation strategies to avoid single-source dependency shocks.
Case signals to watch in 2026 — leading indicators of structural change
- New site and capacity announcements by major suppliers and their pace of commissioning — these indicate where lead times and qualification friction will ease or persist.
- JV formations and regional operational setups near major fab clusters — these reveal supplier prioritization of localized supply models.
- Public movements on PFAS policy and state-level restriction timelines — they will materially affect reformulation urgency and contract terms.
- Customer trade-off decisions between cost, time-to-qualify and chemical performance — these will drive which chemistries scale and which become niche.
PW Consulting’s Special Electronic Chemicals For Photoresist Market study is designed to move beyond descriptive market commentary to provide executable intelligence for 2026 decision cycles. We present a clear synthesis of macro growth, supplier behavior and regulatory pressure — while retaining the proprietary, subsegment-level modeling and supplier scorecards that are essential to transactional and operational decisions. In this executive summary we have intentionally presented the high-value strategic insights and withheld detailed subsegment tables and granular regional/application splits to preserve the exclusive, actionable analytics contained in the full report.
For access to the full dataset, supplier scorecards, scenario models and operational toolkits — including the proprietary subsegment forecasts and regional/application breakdowns — visit the PW Consulting report page or contact our advisory team to request a briefing and licensing options. PW Consulting’s industry practitioners stand ready to support M&A diligence, procurement redesign, and regulatory contingency planning backed by the report’s empirical models and supplier-level intelligence.
For detailed analysis of this topic, please visit the official page: Special Electronic Chemicals For Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recycled Rare Earth Market Poised for Rapid Growth — 12.7% CAGR Signals Major Investment Opportunity
By pmarketresearch, 2026-07-07
PW Consulting: Recycled Rare Earth Market — Strategic Brief for 2026 Decision-Makers
Executive Snapshot
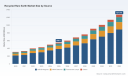
As decarbonization, electrification, and onshoring policies reshape critical material supply chains, recycled rare earths are rapidly moving from niche sustainability projects to core components of commercial strategy. PW Consulting’s new Recycled Rare Earth Market report — based on a rigorous base year of 2025 and a forecast horizon through 2032 — captures this transition with a practical, decision-oriented lens. Our analysis shows the recycled rare earth market expanding from roughly USD 550.6 Million in 2025 at a compound annual growth rate (CAGR) of 12.7%, with a projection that it will cross the USD 1.2 billion threshold by 2032. For corporate leaders planning capital, sourcing, or product strategy in 2026, this is not a theoretical trend: it is a fast‑moving commercial frontier.
Recycled Rare Earth Market
Why 2026 Is a Turning Point
Policy and commercial signals that crystallized in 2024–2025 continue to set the stage for near-term market reconfiguration. Export controls and secondary‑resource regulations introduced by major producing countries, paired with tariff measures and procurement preferences in importing markets, are creating both supply disruption risk and commercial windows for domestic recycling and closed‑loop supply models. Meanwhile, OEM commitments and new recycling facilities are converting pilot‑scale demonstrations into predictable supply streams.
Recycled Rare Earth Market
For executive teams that must decide in 2026 whether to build, buy, or partner for recycled rare earth feedstock, the margin for error is narrowing. Our report turns that narrowing window into actionable options—identifying where near-term investments can convert into medium‑term strategic advantage, and where tactical partnerships are the lower‑risk route to access recycled REEs.
Recycled Rare Earth Market
Market Trajectory — What the Numbers Signal
-
Historic momentum: The market more than doubled in the 2020–2025 period, evidence of accelerating collection, processing innovation, and commercial acceptance.
-
Sustained growth outlook: A projected CAGR of 12.7% across the 2026–2032 forecast period supports the business case for capacity build‑outs and long‑term offtake contracts.
-
Scale inflection ahead: Our scenario work highlights a transition from fragmented pilot capacity in 2025 to industrial‑scale hubs by the late 2020s — a structural shift that will alter sourcing economics and supplier bargaining power.
Key Demand and Supply Drivers
-
Demand pull from electrification and high-performance magnets: Continued adoption of high‑energy permanent magnets across EV powertrains, wind turbines, and industrial motors underpins long‑term material demand.
-
Policy accelerants: Tariffs, strategic procurement, and export controls are incentivizing domestic recycling and alternative supply chains in several consuming nations. These measures are driving investment decisions in recycling capacity and influencing siting choices.
-
Cost and circularity: Improved hydrometallurgical and short‑loop magnet‑to‑magnet processes are reducing the economic gap with primary production and creating attractive total‑cost propositions for manufacturers seeking secure, lower‑carbon feedstock.
-
Collection and logistics constraints: The pace of scaling recycled rare earths will be constrained by collection streams, disassembly logistics, and reverse‑supply‑chain economics unless coordinated collection programs and standardized material specifications are implemented.
Competitive Landscape — Who Matters and Why
The competitive field is heterogeneous, comprising technology innovators, integrated processors, and specialist recyclers. These actors are pursuing differentiated paths — short‑loop magnet-to-magnet recycling, mixed rare earth oxide (MREO) production, and pre‑processing services that feed larger refining facilities. Key participants we analyze in the report include both established metals recyclers and new entrants building industrial hubs.
-
Cyclic Materials (Toronto) — Operating North America’s first facility producing recycled MREO from end‑of‑life magnets and expanding to a larger campus in the U.S., Cyclic is a textbook example of an operator scaling proprietary hydrometallurgical routes into hub‑and‑spoke processing networks.
-
MP Materials Corp. (USA) — An integrated rare earth producer implementing commercial‑scale magnet recycling to create closed‑loop supply for permanent magnets; their model illustrates integration from feedstock recycling to magnet manufacturing and strategic OEM collaborations.
-
American Resources Corporation (via Electrified Materials) — Expanding pre‑processing capabilities domestically to aggregate manufacturing scrap and end‑of‑life magnet materials, positioning itself as a key aggregator for downstream processors.
-
Hitachi Metals — A legacy materials firm applying proprietary magnet recycling methods, demonstrating how incumbent OEM suppliers can adapt manufacturing capabilities into circular supply offers.
-
HyProMag / Mkango — Advancing hydrogen processing and short‑loop magnet refurbishment at scale, representing an alternative pathway that preserves magnetic properties with a lower material footprint.
-
Specialists and regional recyclers (e.g., Geomega, Umicore, Accurec, REEcycle, Carester) — A mix of technology developers and service providers that will be critical to regional supply resilience and niche processing requirements.
Our competitive analysis does more than name players: the report maps capabilities to commercial needs (feedstock aggregation, metallurgical conversion, magnet remanufacture, regulatory compliance), and assesses where partnership, equity investment, or offtake contracting can unlock faster access to recycled feedstock.
Regulatory and Geopolitical Considerations
-
Export controls and secondary‑resource regulations from major producing countries have raised both the strategic importance and near‑term uncertainty of cross‑border supply. Policymakers’ moves to protect technologies and materials create arbitrage opportunities for onshore recyclers but also increase compliance burdens for downstream users sourcing global feedstock.
-
Tariff regimes and procurement preferences in key consuming markets are likely to favor domestically processed recycled material and may shorten the time horizon for commercially viable domestic recycling projects.
-
Companies must therefore embed regulatory scenario planning in commercial decisions, using multi‑jurisdictional compliance frameworks and traceability systems to avoid disruptions and preserve market access.
Practical Strategic Recommendations for 2026 Decisions
PW Consulting translates market signals into a sequenced set of actions for corporate leaders. Below are the pragmatic levers we recommend prioritizing in 2026:
-
Secure optionality through layered contracts: Combine short‑term offtake with staged capacity commitments. Where capex is uncertain, prefer anchor offtakes with staggered startup milestones tied to feedstock quality and traceability metrics.
-
Fast‑track feedstock aggregation partnerships: Work with scrappers, OEMs, and electronics recyclers to standardize disassembly and packaging specifications to increase feedstock yield and predictability.
-
Prioritize technology and process diligence: Conduct metallurgical piloting and head‑to‑tail lifecycle assessments before committing to large capital projects; evaluate both hydromet and hydrogen‑based short‑loop solutions against quality and energy intensity metrics.
-
Map regulatory scenarios to investment triggers: Build decision trees that link regulatory shifts to go/no‑go capital triggers and contractual flex provisions.
-
Use modular capacity strategies: Favor hub‑and‑spoke or scalable modular facilities to manage collection variability and reduce stranded asset risk.
-
Embed traceability and ESG KPIs: Recycled rare earths’ commercial premium will depend on auditable claims for origin, carbon footprint, and circularity—build those capabilities into early contracts and reporting systems.
What the Report Delivers — Practical, Not Theoretical
PW Consulting’s Recycled Rare Earth Market report is designed for executives making 12–36 month deployment decisions. The deliverables include:
-
A dynamic market model calibrated to 2025 base year inputs and multiple 2026–2032 scenarios, enabling custom sensitivity runs for price, feedstock availability, and policy shifts.
-
Supplier and technology scorecards that evaluate process maturity, throughput scalability, capital intensity, and ESG metrics — presented as decision matrices to support build vs. partner choices.
-
Operational playbooks for feedstock collection programs, reverse logistics, and pre‑processing specifications to improve recovered rare earth yield and reduce processing variability.
-
Commercial contracting templates and offtake structures tailored to recycled material characteristics, including quality bands, acceptance testing, and escalation clauses tied to regulatory outcomes.
-
Investment prioritization and M&A frameworks to identify high‑value acquisition targets, minority equity partnership structures, and earn‑out mechanics that align incentives across the circular value chain.
-
Regulatory impact maps and compliance checklists for multi‑jurisdictional sourcing strategies, including traceability requirements and risk‑mitigation tactics for export control events.
Next Steps — How to Use This Intelligence in 2026
Decision-makers should treat recycled rare earths not as an optional green premium but as a strategic resource class requiring the same rigor applied to primary sourcing: scenario‑based planning, contractual staging, technology validation, and regulatory hedging. In 2026, companies that align procurement, R&D, and public affairs around a coherent recycled‑REE strategy will secure both supply resilience and potential cost and carbon advantages as the market scales.
Access the Full Report
This release is a strategic summary intended to demonstrate the report’s practical value. For the full dataset, segmented modelling, supplier heatmaps, and downloadable commercial templates, PW Consulting invites stakeholders to access the complete Recycled Rare Earth Market report on our website. Our client services team is also available for bespoke briefings, scenario workshops, and transaction support to convert market insight into executable deals.
PW Consulting — actionable intelligence for leaders building the circular critical‑materials economy.
For detailed analysis of this topic, please visit the official page: Recycled Rare Earth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Electronic Grade Adhesives Market to Rise from USD 6,380.0M (2025) to USD 9,797.7M by 2032 at 6.32% CAGR — Asia‑Pacific Leads with USD 3,522.3M
By pmarketresearch, 2026-07-07
Electronic Grade Adhesives Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Electronic Grade Adhesives frames a pragmatic, execution-oriented roadmap for executives planning investments, sourcing, and product development across the electronics and semiconductor value chain in 2026. The report synthesizes historical performance (2020–2025), delivers a seven-year forecast (2026–2032) and translates technical, regulatory and supply-side signals into concrete strategic options — while reserving the detailed segment tables and proprietary supplier scoring for readers who access the full report.
Electronic Grade Adhesives Market
Why this report matters in 2026
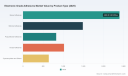
- Actionable market sizing anchored to a 2025 base-year: the electronic-grade adhesives market reached approximately USD 6,380 Million in 2025 after steady expansion from 2020. Our topline historical series (2020–2025) and forward-looking model project continued expansion through 2032, reaching roughly USD 9,798 Million by 2032 under a core-case CAGR of 6.32% for the forecast period.
- Decision focus: Procurement managers, product leaders, and M&A teams need to convert material science trends and regulatory shifts into supply-chain design, portfolio pivots, and capital deployment plans. This study translates technical drivers — from underfill reliability to thermal interface innovation — into investment-ready hypotheses for 2026 action.
- “Trailer” approach to intelligence: we reveal the market architecture, competitive dynamics, cost drivers and risk scenarios to establish credibility, but hold detailed subsegment shares, price curves, and our proprietary supplier-score matrices behind the report gateway to incentivize direct engagement.
Topline market dynamics and what they imply
The adhesives market serving electronics and semiconductor packaging has shown resilient growth across recent cycles. From a market base of around USD 4,832 Million in 2020, the sector expanded to approximately USD 6,380 Million by 2025. Our forecast anticipates continued steady growth, driven by semiconductor packaging complexity, miniaturization of consumer devices, electrification in automotive and broader industrial digitization.
Electronic Grade Adhesives Market
Key implications for executives in 2026:
Electronic Grade Adhesives Market
- Capacity planning must assume sustained mid-single-digit growth: the 6.32% CAGR embedded in our core forecast implies steady demand for both commodity and differentiated adhesive formulations.
- Product roadmaps should prioritize thermal management and reliability-grade chemistries: higher power-densities and fine-pitch assemblies put premium on thermally conductive, low-outgassing, and lead-free formulations.
- Supply security and cost pass-through deserve renewed attention: raw-material volatility and regional regulatory shifts materially affect formulations, throughput and qualification cycles.
Raw materials, regulation and cost pressure — the operational triangle
Three supply-side forces are shaping strategy windows in 2026:
- Raw-material price dynamics. Northeast Asia and European epoxy resin markets have seen firmer price points in early 2026, reflecting tightness in feedstocks such as bisphenol A and epichlorohydrin and persistent demand from electrical laminates and electronics segments. These movements create a two-speed margin environment: commodity epoxies under pressure, while specialty halogen-free and low-impurity grades command premium pricing.
- Regulatory impetus. Continued regulatory scrutiny — notably the EU REACH classification pathway for bisphenol A as an SVHC — is accelerating formulation shifts toward low-impurity and halogen-free epoxy systems for electronics. For companies selling into EU and global OEMs that adopt REACH-aligned specifications, reformulation timelines are now a procurement and qualification priority for 2026.
- Trade and supply policy. Recent determinations affecting cross-border resin flows have altered near-term sourcing strategies. While some trade remedies were not sustained in early rulings, the interpretive uncertainty has led many manufacturers to diversify supplier lists and vertically secure key intermediates.
What the report provides — practical, executable content
This study is intentionally operational. It is built for executives who must act fast and pragmatically on partial information. Deliverables include:
- Top-down and bottom-up market sizing with scenario variants (baseline, upside, downside) calibrated to technology adoption and macro inputs.
- Seven-year forecast (2026–2032) with sensitivity testing to raw material price paths, regional demand shocks and packaging technology shifts.
- Vendor scorecards and go-to-market playbooks evaluating technical capabilities, channel strategies, geographic footprint and vertical focus. (Note: full scorecards and scoring weights are provided in the full report.)
- Operational playbooks covering qualification timelines, sample economics, and process replication protocols to accelerate application engineering cycles in high-reliability markets.
- Procurement tools: a supplier-risk heatmap, contract language templates for raw-material pass-through, and a six-month cost-monitoring cadence tailored to adhesives buyers.
Competitive landscape — who matters and why
The market exhibits moderate concentration: our concentration metrics indicate that the top three suppliers account for a significant, but not dominant, share (CR3 ~36.5%), while the top five represent close to half of the market (CR5 ~49.1%). This structure creates space for global leaders to leverage scale while enabling medium-sized specialists to capture niche, high-margin pockets related to advanced packaging and light-curable systems.
- Henkel AG & Co. KGaA (Düsseldorf) — A leading integrated supplier with a broad portfolio across underfills, die attach adhesives and thermal materials. Recent factory and lab investments (including expansion of application engineering facilities) reinforce Henkel’s strategy of coupling material innovation with on-site process replication for OEMs and OSATs.
- 3M Company (St. Paul) — Strong in structural and fast-curing systems, with a growing distribution footprint via channel partnerships. 3M’s focus on thermal stability and fast-cure chemistries aligns with OEM demand for accelerated production and miniaturization.
- Dow Inc. (Midland) — Notable for silicone-based systems that serve harsh-environment and display applications. Dow’s DOWSIL line remains relevant where primerless adhesion and environmental resilience are required.
- H.B. Fuller, Sika, Momentive, Wacker, Shin-Etsu — Regional and global players offering complementary portfolios for PCB protection, sensor sealing and thermal management; many pursue targeted M&A and application-engineering expansion to capture automotive and industrial electronics growth.
- Dymax, DELO, YINCAE, NAMICS — Specialist suppliers focused on light-curable systems, precision bonding and advanced underfills for fine-pitch semiconductor packaging. These firms are primary beneficiaries of high-reliability packaging trends.
- Huntsman — A key epoxy-resin and formulated-system supplier, particularly relevant for encapsulants and potting compounds used in high-performance electronics.
Recent corporate moves highlight two strategic themes: (1) closer proximity to customers via R&D and application labs (e.g., new R&D centers and lab expansions) to shorten qualification cycles; (2) channel and distribution agreements to accelerate aftermarket reach and small-batch production adoption. Examples include new R&D activities in Silicon Valley, multiple lab expansions in Southeast Asia, and distribution partnerships that broaden access to specialty formulations.
Risks, blindspots and what to hedge in 2026
- Material availability and price volatility: maintain dual-sourcing and examinate backward-integration where feedstock exposure is material to unit economics.
- Regulatory compliance and reformulation risk: accelerate REACH-aligned reformulation workstreams if selling into or through European OEMs; anticipate extended qualification windows.
- Qualification lead times: procurement and product teams must account for multi-stage testing (thermal cycling, drop, moisture sensitivity) when planning product launches — schedule slippage remains the most common execution failure.
- Technology displacement: light-curable and novel thermally conductive adhesives are adoption risks to legacy epoxies; targeted product development and selective partnerships can mitigate loss of share.
Strategic recommendations for 2026
- Prioritize supplier relationships that provide co-development and on-site process replication capabilities — the ability to qualify adhesives within a customer’s assembly environment is a competitive differentiator.
- Execute a two-track portfolio strategy: protect commodity-margin through scale efficiencies while selectively investing in premium formulations for thermal management and fine-pitch packaging.
- Use procurement contracts to transfer active raw-material risks and to secure capacity for critical intermediates during project qualification phases.
- Accelerate targeted partnerships with equipment and materials specialists to shorten qualification cycles for light-curable and low-outgassing systems used in high-density assemblies.
Next steps — where to get the full intelligence
PW Consulting’s Electronic Grade Adhesives Market report is designed as a decision engine for 2026. The full dossier includes detailed subsegment tables, regional and application splits, price models, proprietary supplier-scorecards, and downloadable procurement templates that are intentionally withheld from this preview. For teams building sourcing strategies, technical roadmaps, or M&A theses this year, the full report converts the themes above into executable workplans and model-ready inputs.
Visit the PW Consulting report page to access the complete dataset, supplier heatmaps and our interactive scenario model. PW Consulting’s analysts are available to conduct tailored briefings and walk-throughs for procurement, R&D and corporate development teams preparing for 2026 execution.
For detailed analysis of this topic, please visit the official page: Electronic Grade Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metaverse in Manufacturing Market Poised to Grow at a 28.5% CAGR, Revolutionizing Factory Operations
By pmarketresearch, 2026-07-07
Metaverse in Manufacturing Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
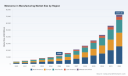
As manufacturers shift from exploratory pilots to enterprise-grade deployments, the industrial metaverse is transitioning from blue-sky promise to boardroom priority. Our new PW Consulting report — Metaverse in Manufacturing Market (base year 2025) — synthesizes five years of historical market movement and a seven-year forecast to deliver actionable guidance for executives planning 2026 investments. The market has expanded rapidly (from a small base in 2020 to approximately USD 12.5 billion in 2025) and is projected to continue at a double‑digit pace (CAGR 28.5%), reaching well into the tens of billions by the early 2030s. This brief highlights the strategic value of the full report for decision-makers while preserving the proprietary segmentation detail contained in the complete study.
Metaverse In Manufacturing Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the inflection point where infrastructure readiness (GPU compute, real‑time physics engines), standards convergence, and vendor maturity align to enable scalable industrial metaverse deployments. Our forecast shows meaningful market acceleration in 2026, making the next 12–18 months decisive for capability-building versus vendor lock‑in.
Metaverse In Manufacturing Market -
Risk‑to‑reward optimization: The report provides a structured approach to prioritize proofs‑of‑value that de‑risk full-scale rollouts. We map tactical pilots to enterprise objectives (throughput improvement, downtime reduction, time‑to‑market compression) and quantify investment horizons so leaders can make defensible capital allocation decisions in 2026.
Metaverse In Manufacturing Market -
Vendor and ecosystem plays: Rapid strategic partnerships and platform integrations from major technology vendors are reshaping procurement choices. Our analysis reveals how platform-led alliances and open‑standards adoption will determine integration cost and future optionality—key considerations for procurement teams and CIOs evaluating 2026 roadmaps.
High‑level market dynamics (what the numbers tell us)
The industrial metaverse market has moved beyond isolated proofs and is now scaling across manufacturing value chains. Growth across 2020–2025 demonstrates strong market validation; the forecast period (2026–2032) reflects continued compound growth driven by three structural forces: (1) persistent productivity pressure across manufacturing tiers, (2) maturity of real‑time 3D and physics simulation platforms, and (3) expanding enterprise adoption of AI‑enabled digital twins. While we intentionally withhold detailed splits in this summary, the full report dissects demand by technology families, application clusters and regional adoption patterns to help leaders prioritize 2026 investments.
Practical, decision‑ready content in the full report
-
Actionable adoption playbooks: End‑to‑end pilot templates for manufacturing use cases (e.g., digital twin simulation, immersive training, collaborative product development, remote maintenance) that specify scope, success metrics, data requirements, tooling, and sample budgets tailored for 2026 procurement cycles.
-
Vendor evaluation matrix: A comparative framework that evaluates platform providers across technology maturity, integration readiness, partner ecosystems, compute dependency and commercial models—designed to accelerate vendor shortlisting without requiring proprietary RFP redesign.
-
Integration & infrastructure blueprint: Guidance on hybrid cloud/edge architectures, high‑performance GPU requirements, real‑time synchronization, security and data governance patterns that are important for scaling from pilot to plant‑wide deployments.
-
ROI and total cost of ownership models: Financial templates and sensitivity analyses that quantify productivity, uptime and training cost benefits under conservative, mid and aggressive adoption scenarios so CFOs can compare metaverse investments against alternate digitalization projects.
-
Change management and workforce pathways: Practical programs to re‑skill frontline workers, integrate metaverse workflows into standard operating procedures, and design governance for cross‑discipline collaboration between IT, OT and engineering functions.
Competitive landscape — platform makers, system integrators and industrial champions
The competitive picture is evolving fast. Leading platform vendors and industrial incumbents are moving beyond standalone products to ecosystem plays, combining real‑time 3D engines, simulation cores, and industrial IT integration.
-
Siemens AG (Munich) is positioning its Xcelerator suite and new Digital Twin Composer (announced for broader availability in 2026) as a backbone for large‑scale, physics‑based factory digital twins. Siemens’ strategy emphasizes lifecycle integration from planning through adaptive manufacturing—targeting customers that need enterprise coherence across engineering and operations.
-
NVIDIA Corporation (Santa Clara) has catalyzed an industrial metaverse stack through Omniverse, focusing on photorealistic, physics‑accurate real‑time simulation and GPU performance. Recent 2026 partnership activity underscores NVIDIA’s role as the computational platform enabler and a convenor of industrial software partners.
-
Dassault Systèmes (France) leverages 3DEXPERIENCE for virtual twins and immersive collaboration, emphasizing design‑to‑manufacture continuity and spatial computing partnerships—appealing to complex engineering organizations.
-
PTC Inc. (Boston) brings AR/MR and the digital thread narrative, with Vuforia and integrated lifecycle capabilities that suit manufacturers seeking rapid field‑worker augmentation and traceable change management.
-
Microsoft Corporation (Redmond) combines Mesh and HoloLens for collaborative use cases at scale, offering cloud and identity services that can simplify enterprise deployment, especially for companies already standardized on Microsoft stacks.
-
Unity Technologies (San Francisco) provides a developer‑friendly real‑time 3D engine tuned for simulation and training, attractive to teams requiring high‑fidelity interactions and rapid content iteration.
-
ABB Ltd (Zurich) is integrating robotics, AI and digital twins to deliver practical, plant‑level solutions—particularly where automation hardware and process control converge.
These vendors are not discrete choices but nodes in an ecosystem. The most successful industrial metaverse deployments in our study combine platform integrators with domain specialists and hardware suppliers. Recent product announcements and partnerships during late 2025 and early 2026 underscore a move toward interoperable stacks and co‑innovation engagements, with several platform vendors seeking industrial anchor customers to validate scale and operational governance models.
Standards, regulation and infrastructure — the backbone of scale
-
Standards activity is accelerating. Bodies such as IEEE, IEC and ISO are advancing terminology, multimedia guidance, and digital twin interoperability specifications that will materially lower integration friction as they are codified. Executives should plan for compliance and interoperability testing as part of 2026 project definitions.
-
Infrastructure constraints—primarily high‑performance GPU compute and real‑time physics simulation—remain the principal technical gating factor for large‑scale, multi‑site deployments. Strategic vendor collaborations that combine platform software with specialized compute and edge orchestration are emerging as the pragmatic path to manage cost and latency.
How to use this report in your 2026 planning cycle
-
Prioritize pilot objectives by business value: Use the report’s ROI models to rank use cases and sequence pilots that deliver immediate operational benefits while preserving future integration flexibility.
-
Design procurements for modularity: Tender for interoperable building blocks (simulation engine, digital twin ontology, synchronization layer, edge compute) rather than monolithic solutions to avoid vendor lock‑in during the nascent phase of standards convergence.
-
Invest in internal capability accelerators: Establish cross‑functional metaverse centers of excellence and partner with neutral system integrators to compress the learning curve and capture reuse across facilities.
-
Govern for safety and IP: Formalize data governance, security baselines and IP frameworks early—these disciplines materially affect speed of adoption and contractual exposure when moving from pilot to production.
Final note — what to expect from the full intelligence package
This press brief maps the strategic landscape and identifies the decision levers that should shape 2026 programs. The full PW Consulting report contains the granular vendor scoring, use‑case financials, deployment playbooks and an interactive decision toolkit that senior leaders and program managers will find indispensable for operationalizing industrial metaverse strategies. To preserve competitive value for our clients, we intentionally reserve the core segmentation tables and proprietary scenario models for the complete report.
Access the full Metaverse in Manufacturing Market report and the executive toolkit on PW Consulting’s report portal to get the detailed breakdowns, vendor matrices and implementation templates you need to move from pilot to production in 2026.
For detailed analysis of this topic, please visit the official page: Metaverse In Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Essential Rose Oil Market Set to Reach USD 882.66 Million by 2032 at a 6.5% CAGR, with Europe Holding USD 213.72M in 2025
By pmarketresearch, 2026-07-07
Essential Rose Oil Market — Strategic Outlook 2026: PW Consulting Releases Actionable Intelligence for Executive Decision-Making
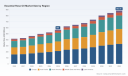
PW Consulting today publishes its Essential Rose Oil Market Report (base year 2025), a strategic briefing designed to inform 2026 sourcing, innovation, and M&A decisions across fragrance houses, cosmetic brands, contract manufacturers, and raw material traders. Combining an independently modelled market-size trajectory, a competitive map of incumbent growers and global processors, and a practical playbook for supply-chain resilience, the report translates sector complexity into executable options for senior management.
Essential Rose Oil Market
Why this report matters for 2026
-
A defined growth runway: Our model shows the global essential rose oil market expanding from USD 418.5 Million in 2020 to USD 568.0 Million in 2025, with a compounded annual growth rate of 6.5% through 2032, reaching an expected USD 882.66 Million by 2032. The near-term projection for 2026 is USD 624.27 Million. These headline figures frame the addressable economics for premium naturals strategies and validate continued investment in rose-derived formulations.
Essential Rose Oil Market -
Seasonal and concentration risk: Despite growth, supply dynamics remain fragile because production is highly concentrated geographically and intensely seasonal. Our synthesis of field-level reporting shows cultivation and harvesting continue to rely on a large seasonal workforce, with a very narrow harvest window—facts that materially affect spot availability, quality variation, and cost volatility.
Essential Rose Oil Market -
Strategic inflection points for buyers: The combination of predictable demand growth and constrained supply creates clear decision levers for 2026: diversify sourcing, invest in supplier partnerships and certifications, and consider structured offtake or backward integration to secure high-purity material for premium product tiers.
What’s inside the report — operational, not academic
-
Granular market modelling (2020–2032): time-series revenue scenarios under three demand-growth and price-volatility assumptions, enabling stress-testing of procurement strategies and SKU-level margin sensitivity.
-
Supply-chain blueprint: an operational map from seed to distillate, highlighting pinch points (labor, distillation capacity, storage, and logistics), break-even distillation economics, and a proprietary scorecard for supplier resilience.
-
Commercial playbook for 2026: contract templates, suggested offtake structures, and negotiation levers tailored to different buyer archetypes (boutique perfumers, global fragrance houses, CPG formulators).
-
Sustainability & traceability toolkit: roadmaps for implementing GEO/PO/chain-of-custody approaches and certification prioritization (organic, ethical trade), tied to product premiumization and regulatory expectations in key markets.
-
M&A and partnership shortlists: screened acquisition targets and JV archetypes with estimated integration risks and expected synergies, including practical valuation heuristics specific to essential oil assets.
-
Risk register and hedging playbook: scenario-based mitigation for crop failure, labor unrest, geopolitical exposure, and price spikes—complete with decision trees for when to shift from spot buying to multi-year contracts or equity partnerships.
-
Go-to-market implications: marketing stratagems and claims frameworks to translate traceability investments into consumer value while staying compliant with claims regulations across major geographies.
Note: To preserve the report’s commercial integrity and encourage full due diligence, we are intentionally omitting detailed split tables (regional, type, and application percentages) from this release. The full dataset and interactive dashboards are available through our report portal.
Competitive landscape — who matters and why
The rose oil value chain is a two-tier ecosystem: regionally anchored cultivators and distillers in source countries, and global fragrance/flavor houses and distributors that convert raw material into finished aromas and formulations. Our analysis profiles the strategic posture of leading participants and their implications for buyers in 2026.
-
Regional growers and distillers (Bulgaria-centric leadership): Several established Bulgarian distilleries combine field ownership or long-term grower relationships with extraction capabilities. Their competitive advantages include provenance and traceability from contiguous cultivation areas, control over agronomy and harvest timing, and the ability to certify organic and ethical attributes. These operators remain the primary gatekeepers of high-grade raw material during the short annual harvest window.
-
Global fragrance houses and ingredient suppliers: Major firms with global reach leverage industrial-scale sourcing, technical application support, and diversified product portfolios. Their strengths are contract coverage, formulation expertise, and buyer access, enabling them to smooth short-term supply shocks through inventory and blending strategies. Firms that announced sustainable sourcing strategies and acquisition plans are positioning to capture premium margins whether through proprietary blends or exclusive supply agreements.
-
Distributors and regional exporters: Players with strong documentation and quality-validation capabilities serve as commercial bridges between small distillers and global formulators. They are increasingly active in certification-enabled markets, offering traceability bundles that command pricing premiums with luxury and natural-focused brands.
Market concentration metrics indicate a moderately fragmented sector: the top three companies control roughly one-third of market share, while the top five account for just under half. This structure creates room for strategic consolidation, selective partnerships, and private-equity interest—opportunities we highlight for acquirers and potential divestors alike.
Recent industry movements shaping 2026 strategy
-
Strategic re-alignment: Global fragrance leaders have signalled increasing focus on sustainable, ethically sourced naturals as part of multi-year growth plans. These directional shifts mean buyers should expect competitive bidding for certified supplies and deeper commercial linkages that privilege long-term partners.
-
Certifications matter: Producers obtaining ethical sourcing certifications are already capturing contract advantages in premium segments. Certification is increasingly a non-negotiable commercial asset for access to certain customer channels.
-
Portfolio consolidation by distributors: Recent acquisitions in related essential-oil portfolios illustrate how distributors and traders are scaling to offer broader coverage and inventory depth—an important consideration for manufacturers seeking single-source procurement simplification.
-
Operational investments at source: Expandable distillation capacity and organic acreage investments by regionally-rooted operators point to an industry gradually professionalizing post-harvest management—reducing quality variance over time but not eliminating seasonal scarcity.
Raw material realities that will shape commercial outcomes
-
High input intensity: Rose oil extraction is resource and labor intensive—industry estimates indicate thousands of kilograms of petals are required to produce a single kilogram of essential oil. This underlying biology and labor need amplifies both unit cost and the potential for supply shocks.
-
Price volatility and premium signals: Market observers reported that organic Bulgarian rose oil reached historically high export price points in recent years, signalling how certification and scarcity can drive significant price differentiation. Buyers should be prepared for episodic price spikes tied to crop outcomes and certification premiums.
-
Geographic concentration: The supply base is dominated by a few traditional cultivation regions. This geographic concentration supports strong provenance narratives but also concentrates climate, labor, and regulatory risk.
-
Labor dynamics: A large seasonal workforce underpins the harvest window, and any changes in labor availability, wage levels, or regulation can materially affect yield, quality, and unit economics.
Direct implications for 2026 corporate decisions
-
Sourcing strategy: Prioritize multi-channel sourcing that mixes direct partnerships with regional distillers, validated distributors for short-term coverage, and contractual offtake agreements for high-purity requirements.
-
Certification and premiumization: Consider targeted investment in certification pathways for core SKUs where the brand value justifies the cost, and design SKU ladders to segregate premium-certified claims from mainstream formulations to optimize margin capture.
-
Risk management: Implement a three-tier risk mitigation approach—inventory buffers, flexible quality blending rules, and pre-negotiated escalation clauses for force majeure events tied to harvest outcomes.
-
M&A and partnerships: For companies seeking control of upstream economics, selective acquisitions or JVs with regionally established distillers offer immediate supply security and provenance control. For others, exclusive supply contracts with certification premiums will protect brand positioning without capital intensity.
-
R&D and formulation: Invest in lower-dose reformulations and aroma-modulation technologies to stretch scarce high-grade material across high-value SKUs, reducing exposure to raw-material cost swings.
How PW Consulting supports executive action
Our Essential Rose Oil Market Report is designed as an executive toolkit—not merely a descriptive study. Alongside the full dataset and dashboards, purchasers receive custom scenario workshops, supplier due-diligence templates, and a templated procurement playbook adaptable to different buyer risk appetites. We also provide a tailored M&A target memo on request, focusing on integration risks and synergies for critical upstream assets.
For procurement heads, R&D chiefs, and corporate development teams mapping 2026 priorities, the report condenses complex bio-economic realities into prioritized, actionable pathways. To review the full regional/type/application breakdowns, the detailed supplier matrix, and the interactive financial model, please consult the report portal linked in our release notice.
Contact
PW Consulting — Strategy & Industry Intelligence. For licensing, bespoke advisory, or to request the full dataset and scenario workshop, access the report page via our official portal or contact our client services team.
For detailed analysis of this topic, please visit the official page: Essential Rose Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com