

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Modular Steering Column Market to Reach USD 3,969.5 Million by 2032 on a 5.96% CAGR; Asia Pacific Leads with USD 1,188.32 Million in 2025

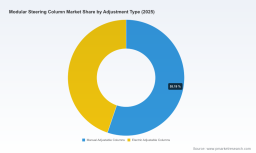
Modular Steering Column Market: A 2026 Strategic Playbook — PW Consulting Industry Brief
As automotive ecosystems accelerate through electrification, advanced driver assistance systems, and materials-driven lightweighting, the modular steering column has evolved from a mechanical commodity into a systems-level strategic asset. PW Consulting’s new Modular Steering Column Market report — synthesizing historical performance (2020–2025) and forward-looking projections (2026–2032) — equips C-suite leaders, procurement strategists, and product planning teams with the pragmatic intelligence needed to make high-stakes decisions in 2026. Our market model indicates the sector is on a steady expansion path with a compound annual growth rate of 5.96%, reinforcing that the segment offers both defensive resilience and targeted growth opportunities.
Modular Steering Column Market
Why this report matters to 2026 decision makers
- Timing for roadmap commitments: With product development cycles and supplier qualification windows increasingly compressed, 2026 is the last practical year for many OEMs and Tier‑1s to lock in modular steering column strategies aligned with 2028–2030 platform launches.
- Capital allocation clarity: A clear CAGR and multi-year market sizing allow finance and strategy teams to prioritize investments in electrified adjustment mechanisms, electronic locking modules, and material substitutions where payback curves are favorable.
- Regulatory and safety alignment: Compliance requirements (including energy-absorbing performance and functional safety for electronic modules) are shifting supplier evaluation criteria — making this report essential for risk‑adjusted procurement and engineering trade-off assessments.
Macro snapshot (methodology and headline figures)
Our analysis is built on audited historical data from 2020 through 2025 and generates a base-year market synthesis for 2025, with forecasts through 2032. All financials are presented in USD (Million). The headline: the global modular steering column market demonstrated consistent expansion through the base period and, under our central scenario, will sustain near‑term growth driven by increased adoption of configurable electronic adjustment systems, greater modularization across vehicle platforms, and OEM-led consolidation of supplier footprints. The market concentration profile is meaningful — the top three suppliers command a substantial share of the industry, while the top five collectively represent an even larger portion — creating both barriers and opportunities for challengers depending on capability differentiation.
Modular Steering Column Market
Key structural trends shaping the market
- Modularity as a platform lever: OEMs are treating the column as a cross-platform module to accelerate variant proliferation while containing complexity on wiring and seat-belt integrated systems.
- Electrified adjustment & integration: Electric tilt-telescope mechanisms and integrated column control modules are migrating from premium vehicles into mainstream segments, driven by user convenience expectations and packaging efficiency on electrified architectures.
- Safety and functional-safety convergence: Crash energy management requirements and ISO 26262 implications for electronic control units make column architecture decisions a combined mechanical-electronic-safety design challenge.
- Lightweighting pressure: Materials substitution (notably magnesium and aluminum alloys) and polymer-metal hybrids are increasingly specified to shave kerb weight and support EV range objectives.
- Supplier consolidation and specialization: Strategic M&A, platform bundling, and selective vertical integration are reshaping supplier roles — from component vendors to systems integrators.
Competitive landscape — what the leaders are doing and why it matters
Our competitive analysis profiles incumbent systems suppliers, their strategic positions, and the offensive/defensive plays that matter to buyers and investors.
Modular Steering Column Market
- Nexteer Automotive (Auburn Hills, MI): Nexteer is doubling down on modular EPS suites with scalable electric-assist column variants. Their recent introduction of a High-Output Column-Assist EPS demonstrates how suppliers can leverage modular commonality to serve both light vehicles and heavier applications — a model that shortens integration time for OEMs targeting multiple segments.
- thyssenkrupp AG (Essen, Germany): Known for adaptive crash behavior and differentiated load-path designs, thyssenkrupp positions modularity as a safety differentiator. For OEMs focused on higher mass-market and premium safety positioning, suppliers with proven crash performance adaptability remain essential partners.
- Kongsberg Automotive (Kongsberg, Norway): Their in-house end-to-end capability for tailored tilt-telescopic systems suits off-highway and commercial vehicle programs, where bespoke requirements and validation burdens favor suppliers able to deliver complete engineering throughput.
- Merit Automotive Electronics Systems (Spain/global): Merit’s focus on integrating convenience and security features within modular packages reduces wiring complexity and variant count — a compelling proposition for platforms seeking both cost and manufacturability benefits.
- NSK Ltd. (Tokyo): NSK’s use of engineered plastics for impact absorption and lightweighting highlights a materials-led route to compliance and performance, attractive for OEMs pursuing mass reduction without compromising crash behavior.
- Robert Bosch GmbH (Gerlingen): Bosch brings weight-saving material mixes and modular ergonomics tailored to commercial fleets, demonstrating how component-level innovation can unlock fleet economics through reduced fuel/energy consumption.
- ZF Friedrichshafen AG (Friedrichshafen): Through integrated control modules and a safety-heavy engineering pedigree, ZF’s approach exemplifies systems-level bundling that can simplify OEM software and diagnostics strategies.
- JTEKT Corporation (Osaka), Hyundai Mobis (Seoul), Mando Corporation (Seoul): These suppliers collectively reinforce the market’s balance between global scale and regional engineering strengths — each offering modular solutions within broader EPS/HPS ecosystems.
For procurement and R&D leaders, the implication is clear: supplier selection must be evaluated on an axis of modular commonality, functional-safety capability, materials roadmap, and integration into vehicle-level electrical/electronic architecture.
Regulatory, materials and engineering headwinds/opportunities
- Safety standards drive architecture choices: Long-established frontal crash requirements for energy absorption and controlled displacement remain non-negotiable design constraints. Suppliers that can validate predictable crush behavior while integrating electronic modules have a competitive edge.
- Functional safety for electronics: ISO 26262 compliance is a gating factor for electronic column control modules. Buyers should incorporate functional-safety maturity as a procurement KPI rather than an afterthought.
- Materials trade-offs: Magnesium and aluminum alloys offer attractive weight reductions and can substitute ferrous elements at favorable ratios, but material cost volatility and manufacturing readiness create trade-offs that must be quantified in total-cost-of-ownership models.
What’s inside the PW Consulting report — practical, decision‑ready deliverables
Built for actionable use in 2026 planning cycles, the report blends strategic intelligence with operational tools:
- Market model and scenario engine: A validated market-sizing baseline for 2025 and probabilistic forecasts through 2032 that allow users to test scenarios (e.g., accelerated EV adoption, materials price shocks, supplier consolidation).
- Supplier capability matrix: Comparative evaluation across modularity, crash performance, functional-safety maturity, global manufacturing footprint, and cost-to-serve considerations.
- Technology adoption roadmaps: Timing windows for electrified adjustments, electronic locking modules, and fully integrated column control units, mapped to typical OEM platform timelines.
- Procurement playbook: RFP templates, evaluation scorecards, and recommended contractual risk allocations for warranty, software integration, and performance validation.
- Investment and M&A signal map: Criteria to identify acquisition targets and partnership archetypes that accelerate capability acquisition or market entry.
- Case studies and engineering trade-offs: Example trade-off analyses demonstrating how materials substitution, modular commonality, and electronic integration affect mass, cost, and safety outcomes.
To preserve commercial sensitivity and adhere to the “preview” principle, the report summarizes high‑level findings and frameworks while reserving detailed segment-level figures, regional splits, and vendor-specific revenue estimates for subscribers and authorized purchasers.
How to use the intelligence in 2026 — three tactical recommendations
- Start supplier dual‑sourcing with modular alignment: Use the supplier capability matrix to identify a primary integrator and a secondary specialist. Focus the primary on platform commonality and the secondary on niche capabilities (e.g., high‑output column assist, heavy‑duty crash behavior).
- Embed functional safety early: Make ISO 26262 compliance and demonstrable safety-engineering artifacts mandatory in early RFP stages to avoid costly redesigns during validation.
- Run a materials volatility stress test: Quantify P&L sensitivity to magnesium/aluminum price swings and evaluate hedging or forward sourcing strategies for critical alloy inputs.
Concluding perspective
As vehicles become more software-defined and platforms proliferate across powertrain architectures, the modular steering column sits at an intersection of mechanical design, electronic control, materials engineering, and safety regulation. For executives mapping 2026 investment plans, the core question is not whether to engage with the modular column market, but how to architect supplier relationships, technology choices, and procurement processes to convert that engagement into a competitive advantage.
PW Consulting’s Modular Steering Column Market report provides the market-sizing, supplier intelligence, engineering trade-offs, and procurement playbooks required to make those decisions with confidence. For full access to the proprietary segmentation, regional breakdowns, and supplier revenue estimates that underpin our recommendations, please follow the link on PW Consulting’s official report page.
For detailed analysis of this topic, please visit the official page: Modular Steering Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com