

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts 4.2% CAGR for Global Latex Gloves Market Through 2032
By pmarketresearch, 2026-07-07
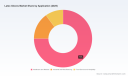
Latex Gloves Market 2026: Strategic Intelligence Briefing — PW Consulting
PW Consulting’s latest Latex Gloves Market report (base year 2025) delivers a targeted, decision-ready intelligence package for executives planning capital allocation, procurement strategy, product portfolio shifts, and M&A activity in 2026. This briefing highlights the report’s strategic value, summarizes high‑level market dynamics, and outlines immediate actions that senior leaders should prioritize—while reserving the detailed segment-level tables and company revenue breakdowns for the full report available on our site.
Latex Gloves Market
Market snapshot: where the market stands and where it’s headed
After a volatile 2020–2025 period, the latex gloves market is stabilizing into a modest growth trajectory. PW Consulting’s market model places the 2025 global market at approximately USD 9,500 Million (base year), with a forecasted reacceleration in 2026 and a compound annual growth rate (CAGR) of approximately 4.2% across the 2026–2032 forecast horizon. Under our central scenario the market expands to roughly USD 12,671 Million by 2032, driven by a mix of healthcare demand normalization, targeted industrial reuse, and differentiated product innovation.
Latex Gloves Market
The historical series captured in the report shows the pandemic-era inflection and subsequent correction that shaped supplier strategy, capacity utilization, and buyer behavior. That history is an input to the forward projections and to the scenario analyses we recommend companies use when stress‑testing 2026 investments.
Latex Gloves Market
Why this matters for 2026 decision-making
- Capex and capacity planning: Recent capacity announcements and the recovery dynamics exposed in our model indicate that greenfield and brownfield investments will be sensitive to natural rubber price volatility and lead times. The report provides a calibrated capex decision framework linking capacity ramp assumptions to price scenarios and utilization thresholds that justify new builds.
- Procurement and cost pass-through: Natural rubber latex remains a major cost driver. Our scenario work demonstrates how seasonal tapping disruptions and weather events can create sudden input cost shocks. The full report includes a cost‑pass‑through matrix and contracting playbook to protect margin under short and medium‑term price shocks.
- Regulatory compliance and supply continuity: Evolving regulatory timelines—most notably the postponement of enforcement for certain deforestation-related rules into late 2026—create both risk and runway for supply‑chain remediation. PW Consulting’s regulatory impact matrices map 510(k) requirements, ASTM/EN standards, and emerging labeling expectations to supplier readiness templates.
- Portfolio and product strategy: The continuing shift toward non‑latex alternatives in some end markets (driven by allergy concerns and policy actions) means that product differentiation, not just cost, will determine share gains. The report’s product/pricing elasticity analyses help teams prioritize which glove variants to scale and where to adopt accelerator‑free or synthetic-latex formulations.
Key market dynamics shaping 2026
- Raw material volatility: Natural rubber latex remains a volatile input—seasonal, weather‑sensitive, and influenced by regional production events. This volatility directly affects manufacturing margins and contract negotiation stances. Our report contains an actionable raw-material risk toolkit.
- Standards & regulatory pressure: Medical gloves are governed by medical device frameworks (e.g., US FDA pathways) and technical standards such as ASTM D3577/D3578 and EN 455. Labeling requirements for natural rubber latex and the regulatory cadence in key markets are modeled to show compliance timing and cost impacts.
- Demand substitution trends: The shift toward nitrile in certain healthcare and food service segments persists—driven by allergy prevalence and policy. PW Consulting’s demand mix scenarios quantify substitution potential and identify end-market pockets that will retain strong latex demand.
- Market concentration and competitive dynamics: The market shows measurable concentration at the top, with the leading manufacturers collectively holding significant share. Our competitive positioning maps and CRx context are designed to inform market entry, pricing, and partnership strategies.
Competitive landscape — what to watch in 2026
The market is competitive and innovation‑driven. Leading manufacturers and distributors are executing a range of tactics—from performance‑oriented product launches to capacity disclosures and distribution plays. Notable trends and company moves reviewed in the report include:
- Product innovation: Several incumbent manufacturers have introduced accelerator‑free, lightweight, and sulfur-free latex formulations designed to reduce allergy risk and improve comfort. These moves are designed to slow substitution to non‑latex alternatives and to retain clinical and specialist industrial uses.
- Supply-side scale and flexibility: Major producers have signaled or confirmed running capacities that position them to service both high‑volume commodity channels and higher‑margin specialty segments. Our supplier scorecards quantify operational flexibility, compliance posture, and cost structure differentials across the competitive set.
- Distributor and channel strategies: Global distributors and integrated healthcare suppliers continue to shape procurement dynamics in hospitals and clinics, where bundled purchasing and private‑labeling influence pricing and product mix.
For executives assessing partners or targets, the report includes qualitative profiles and strategic assessments of the principal players, evaluating production footprints, standard compliance, product portfolios, and strategic intent.
Practical contents of the full report (what you’ll get)
PW Consulting’s Latex Gloves Market report is structured for immediate operational use by C‑suite and commercial teams. The deliverables include:
- A transparent market model (2020–2032) with scenario toggles for raw material prices, substitution rates, and regulatory shocks.
- Demand drivers and end‑market diagnostics that prioritize geographies, channels, and applications for revenue ROI—presented as decision rules rather than raw subsegment tables in this briefing.
- Procurement playbook for latex sourcing: hedging approaches, contract templates, and supplier qualification checklists.
- Commercial playbook: go‑to‑market segmentation, pricing elasticity models, and product roadmap prioritization (including accelerator‑free and synthetic‑latex launches).
- Supplier scorecards and M&A screening matrices that identify scale players, niche innovators, and distressed or opportunistic targets.
- Regulatory impact matrices and compliance timelines, mapping 510(k), ASTM/EN standards, and EUDR implications by supply chain node.
- Executive dashboards and presentation‑ready slide decks tuned for board briefings and investment committees.
Strategic actions to prioritize in 2026
- Lock in flexible raw‑material arrangements: Negotiate contracts with indexed price floors/ceilings and multi‑source clauses to protect margins while preserving supply continuity.
- Segmented go‑to‑market: Differentiate product mixes across clinical, industrial, and foodservice channels—invest in accelerator‑free and synthetic-latex options where clinical comfort and allergy avoidance are mission‑critical.
- Invest selectively in automation and quality systems: Focus on inline quality testing and certifications that reduce audit friction in regulated markets and command premium pricing.
- Targeted M&A and partnerships: Use the report’s screening matrices to pursue bolt‑on capabilities—synthetic-latex R&D, regional distribution footprint, or certification labs—that accelerate time to market and de‑risk regulatory exposure.
- Scenario planning and stress tests: Run the report’s scenario tool across your P&L to identify trigger points for capacity rationalization, price adjustments, or temporary product pivots.
What we intentionally withhold in this briefing
In line with our “preview” approach, this release conveys high‑level market sizing, growth trajectory, concentration indicators, and strategic implications. To preserve the commercial utility of the analysis and to support client due diligence, detailed region‑by‑region, type‑by‑type, and application‑by‑application revenue splits and company-specific revenue breakdowns are available only in the full report and accompanying datasets. These withheld items include granular tables, downloadable model files, and deal‑ready scorecards that procurement and corporate development teams will find essential for executing 2026 initiatives.
Methodology & confidence
Our forecasts synthesize historical demand data (2020–2025), manufacturer disclosures, trade flows, standards timelines, and primary interviews with industry stakeholders. A probabilistic scenario framework drives the 2026–2032 outlook, with sensitivity bands around raw material inputs, substitution rates, and regulatory enforcement milestones. Market concentration metrics included in the report provide a view of competitive intensity and consolidation risk.
Next steps — how PW Consulting can help you execute
For manufacturing leaders, procurement heads, and corporate development teams preparing for fiscal 2026, PW Consulting offers tailored advisory support including model customization, supplier diligence engagements, and M&A advisory. If your 2026 plan requires validated scenarios, negotiations playbooks, or integration roadmaps, our team can deliver targeted modules from the full Latex Gloves Market report customized to your strategic priorities.
Access the full report and the associated data package on the PW Consulting website to retrieve the complete segment breakdowns, company profiles, downloadable market model, and executable playbooks that underpin these conclusions.
For detailed analysis of this topic, please visit the official page: Latex Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inline Viscometers Market to Reach USD 395.7 Million by 2032, Driven by Strong Asia-Pacific Gains
By pmarketresearch, 2026-07-07
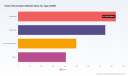
Inline Viscometers Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare capital allocation and product strategies for 2026, PW Consulting presents a focused preview of the Inline Viscometers Market landscape drawn from our forthcoming full report. The market has moved from a niche instrumentation category to an operationally critical component in continuous manufacturing and fluid process control. This briefing highlights the macro trajectory, competitive dynamics, regulatory context, and the practical decision levers that matter for executives, investors and product leaders — while reserving the granular segmentation tables and valuation models for the full report.
Inline Viscometers Market
Macro picture: growth, scale and what it means for 2026 planning
Across our base and forecast horizons, the inline viscometers market demonstrates steady, commercially meaningful expansion. From a 2025 base year value of approximately USD 248.5 Million, the market is projected to register a compound annual growth rate (CAGR) of 6.85% over the 2026–2032 forecast window, reaching roughly USD 395.7 Million by 2032. The immediate next step in 2026 sees an uplift to an estimated USD 277.4 Million.
Inline Viscometers Market
Why these macro numbers matter for 2026 decisions:
Inline Viscometers Market
- Budgeting and capacity: a mid-single-digit-plus CAGR signals that incremental capacity investments can be recovered within typical industrial equipment depreciation cycles, especially when paired with recurring service revenues.
- Product roadmaps: consistent market expansion justifies multi-year R&D roadmaps focused on sensor integration, reliability improvements and software-enabled analytics rather than one-off product launches.
- M&A and partnerships: growth combined with moderate market concentration creates windows for bolt-on acquisitions and strategic alliances to accelerate route-to-market or add complementary technology stacks.
Key demand drivers shaping 2026 procurement
Our review of the dynamics affecting buyer behavior identifies four persistent themes that will determine procurement priorities next year:
- Continuous processing adoption: As manufacturers across chemicals, food & beverage, pharmaceuticals and coatings continue shifting from batch to continuous operations, inline viscosity measurement becomes a non-negotiable element of process control strategies.
- Digitalization and data-led operations: Customers want viscometers not as standalone instruments but as nodes in an IIoT architecture, delivering time-series viscosity data, health diagnostics and closed-loop control capabilities.
- Operational resilience and uptime: Instruments that reduce manual sampling and support predictive maintenance deliver both safety and OEE (overall equipment effectiveness) benefits that are easily quantified in investment cases.
- Standards and compliance: ISO 3219:2021 continues to frame expectations for rotational viscometer methods. Suppliers who demonstrate alignment with prevailing standards reduce adoption friction, particularly in regulated industries.
Technology trajectories and product strategy implications
The category comprises multiple sensing approaches — vibrational/resonant, rotational and hybrid integrations with established flow and density technologies. Each approach presents trade-offs between measurement range, sensitivity, installation complexity and integration cost.
- Resonant/vibrational sensors: excel in inline, real-time measurement with high repeatability and compact footprints — attractive for retrofit and continuous-process scenarios.
- Rotational approaches: remain relevant where established laboratory-to-line equivalency is required and where compliance with legacy test methods matters.
- Integrated solutions: vendors integrating viscosity sensing with Coriolis or density meters offer differentiated value by combining mass flow and rheological insights for advanced process control.
For R&D and product leaders planning 2026 investments, the strategic calculus is threefold: prioritize modularity to support multiple installation profiles, embed secure connectivity and edge analytics, and design service contracts that monetize calibration, diagnostics and data services.
Competitive landscape: what the market structure tells us
Our competitive review emphasizes five incumbent and emerging suppliers that illustrate distinct strategic approaches and execution models:
- AMETEK Brookfield (USA) — Known for inline viscosity sensors tailored to continuous monitoring in food, chemical and pharmaceutical contexts. Their strength lies in application depth and service capability across process industries.
- Anton Paar GmbH (Austria) — Provides inline viscometers and process sensors optimized for real-time production line integration. Anton Paar leverages high-precision metrology and strong OEM relationships.
- Rheonics AG (Switzerland) — Specializes in resonant sensor technology, pairing inline viscosity and density measurement for sectors such as oil & gas, coatings and food. Their product strategy emphasizes compact, high-frequency sensing and clean integration into process control systems.
- Emerson Electric Co. (USA) — Positions inline viscosity measurement within broader process instrumentation portfolios, often integrating viscosity measurement with Coriolis flow metering to deliver combined mass-flow and rheological data streams.
- KROHNE Messtechnik GmbH (Germany) — Offers robust inline viscometers for chemical, petrochemical and food applications, with a focus on reliable field performance and global service networks.
Market concentration metrics indicate a competitive but consolidating landscape: the top three players account for a meaningful share of the market while the top five broaden that concentration further. This structure creates both opportunities for innovative challengers to capture niche pockets and incentives for incumbents to pursue M&A that complements organic growth.
Risks and scenario sensitivities for 2026
When using our projections to shape 2026 strategy, executives should stress-test plans against three risk vectors:
- Supply-chain volatility: component shortages and lead-time variability can compress gross margins on hardware-centric offerings; mitigation includes dual-sourcing critical components and designing for component flexibility.
- Regulatory shifts and standard harmonization: evolving metrology standards or industry-specific regulatory updates could alter validation requirements; proactive engagement with standards bodies and transparent conformance documentation reduce market friction.
- Substitution and integration risks: parallel technologies (e.g., advanced spectroscopic sensors or AI-enabled inferential models) may change value perceptions; incumbents should emphasize validated accuracy, interoperability and the cost of switching in buyer economics.
Practical playbook for 2026 — six action items
Executives should translate the trends above into concrete actions in 2026. PW Consulting recommends the following prioritized playbook:
- Re-center product roadmaps around modular, connected sensor platforms that support edge analytics and secure cloud telemetry — this unlocks recurring service revenues and enables outcome-based pricing.
- Forge OEM and system integrator partnerships to embed viscometers early in process architectures rather than selling as aftermarket add-ons.
- Invest selectively in resonant sensor innovations and combined-parameter instruments (viscosity + density or flow) to capture higher-value integration pockets.
- Create clear compliance packages aligned with ISO 3219:2021 and industry-specific validation protocols to accelerate adoption in regulated segments.
- Develop a disciplined M&A playbook: target tuck-ins that add data analytics, field service networks or niche process application expertise; use financial models that account for service lifetime value.
- Operationalize risk management: shorten lead-time exposure, expand local calibration capabilities, and introduce flexible pricing to buffer order volatility.
What PW Consulting’s full report delivers
This preview distills strategic high points; the comprehensive PW Consulting Inline Viscometers Market report provides the operational level detail organizations need to execute in 2026, including:
- Multi-scenario financial models and a 2026–2032 forecast with embedded sensitivity testing (base, upside, downside).
- Vendor benchmarking and a decision matrix covering technology fit, integration effort, aftermarket service capability and go-to-market reach.
- Buyer procurement playbooks and sample ROI calculators for CAPEX vs. OPEX trade-offs under different production profiles.
- Regulatory alignment guides and a compliance checklist keyed to recognized standards such as ISO 3219:2021.
- Action-oriented M&A due-diligence templates and integration scorecards tailored for instruments and software acquisitions.
To adhere to the “trailer” principle, we are deliberately reserving detailed segment-level splits and the vendor-level revenue tables for the full report and the subscriber portal. Those datasets are the most operationally sensitive inputs for market entry, pricing and M&A execution and are available with the complete deliverable.
Conclusion: positioning for advantage in 2026
For 2026, the inline viscometers market represents an intersection of steady top-line growth, accelerating digital expectations and selective consolidation. Companies that align product architecture to system-level needs, secure standards conformance, and monetize lifecycle services will convert market growth into sustainable margin expansion. Conversely, firms that treat viscometers as commodity hardware risk margin compression and slower adoption.
PW Consulting’s full report converts the market’s macro trajectory — anchored by a 2025 base of approximately USD 248.5 Million and a 6.85% CAGR — into executable decisions, financial models and partnership strategies. For teams preparing budgets, product roadmaps or M&A pipelines for 2026, the comprehensive datasheets, vendor scorecards and scenario models in the complete report are essential tools.
Next steps
Access the full Inline Viscometers Market report for the granular datasets, regional and application segmentation, vendor revenue figures, and downloadable financial models. PW Consulting subscribers and enterprise clients can also commission tailored briefings and scenario workshops to stress-test 2026 plans against market realities.
For detailed analysis of this topic, please visit the official page: Inline Viscometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold Roof Coating Market Poised to Reach USD 8.61 Billion by 2032, Growing at a 7.15% CAGR
By pmarketresearch, 2026-07-07
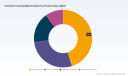
Cold Roof Coating Market Outlook 2026: Strategy Briefing from PW Consulting
PW Consulting today publishes an executive briefing drawn from our forthcoming Cold Roof Coating Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The market for cold (reflective) roof coatings is on a sustained growth path — our model pegs a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast window. In monetary terms, the market expands from roughly USD 5.3 billion in 2025 to an anticipated USD 8.6 billion by 2032 (USD, revenue unit: Million).
Cold Roof Coating Market
Why this matters for 2026 decision-makers
- Policy and procurement timelines are converging. Building codes, municipal heat-island mitigation programs, and corporate net-zero commitments are moving from guidance to procurement criteria. Products that are CRRC-rated and demonstrate lifecycle energy savings are increasingly prerequisites for large public and private contracts.
- Standards and testing have become a practical constraint and opportunity. ANSI/CRRC S100-2025 introduced revised protocols for liquid-applied coatings and polymer/composite materials that materially affect how products are validated. The standard update, and CRRC’s move to accredit independent international testing labs, changes time-to-market and compliance cost calculations.
- Margins are under pressure from raw material volatility. Resin feedstocks, titanium dioxide pigments, and specialty additives experience price swings that flow directly into production cost models. At the same time, higher-value chemistries such as silicone formulations command meaningful price premiums due to longer service life and reduced maintenance cycles.
- Commercial product strategies are being reshaped by warranty and performance programs. Recent industry actions—ranging from extended warranty programs to CRRC-listings and Title 24 compliance claims—shift value toward manufacturers that can pair validated performance with strong installer networks and risk-sharing warranties.
What PW Consulting’s report delivers (practical, operational, decision-ready)
Our full Cold Roof Coating Market report is explicitly designed as a playbook for 2026 planning cycles. It blends market-level sizing with actionable modules that procurement, product, and corporate strategy teams can use immediately. Highlights include:
Cold Roof Coating Market
- Forward-looking market size and revenue models (2026–2032) with scenario analysis under alternative regulatory and raw material cost paths.
- Unit-cost and margin models for the principal technology classes, enabling SKU-level pricing stress tests and profitability sensitivity runs.
- A compliance and specification matrix tied to ANSI/CRRC S100-2025 and common regional building-code requirements, with recommended test pathways to optimize time-to-certification.
- Go-to-market playbooks for new entrants and incumbents: distribution channel mapping, installer certification programs, specification-sales frameworks, and warranty design options.
- Supplier and raw-material risk heatmaps plus mitigation steps (hedging approaches, alternative chemistries, strategic sourcing buffers).
- Commercial tools for end-users: lifecycle cost comparison templates, HVAC load reduction calculators, and retrofit vs. replacement decision flows.
- M&A and partnership scouting: candidate profiles, valuation heuristics, and integration playbooks focused on technology, channel reach, and testing/certification assets.
To preserve competitive advantage for subscribers, the report deliberately withholds granular split tables in this public briefing. The full dataset, including downloadable models and transaction-ready slides, is available through the PW Consulting report portal.
Cold Roof Coating Market
Market structure and competitive dynamics — what to expect in 2026
The cold roof coating market exhibits moderate concentration. The top three global players represent roughly one-third of market revenue, and the top five approach the mid‑40s percentage share — a structure that allows both scale-driven firms and regional specialists to coexist. Competitive advantage is driven by a combination of validated performance (CRRC, ASTM), channel control (distribution + contractor networks), and technical differentiation (polymer chemistry, ceramic additives, UV-stable pigments).
- Scale and specification leadership: Established coatings multinationals with broad architectural and industrial portfolios are leveraging global labs, long-standing customer relationships, and deep distribution to defend large accounts. These firms invest in formulation R&D and program-level warranty support to command specification lists for commercial projects.
- Technical differentiation: Players focused on higher-margin chemistries (e.g., silicone systems, proprietary ceramic dispersions, insulative nanomaterials) compete on lifecycle cost and reduced maintenance frequency rather than entry price.
- Restoration and service-first providers: Brands offering system-level solutions (liquid-applied membranes, fiber reinforcement, integrated waterproofing) tie coatings to broader roof-restoration value propositions, enabling long-term service contracts and installer exclusives.
- Specialists and regional champions: Local manufacturers and niche innovators use code and incentive familiarity plus installer networks to defend regional volumes—particularly where procurement favors local-sourcing or compliance with specific jurisdictional standards.
Notable company positioning and recent moves
Key incumbents and innovators are setting the pace in different dimensions:
- Sherwin-Williams — Leverages pigment and formulation depth to serve commercial and industrial systems with infrared-reflective pigments and integrated application systems.
- PPG Industries — Competes on high-reflectivity formulations and global architectural reach; positions high-SRI products for large-scale deployments.
- AkzoNobel — Focused on elastomeric, durable roof coatings targeted at weather resistance and long-term performance in commercial roofing.
- RPM (Tremco) — Packages liquid-applied coatings within roof-restoration systems and installer-backed warranty offerings.
- BASF & Dow — Play the materials-infrastructure role: dispersions, elastomers, and digital tools (e.g., energy-savings calculators) that support specification and OEM formulation strategies.
- Sika, GAF, Henry (Carlisle) and others — Combine waterproofing systems or high-stability pigments with installer networks and product warranties to secure large project pipelines.
- Specialists (NanoTech Materials, Castagra, Neogard/Hempel) — Differentiate through ceramic/nano additives, VOC-free formulations, and CRRC/Title-compliant product launches. Recent examples include new eco-friendly fiber-reinforced product rollouts and extended warranty programs that aim to convert retrofit markets.
Recent industry milestones — such as CRRC’s 2025 standard updates and its accreditation of independent international test labs — materially change compliance timelines and elevate the strategic value of in-house or partner lab capacity. Separately, product launches and warranty programs announced in 2024–2026 illustrate the dual front of technology and commercial risk-transfer initiatives shaping buyer decisions.
Risks, catalysts, and near-term watch items
- Raw material price volatility: Acrylic and silicone resin feedstocks, pigment availability and specialty additives will influence margins and could compress low-margin segments unless pass-through mechanisms or hedges are in place.
- Regulatory and standards shifts: Additional CRRC refinements or regional code updates could accelerate demand but raise near-term certification cost and time-to-specification.
- Installer capacity and labor dynamics: High-quality application is a gating factor for warranty-backed products; installer certification programs and labor availability will be central to scaling advanced solutions.
- Technology substitutions: Proprietary ceramic blends, nanomaterials, and hybrid systems could reprice the performance-per-dollar equation and create new premium tiers.
- Green procurement incentives: Municipal and corporate incentive programs tied to SRI/reflectance metrics will be accelerants for adoption in retrofit markets.
How companies should act in 2026
- Manufacturers: Prioritize CRRC testing pathways, align SKU mix to risk-adjusted margin models, and build installer certification ecosystems tied to warranty products.
- Distributors / installers: Differentiate via integrated specification support, performance documentation, and managed-service agreements that reduce owner perceived risk.
- Building owners / facility managers: Use lifecycle cost tools to evaluate payback; demand certified performance claims and warranty alignment with expected service intervals.
- Private equity / investors: Focus diligence on asset-light platform plays that can scale installer networks or on technology plays that deliver genuine lifecycle delta versus commodity acrylics.
- Policymakers and utilities: Structure incentives around demonstrated energy savings and long-run maintenance reductions to maximize public benefit.
Next steps and how to get the full intelligence
This briefing is intended to frame the strategic choices and operational levers that PW Consulting’s Cold Roof Coating Market report covers in depth. Our work combines granular forecasting, SKU-level margin modeling, compliance playbooks, supplier risk matrices, and M&A-ready diligence packages. For teams preparing 2026 budgets, R&D roadmaps, procurement specifications, or transaction screening — the full dataset and executable templates are available through the PW Consulting report portal.
Contact PW Consulting for access to the report, companion models, and a briefing session tailored to your organization’s role in the cold roof coatings value chain.
For detailed analysis of this topic, please visit the official page: Cold Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyelectrolyte Market to Reach USD 4,952.42 Million by 2032 at a 5.31% CAGR, Led by Asia Pacific's USD 1,380 Million Share
By pmarketresearch, 2026-07-07
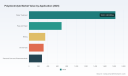
Polyelectrolyte Market Outlook 2026: Strategic Signals for Executive Decision-Making
Executive summary
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a concise preview of our latest Polyelectrolyte Market report (base year 2025). The global polyelectrolyte market is on a steady growth trajectory with a compound annual growth rate (CAGR) of 5.31% through the 2026–2032 forecast window. Our modelling shows the market expanding from an estimated USD 3,450 Million in 2025 to approximately USD 4,952 Million by 2032, with the next twelve months representing a pivotal planning horizon for procurement, capacity investment, and portfolio restructuring.
Polyelectrolyte Market
This communication follows a ‘trailer’ principle: it surfaces the analytical architecture, strategic implications, and actionable frameworks contained in the full report while intentionally withholding the granular segment-level tables and proprietary split data that executive teams rely upon for transaction- and bid-level decisions. Those detailed exhibits and scenario worksheets are available in the full report on our website or through a direct client briefing.
Polyelectrolyte Market
Why 2026 is a strategic inflection point
-
Consolidation meets regulation: The market’s top-tier concentration metrics—CR3 ≈ 34.8% and CR5 ≈ 47.5%—indicate a competitive environment in which a small group of global and regional players influence pricing, technology diffusion, and supply reliability. For buyers and investors, 2026 is the first full planning year in which the interplay of consolidation and tighter environmental standards will materially affect contract structures and CAPEX timing.
Polyelectrolyte Market -
Supply chain and input-cost volatility: Polyacrylamide and acrylamide-input dynamics have shown regional divergence through 2025. Notably, China’s domestic polyacrylamide pricing softened across the year, while Northeast Asia and Europe displayed modest upward pressure in late 2025. Acrylamide production remains linked to petroleum-derived feedstocks, keeping polymer producers exposed to crude-price and logistics volatility—an exposure that will shape hedging and sourcing strategies in 2026.
-
Policy-driven demand acceleration: Stricter wastewater discharge and chemical-safety regulations are accelerating upgrades in municipal and industrial treatment plants. That regulatory push is lifting demand for higher-performance polyelectrolytes and creating windows for product substitution and premiumization—opportunities that are measurable at the product-line and customer-segment level in our full analysis.
Key market dynamics that will drive decisions in 2026
-
Volume growth with selective premiumization. Our topline forecast (2026 base-up projection) anticipates both steady volume expansion and pockets of above-market-value demand where treatment specifications and environmental enforcement require specialty chemistries. Procurement teams should expect a mix of commoditized buying behavior for bulk grades and value-based negotiations where performance and compliance matter.
-
Regional cost arbitrage and localization pressure. Variances in regional feedstock prices and energy inputs continue to produce cost differentials. Manufacturers are responding with localized capacity builds and contract diversification; buyers should plan multi-sourcing strategies and conditional bilateral agreements to mitigate single-source exposure.
-
Technology and formulation as differentiation levers. R&D investment is focusing on higher molecular-weight polymers, tailored charge densities, and formulations that reduce sludge volumes or improve dewaterability. These technical attributes create clear procurement evaluation criteria beyond price—criteria we quantify and prioritise in our supplier scorecards.
-
Environmental and health compliance shaping product choice. Regulatory frameworks are tightening across wastewater discharge and chemical handling. As a result, lifecycle assessments, disclosure of residual monomers, and product stewardship are becoming procurement-filtering conditions rather than optional value-adds.
Competitive landscape — what corporate strategists need to know
The competitive map combines global leaders, regional champions, and capacity-intense producers from Asia. Major multinational players maintain integrated product portfolios and extensive manufacturing footprints, enabling them to defend premium segments and large municipal contracts. Regional producers, particularly in Asia, are scaling rapidly with high-volume production capabilities and cost-competitive offerings focused on industrial flocculation and mining applications.
-
Global integrated suppliers: Companies with multi-site manufacturing and established brand portfolios (water-focused product lines and paper-chemicals heritage) will continue to leverage scale, applied R&D, and service models to capture municipal and industrial megaprojects.
-
Emerging high-volume manufacturers: Several large-capacity producers from Asia pursue aggressive local and export growth, using cost advantage and production scale to contest commoditized segments—an important consideration for price-sensitive buyers and OEM partners.
-
Specialty and service-oriented players: Firms that bundle chemical supply with engineering, monitoring, and plant-optimization services are winning share in high-complexity contracts where performance guarantees and OPEX reduction are central contract features.
Our competitive profiles in the full report include manufacturing footprints, product portfolios, strategic moves (capacity additions, partnerships), and supplier strength matrices. Executive summaries for each major supplier are provided to help buyers shortlist partners by capability and risk tolerance—information we do not publish in full within this press release to preserve client exclusivity.
Actionable frameworks included in the report
This study is built to be operationally useful for 2026 planning cycles. The full deliverable contains:
-
Scenario-based demand models (short, medium, long) calibrated to macroeconomic outlooks and regulatory intensity, enabling rapid sensitivity testing for CAPEX and procurement budgets.
-
Supplier scorecards and a procurement playbook that translate performance attributes (molecular weight, charge density, residual monomer levels) into negotiation levers and service level KPIs.
-
Supply-chain risk heatmaps and mitigation options, including dual-sourcing templates, stock-sizing heuristics, and contract clauses for feedstock pass-throughs.
-
Unit-cost models and margin buckets for producers—useful for private-equity diligence and for strategists assessing the economics of vertical integration or toll-manufacturing partnerships.
-
Regulatory scenario matrices (compliance pathways) showing where substitution premium opportunities will emerge under varying enforcement regimes.
-
Deal origination lists and M&A screening criteria focused on bolt-on targets and capacity plays that align with regional demand growth and product-mix optimization.
Strategic implications by function (what each executive should prioritize)
-
Procurement: Move from purely price-based sourcing to a hybrid model that prices in service, technical support, and compliance risks. Use our supplier scorecards to re-bid material contracts with conditional performance payments tied to dewatering or polymer-efficiency metrics.
-
Operations & manufacturing: Reassess production footprints versus feedstock exposure. Where upstream acrylamide dependence creates volatility, consider tolling arrangements or incremental on-site monomer storage as hedges.
-
R&D & product: Prioritize formulations that reduce sludge volume and energy intensity—these attributes will be monetizable through performance contracts and are increasingly demanded by municipal buyers.
-
Corporate development & investment: Target acquisition candidates that add technical depth or localized capacity in markets where trade barriers and logistics costs blunt export economics.
-
Risk & compliance: Integrate lifecycle assessments and residual-monomer disclosure into supplier selection criteria. Prepare for incremental compliance costs by modeling them into 2026 procurement cycles.
How to use this report in your 2026 planning
The primary value of our report is practical integration: marrying market forecasts (historical 2020–2025 base and forecast 2026–2032) with executable procurement and investment playbooks. For CFOs, the topline growth and concentration metrics provide a basis for scenario budgeting. For procurement heads, our negotiation templates and supplier heatmaps shorten sourcing cycles. For M&A teams, the deal pipeline and valuation sensitivity tables accelerate target screening and transaction structuring.
We emphasize that while this press release highlights thematic drivers and top-level forecasts—total market estimates and aggregate growth rates—the detailed regional, type, and application split tables that underpin contract-level decisions are available only in the full report and through PW Consulting client briefings. That granular intelligence is where actionable savings and strategic advantage are crystallized.
Closing and next steps
Polyelectrolytes remain a mission-critical input across water treatment, pulp & paper, mining, oil & gas, and specialty applications. The market’s steady CAGR of 5.31% combined with regulatory uplift and regional cost differentials creates a landscape where timely strategic choices in 2026 can materially improve commercial outcomes.
To access the full dataset, supplier matrices, and scenario tools that support near-term decisions, visit the PW Consulting report page or contact our industry desk to schedule a tailored briefing. Our full report equips executive teams to convert macro signals into procurement savings, defensible CAPEX choices, and prioritized M&A roadmaps—without the noise.
For detailed analysis of this topic, please visit the official page: Polyelectrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Pancreatic Enzymes & Supplements Market to Reach USD 4,869.65 Million by 2032, Expanding at a 7.24% CAGR
By pmarketresearch, 2026-07-07
Pancreatic Enzymes and Supplements Market 2026: Strategic Imperatives for Life Sciences Leaders
PW Consulting’s latest market intelligence — the Pancreatic Enzymes And Supplements Market report (base year 2025, forecast 2026–2032) — frames an industry at an inflection point. After a period of steady expansion through the first half of the decade, the global market surpassed USD 2.98 billion (2025, USD Million) and is projected to continue growing at a compound annual growth rate of 7.24% across our 2026–2032 forecast horizon. By 2032, our model projects a multi-billion-dollar opportunity underpinned by persistent clinical need, constrained raw-material supply, and concentrated commercial leadership. For executives planning resource allocation, M&A, manufacturing investments, or market-entry strategies in 2026, the implications are immediate: act with precision, prioritize supply resilience, and build evidence that secures formulary and payer access.
Pancreatic Enzymes And Supplements Market
Why 2026 Is a Strategic Pivot Year
Several structural features of the pancreatic enzyme ecosystem raise urgency for strategic decisions in 2026. First, the category is clinically essential for patients with exocrine pancreatic insufficiency (EPI) arising from cystic fibrosis, chronic pancreatitis, pancreatectomy and other etiologies. That clinical imperative sustains demand even when pricing and reimbursement pressures mount.
Pancreatic Enzymes And Supplements Market
Second, the category’s supply architecture remains tightly coupled to animal-derived pancreatin and pancrelipase APIs. Manufacturing complexity, source concentration, and periodic capacity limitations have created regional availability disruptions in recent years, and our risk-mapping indicates these constraints will continue to influence commercial performance and patient access into 2026 and beyond.
Pancreatic Enzymes And Supplements Market
Third, market concentration is high: PW Consulting’s competitive analysis shows a compact set of branded prescription PERT players and a handful of API producers that together exert outsized influence on supply, pricing, and innovation pathways. This concentration creates both strategic barrier and tactical opportunities for entrants and incumbents alike.
What the Report Delivers — Practical, Actionable Outputs
- Robust market sizing and a granular forecast model for 2026–2032, including scenario analyses that stress-test demand under supply disruption, payer tightening, and alternative therapy adoption scenarios.
- Clinical and regulatory landscape mapping that synthesizes FDA precedent, prescribing information updates, and the post-2000s NDA environment that governs current PERT approvals — essential reading for regulatory and clinical affairs teams.
- Supply-chain deep dives covering API sourcing, critical-path manufacturing steps, and an independent assessment of global capacity bottlenecks — enabling procurement and operations teams to build mitigation strategies.
- Commercial playbooks for formulary positioning, payer engagement, and patient-assistance design that balance access with sustainable revenue management.
- Competitor intelligence dossiers with product profiles, recent regulatory and commercial developments, and tactical recommendations for partnership, licensing, or targeted M&A.
- Risk and quality matrices aligned to GMP and regulatory expectations, plus a remediation checklist for contract manufacturers and API suppliers.
We designed the report to be a “doer’s manual” for 2026: executives will find the not only the what and the why, but also the how — from drafting an alternative API sourcing strategy to structuring value-based agreements with payers. Note: in line with our “trailer” principle we surface strategic direction and insights in this release but withhold the full proprietary segment tables and granular regional/application splits to drive subscription access to the full dataset.
Competitive Landscape: Who Matters and Why
The market is dominated by established prescription PERT brands and a small set of specialized API manufacturers. Leading commercial PERT brands — marketed by global pharmaceutical firms and specialty players — remain central to treatment patterns for EPI. At the same time, specialist API producers supply the bio-derived pancreatin and pancrelipase that current formulations require.
- AbbVie Inc. — Markets Creon, the most widely used delayed-release pancrelipase capsule for a range of EPI indications. AbbVie’s scale and channel reach make Creon a commercial fulcrum for many healthcare systems.
- VIVUS LLC — Markets Pancreaze and has recently expanded copay support programs that materially affect patient out-of-pocket costs and brand retention among commercially insured populations (copay assistance program expanded in February 2026).
- Digestive Care, Inc. — Markets Pertzye, notable for its bicarbonate-buffered enteric-coated microsphere formulation variant; a differentiated product profile that influences therapy choice for select prescribers.
- Aimmune Therapeutics, Inc. — Markets Zenpep and Viokace, offering both enteric-coated and non-enteric formulations used in conjunction with proton-pump inhibitors in adults, reflecting strategic product diversity within the PERT class.
- Specialist API manufacturers — Companies such as Nordmark Pharma, Shenzhen Hepalink, and Scientific Protein Laboratories manufacture pancreatin/pancrelipase APIs extracted from porcine sources and therefore sit at the center of supply-chain risk and quality assurance conversations.
Recent developments highlight the interplay between quality, regulation, and commercial access. Notably, an FDA warning letter issued in October 2025 to a pancreatin API manufacturer underscores the operational and compliance risks embedded in biological sourcing and processing. Simultaneously, multiple prescription product labeling updates during 2024–2025 and aggressive patient support programs from certain brands continue to reshape market dynamics.
Strategic Implications — What Leaders Must Do in 2026
PW Consulting recommends a prioritized set of strategic actions tailored for three cohort types: incumbent brand holders, API suppliers/CMOs, and new entrants (including consumer-focused OTC supplement players):
- For incumbents: Fortify supply resilience. Establish dual-sourcing arrangements for API, invest in quality-capacity upgrades for owned or contracted manufacturing, and develop contingency allocation protocols to maintain continuity for high-risk patient groups.
- For API producers and CMOs: Proactively invest in regulatory remediation and transparency. The FDA’s heightened scrutiny on biologically derived APIs means quality and documentation now directly influence commercial negotiation strength with formulary committees and brand owners.
- For new entrants and OTC players: Differentiate via evidence. With prescription brands entrenched and no approved generics in the current landscape, OTC offerings must either pursue clear clinical positioning for adjunctive uses or invest in real-world evidence to support claims and channel acceptance.
- Across all players: Re-examine commercial models to balance access and margin. Copay assistance programs are effective short-term patient-access levers but can obscure long-term payer negotiation needs; structured value-based outcomes agreements and indication-specific pricing should be explored where feasible.
Risk Management and Regulatory Readiness
Key 2026 risk vectors include API supply shocks, regulatory enforcement actions, and payer-driven formulary consolidation. Our report’s risk workbook quantifies these scenarios and provides mitigation pathways: manufacturing harmonization checklists, audit-ready documentation templates, and strategic supplier scorecards. Firms that preemptively align quality systems to the stricter end of FDA and global GMP expectations will gain commercial advantage in contracting and tender processes.
Where to Focus Investment and Partnership Capital
Investment and partnership theses that emerge from our analysis are pragmatic and prioritized for near-term ROI:
- Targeted capacity investments that reduce lead times for capsule filling and pouching, rather than speculative expansion of API extraction capacity alone.
- JV or off-take agreements with trusted API producers that include explicit quality KPIs and penalty/relief clauses tied to supply continuity.
- Clinical and HEOR investments demonstrating outcomes and cost-offsets, which materially influence formulary placement and payer negotiations.
- Manufacturing modernization initiatives (automation, contamination control) that materially reduce the risk of regulatory actions and product recalls.
Executive Takeaway
PW Consulting’s analysis concludes that the pancreatic enzymes and supplements market will remain financially attractive through 2032, driven by clinical necessity and disciplined brand economics. However, the pathway to capturing value in 2026 is narrow and operationally intensive: companies must manage supply chains, shore up regulatory compliance, and craft payer-facing value propositions that withstand scrutiny. With CR3 concentration levels indicating that a small number of players command the lion’s share of commercial influence, strategic moves such as alliance formation, selective vertical integration, and targeted HEOR investment will determine who leads the next phase of growth.
Accessing the Full Intelligence
This release highlights the strategic framing and practical implications uncovered in our Pancreatic Enzymes And Supplements Market report. To protect the integrity of our proprietary models and the tactical insight that informs executable decisions, we intentionally limit detailed regional and application-level splits in this summary. Subscribers and corporate clients can access the complete dataset — including scenario-modeled segment tables, supplier maps, and executable playbooks — through PW Consulting’s report portal. For a consultation to translate these findings into a 90–180 day operational plan, contact our advisory team directly.
PW Consulting — translating market intelligence into decisive strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pancreatic Enzymes And Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 25G Optical Chip Market Set to Reach USD 2.9 Billion by 2032, Expanding at a 7.5% CAGR
By pmarketresearch, 2026-07-07
PW Consulting Strategic Brief: 25G Optical Chip Market — What Every Executive Must Know Heading into 2026
As demand for higher bandwidth and lower latency accelerates across cloud, carrier and edge networks, 25G optical chipsets have moved from a tactical upgrade to a strategic infrastructure decision. PW Consulting’s latest market study (base year 2025; historical series 2020–2025; forecast 2026–2032) provides executives with the foresight and practical toolset needed to make high-stakes procurement, investment and partnership decisions in 2026. The global 25G optical chip market, having grown from roughly 1,225 Million USD in 2020 to 1,750 Million USD in 2025, is projected to expand at a compound annual growth rate (CAGR) of 7.5% over the 2026–2032 forecast window, reaching approximately 2,903 Million USD by 2032.
25G Optical Chip Market
Why 25G Is a Strategic Inflection Point in 2026
-
Cost-per-bit economics: As hyperscalers and carriers balance capex and operational power budgets, 25G solutions offer an attractive inflection between legacy 10G links and emerging 50/100G architectures. The near-term optimization of link speeds, power envelope and module complexity is now central to network architecture decisions.
25G Optical Chip Market -
Demand tailwinds from cloud and 5G: Continued densification of data center fabrics and 5G fronthaul/midhaul upgrades underpin steady demand growth, while new enterprise and industrial optical use cases are expanding non-traditional adoption vectors.
25G Optical Chip Market -
Supply-side constraints and bottlenecks: Our sector supply-chain workstream finds leading producers of critical 25G laser technologies (EML/CW) operating near full utilization, with backlogs extending beyond two years at top suppliers. Alongside this, precision optical subcomponents and advanced packaging—areas concentrated in a few geographies—represent persistent bottlenecks that materially influence time-to-market and margin realization.
-
Standards and interoperability: Industry bodies such as the OIF are actively publishing interoperability metrics and test frameworks relevant to 25G and higher interfaces. Companies that align early to these specifications will shorten qualification cycles and reduce field failures.
-
Geopolitical and regulatory risk: Export controls and regional tensions are increasing the cost and complexity of resilient sourcing strategies. For organizations with global footprints, supplier diversification and near-shore contingency plans are no longer optional.
What PW Consulting’s 25G Report Delivers — Practical, Executable Outputs
This is not a high-level narrative. The report was built for decision-makers who must convert insight into action in 2026. Key practical deliverables include:
-
Transparent market-sizing and forecasting methodology — reproducible models that trace demand drivers, adoption timelines and unit economics across the 2026–2032 horizon.
-
A buyer’s playbook — procurement frameworks for tendering, long-term contracting templates, supplier qualification checklists and negotiation levers tailored to optical chip supply dynamics.
-
Supplier benchmarking and risk scoring — a multi-dimensional scorecard covering technology depth, capacity posture, geographic concentration, qualification lead times and commercial flexibility.
-
Technology trade-off matrices — side-by-side evaluation of laser types and photodetector approaches aligned to reach, power, cost and manufacturability trade-offs to support SKU rationalization or new product definition.
-
CapEx and supply-chain scenario tools — sensitivity models that quantify the impact of capacity constraints, material shortages and tariff/embargo scenarios on unit cost, lead time and margin.
-
M&A and partnership screening playbooks — criteria and valuation heuristics for bolt-on acquisitions, joint development agreements and foundry partnerships.
-
Field qualification acceleration templates — test-plan blueprints, interoperability checkpoints, and sample size recommendations to compress qualification cycles without increasing rollout risk.
-
Executive dashboard — a one-page impact summary linking macro forecasts, supplier exposure and recommended 90/180/360-day actions to support board-level decisions in 2026.
Competitive Landscape — Who Matters and Why
The 25G supplier ecosystem combines multi-national incumbents with regional specialists. Market concentration remains meaningful: our CR3 and CR5 metrics indicate a moderately consolidated market (CR3 approximately 38.5%, CR5 approximately 52.2%), which has direct implications for bargaining power, availability and strategic partnership choices.
-
MACOM — Strong in DFB laser diodes optimized for direct modulation and uncooled operation; well-positioned for 5G fronthaul and certain data-center link designs. Their continued presence at leading industry forums signals an emphasis on product-portfolio depth and channel engagement.
-
Lumentum — A leader in InP EMLs and wafer-foundry capabilities. For buyers requiring high-performance long-reach or temperature-stable modules, Lumentum’s vertically integrated supply model shortens lead times but can command premium commercial terms.
-
Broadcom — Deep integration with data center networking ecosystems and expertise in VCSEL and laser link technologies. Broadcom’s platform position makes it a preferred partner for OEMs seeking tight hardware-software co-optimization.
-
Coherent Corp. (formerly II-VI / Finisar) — Broad portfolio across transceivers and lasers, substantial manufacturing footprint and a track record of rapid scale-up for telecom and datacom segments. Their channel reach supports rapid qualification for large customers.
-
Accelink, InnoLight, GLSUN — Regional champions with strong manufacturability and competitive cost positions for mainstream 25G modules. For firms seeking supply affordability and scale in Asia, these players are critical but require careful qualification and IP diligence.
-
NEC Corporation — Notable for recent product launches in 2025 that extend reach and bidirectional transmission capabilities, demonstrating an emphasis on enabling low-power upgrades from legacy systems. NEC’s portfolio can be attractive for operators managing phased migration strategies.
Recent Market Signals that Change the Playbook
-
Product launches in 2025 from established players (including extended-reach and BiDi transceivers) show a push to capture migration spend from 10G to 25G while minimizing infrastructure changes.
-
Supply-chain reports in 2026 flag near-full utilization for certain laser technologies and multi-year backlogs at leading fabs — a clear signal that procurement cycles and multi-source strategies must be planned well in advance.
-
Standardization work from industry forums is reducing interoperability risk, enabling faster time-to-deployment for vendors that conform early to published test matrices.
-
Geopolitical pressure on advanced packaging and certain substrate materials is prompting buyers to quantify nationality-of-origin risk and to consider near-shoreized capabilities as part of resilience planning.
Scenario Planning: What to Watch in 2026
Our report presents three pragmatic scenarios with trigger-based actions:
-
Baseline (CAGR 7.5%): Steady adoption driven by cloud and 5G, with supply-side frictions managed via longer lead times and prioritized allocation. Recommended action: secure rolling 12–24 month supply agreements with pricing floors tied to clear volume bands.
-
Accelerated adoption: If AI-driven interconnect density or a faster-than-expected 5G upgrade cycle materializes, demand could outstrip forecasted capacity in 2026–2027. Recommended action: fast-track strategic investments in capacity co-funding or exclusive short-term supply arrangements.
-
Constrained supply / geopolitical disruption: Material export controls or a packaging shortage could create sharp localized shortages and price volatility. Recommended action: activate dual-sourcing playbooks, release buffer inventory thresholds and reassign critical traffic to alternative top-of-rack architectures temporarily.
Immediate 90-Day Actions for 2026
-
Run supplier exposure mapping against the report’s supplier scorecards to identify single-source risks and prioritize dual-qualification of at least two alternative vendors for every critical optical chip family.
-
Initiate joint forecasting cadences with strategic suppliers to secure allocation and to reduce market-driven lead-time variability.
-
Embed interoperability test requirements into procurement contracts, referencing OIF-aligned test metrics to accelerate rollouts and reduce integration cost overruns.
-
Model short-term capex for modular assembly or localized packaging to hedge against near-term supply-chain disruptions where unit economics justify the investment.
Conclusion — The Strategic Value of PW Consulting’s 25G Study
Entering 2026, the 25G optical chip market presents a composite opportunity: strong and steady market growth (7.5% CAGR to 2032) alongside real operational risks rooted in supply concentration, component bottlenecks and evolving standards. PW Consulting’s 25G report translates these macro dynamics into executable commercial playbooks, supplier-risk tools and scenario models. It is designed for procurement chiefs, product leaders, CTOs and corporate strategists who must convert market forecasts into defensible, time-sensitive decisions.
To access the full dataset, proprietary supplier scorecards, interactive scenario models and the actionable templates referenced in this brief, please visit the PW Consulting report page or reach out to our industry team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Small-Volume Personal Care Packaging Poised for a Steady 4.4% CAGR Through 2032
By pmarketresearch, 2026-07-07
Small Volume Personal Care Packaging Market: Strategic Playbook for 2026
Executive preview
PW Consulting’s latest market study on Small Volume Personal Care Packaging provides a decision-grade, strategy-first roadmap for executives planning product, procurement, and M&A activity in 2026. The market has demonstrated steady expansion, rising from approximately USD 5,543 million in 2020 to roughly USD 6,785 million in the 2025 base year, and our modeled outlook projects growth to an estimated USD 9,172 million by 2032 under a 4.4% CAGR for the forecast period 2026–2032. These macro trajectories conceal a complex mix of fast-moving subsegments, material substitutions, and regulatory tensions that will materially affect capital allocation and go-to-market choices in the coming 12–24 months.
Small Volume Personal Care Packaging Market
Why this report matters to corporate decision-makers in 2026
- Actionable clarity in a fragmented market: Market concentration remains low (CR3 ≈ 18.5%, CR5 ≈ 24.1%), meaning brand owners face a broad field of converters and innovators. Our report synthesizes which supplier archetypes will scale reliably versus those that are attractive short-term partners for niche launches.
- Quantified growth envelope for portfolio planning: The market’s 4.4% CAGR provides a defensible baseline for volume planning and capex prioritization; we overlay that baseline with scenario-specific uplift/downside for travel retail, prestige minis, and sampler strategies so teams can stress-test SKUs and capacity investments.
- Regulatory and input-cost risk baked into commercial models: We model near-term feedstock pressure (notably PE and PP) and the business impacts of increasingly prescriptive recycled-content laws and Extended Producer Responsibility schemes—inputs that materially alter unit economics for small-volume formats.
- Fast-to-apply playbooks: The study turns insight into execution—supplier scorecards, low-MOQ sourcing templates, and pilot design-of-experiments for converting to PCR and fibre-based alternatives without undermining brand experience.
What the report contains (practical, field-tested deliverables)
- Market sizing and forecasting: transparent methodology, base-year calibration (2025) and scenario outputs for 2026–2032 with demand drivers mapped to commercial levers.
- Segment economics: unit-cost models for common small-volume formats, sensitivity analysis to raw-material swings and freight uplift, and break-even matrices for in-house filling versus tolling.
- Supplier and capability matrix: detailed profiles of global converters, OEMs and specialty designers, with capability flags (low-MOQ, micro-dosing, airless systems, refillable mechanics, PCR-capable lines).
- Regulatory playbook: compliance roadmap for recycled content mandates, EPR impact assessment, and an operational checklist for registration, reporting, and on-the-ground traceability.
- Innovation & sustainability lab: technology briefs on airless microdosing, sachet-to-film substitution, paper-based sample formats, and lifecycle trade-off templates for brand sustainability claims.
- Commercial levers & go-to-market templates: piloting checklists, retailer-spec negotiation guides, and an M&A target scoring model to prioritize bolt-ons that accelerate distribution or technical capabilities.
- Case studies & scorecards: real-world examples of brands that successfully deployed travel-size launches, sampling programs, and low-volume refill systems—showing timelines, cost outcomes, and performance KPIs.
Competitive landscape — what to watch from leading suppliers
The supplier field spans global converters, specialist dispensing innovators, and flexible-film manufacturers. Below are the strategic positions and implications for brand owners and procurement teams.
Small Volume Personal Care Packaging Market
- Albéa Group (France) — A global beauty packaging leader with a clear emphasis on compact, low-MOQ solutions and sustainable polymers. Their portfolio and regional collections make them a go-to for prestige serums and gift-sized formats where design fidelity and PCR options matter.
- Aptar Beauty (United States) — Focused on dosing and dispensing innovation, Aptar’s miniature pumps and airless micro-systems are shaping a category of high-feel, hygiene-first products for premium skincare. Their 2026 generation dropper and small-volume pump variants point to continued differentiation through functionality.
- Silgan Dispensing (United States) — Strong in travel-size aerosol and foamer formats; their sampling and minis capability is attractive to brands aiming for tactile trial experiences at scale.
- Berry Global (United States) — Large-scale converter with a growing set of smaller SKU sizes and circular-content platforms; important for brands migrating to recycled-content rigid formats at commercial scale.
- HCP Packaging (UK/global) — Specialist in compacts, palettes and pocket-sized cosmetic engineering—valuable for color cosmetics launches where fit, finish and portability are sales determinants.
- Amcor (Switzerland) — Dominant in flexible sachets and pouches, including paper-based alternatives—critical for large sampling programs and FMCG crossover formats.
- Gerresheimer (Germany) — Glass and specialty rigid solutions for premium applications; relevant where premium feel or barrier performance justifies higher unit cost.
- Unit Pack & JP Packaging (United States) — Niche specialists in unit-dose and thermoformed sample systems, typically targeted by brands seeking technical accuracy, sterility, or highly controlled single-use formats.
Recent supplier moves underline two ongoing industry dynamics: (1) functional miniaturization—new micro-dosing droppers and airless systems introduced in 2026; (2) a sustainability push—broader range of recyclable and recycled-content formats launched in 2024–2025. These provide both opportunity and procurement complexity for brand teams.
Small Volume Personal Care Packaging Market
Market dynamics and regulatory headwinds
- Raw-material volatility: Early-2026 feedstock pressure in polyethylene and polypropylene has driven spot-cost increases; our modeling shows small-volume plastic formats are disproportionately sensitive to per-unit cost swings given thin packaging margins.
- Recycled-content mandates: States are implementing stepped PCR targets (for example, phased increases that reach substantial percentages by the early 2030s). Brands selling in affected jurisdictions must plan PCR adoption timelines now to avoid compliance-driven supply interruptions and cost shocks.
- Extended Producer Responsibility (EPR): Producer-funded systems are expanding in the U.S., increasing compliance administration and end-of-life responsibility. These schemes shift the total cost of ownership for packaging and elevate the strategic value of reusable and take-back pilots.
- Trade-offs across materials: Substituting plastics with glass, metal, or fiber reduces some regulatory exposure but introduces weight, breakage, and carbon trade-offs. Our lifecycle templates help quantify these trade-offs per SKU.
Strategic recommendations for 2026 — prioritized actions
- Implement a PCR transition roadmap with phased pilots: target high-volume SKUs first for demonstration, then expand to prestige minis. Use supplier scorecards in the report to select partners capable of PCR at low MOQs.
- Hedge feedstock exposure: contract strategies (fixed-price windows, index-linked hedges) and dual-sourcing for high-risk components will reduce margin volatility for small-volume SKUs.
- Rationalize the small-volume portfolio: deploy a two-track approach—(A) premium, functional minis that justify higher per-unit cost via premium pricing and (B) low-cost sampler formats (flexible sachets/pouches) for mass reach. The report includes financial templates to test these tracks against the 4.4% baseline growth scenario.
- Fast-follower procurement for innovation: prioritize partners delivering micro-dosing and hygiene-first dispensers for prestige skincare; negotiate co-development clauses and IP cadence to preserve time-to-market advantage.
- Prepare for EPR and reporting: centralize compliance data flows now, and use the report’s registration checklists to avoid last-minute supply disruptions and penalty exposure.
- Targeted M&A and partnerships: prioritize small converters with proven low-MOQ lines or unique dispensing technologies—our M&A scorecard ranks targets by strategic fit and scale-up risk.
How to use this report in board-level planning
- For C-suite: use the report to align product portfolio and sustainability targets with forecasted market growth and regulatory timelines; the provided scenario outputs inform capex and global sourcing choices.
- For procurement: adopt the supplier matrix and negotiation playbooks to reduce unit costs while meeting PCR and traceability requirements.
- For R&D and packaging innovation: prioritize micro-dosing and refill mechanics highlighted in our technology briefs; run the lab’s A/B pilot checklist for consumer and stability testing.
- For M&A and corporate development: apply the target scoring methodology to shortlist bolt-on acquisitions that expedite low-MOQ capability or proprietary dispensing tech.
Next steps and where to get the full intelligence
This release intentionally presents strategic takeaways and high-level, data-driven context while reserving detailed segment-by-segment tables, regional breakdowns, and unit-cost spreadsheets for the full report. That granular intelligence is purpose-built to support 2026 procurement cycles, SKU rationalization workshops, and board-level capital allocation decisions. To access the complete dataset, proprietary supplier scorecards, scenario models, and ready-to-deploy templates, visit the PW Consulting Small Volume Personal Care Packaging Market report page or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Small Volume Personal Care Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: High-Barrier MDO‑PE Film Market Set to Accelerate at a 14.5% CAGR
By pmarketresearch, 2026-07-07
High Barrier MDO-PE Film Market: Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting's new market research report on High Barrier Machine Direction Oriented Polyethylene (MDO-PE) films sets out an operational roadmap for commercial, procurement and investment decisions in 2026 and beyond. The global market has moved rapidly from niche replacement concepts into established commercial deployments — expanding from roughly USD 250 million in 2020 to about USD 486 million in 2025. Our forecast sees sustained, above-market expansion through the 2026–2032 horizon at a compound annual growth rate of approximately 14.5%, with the market size crossing the USD 1.25 billion mark by 2032. Market concentration remains moderate, with the top-three and top-five firms accounting for material but not dominant shares, signaling room for differentiation and consolidation plays.
High Barrier Mdo Pe Film Market
Why 2026 is a pivot year
-
Regulatory inflection: Packaging regulations in major markets are maturing from aspirational targets to hard requirements. Notably, EU packaging mandates are increasing recycled-content and mono-material preferences for contact-sensitive formats by the end of the decade, accelerating commercial interest in recyclable, high-barrier PE constructions.
High Barrier Mdo Pe Film Market -
Material economics and supply dynamics: Volatility in HDPE and related feedstock remains a commercial reality; recent pricing swings demonstrate how upstream cycles can rapidly alter conversion economics for flexible-packaging players. Buyers and converters must now balance short-term raw-material exposures with long-term design-for-recycling gains.
High Barrier Mdo Pe Film Market -
Technology and product maturity: New EVOH-integrated co-extrusions, high-barrier coated options and downgauging breakthroughs have pushed mono-material PE solutions into applications historically reserved for multi-material laminates and metallized foils — from coffee and snack pouches to freeze-stable industrial applications.
What the PW Consulting report delivers — practical, decision-focused content
Our research is structured to be executable for procurement teams, packaging technologists, corporate strategists and private equity investors considering roll-ups or minority stakes. Highlights include:
-
Market sizing and forward-looking demand modelling (2020–2032) with scenario runs sensitive to regulatory adoption rates, feedstock prices and conversion efficiencies.
-
Technology benchmarking and manufacturing economics: process maps for EVOH co-extrusion, vacuum coatings and polyamide-PE structures; capex/opex ranges; thickness/weight trade-offs and downgauging case studies.
-
Supplier capability matrix and go-to-market playbooks: a vendor-shortlist framework that maps technical competencies, geographic service footprints, and strategic fit for converters and brand owners.
-
Commercial templates and negotiation levers: indexed pricing model, raw-material pass-through clauses, quality acceptance criteria and pilot-to-scale conversion checklists.
-
Regulatory and sustainability integrations: compliance timelines, recycled-content pathways, and test-protocol recommendations to demonstrate recyclability and maintain shelf-life/odor protection.
-
M&A & investment pack: target-screening filters, value-creation levers (e.g., manufacturing footprint rationalization, product portfolio adjacencies), and an indicative transaction premium matrix tied to technology ownership and proprietary coating capabilities.
We intentionally present deep, actionable models and templates while withholding fully itemized segmentation datapoints in this release — those core tables and company-level revenue schedules are available in the full report and bespoke briefings.
Competitive landscape: strategic signals from leading suppliers
The competitive set is a mix of global film specialists, regional champions and vertically integrated converters. Our analysis synthesizes product innovation, route-to-market and sustainability messaging to identify where competitive advantage is forming.
-
RKW Group (Mannheim, Germany) — RKW's recent commercialisation of an EVOH-integrated MDO-PE platform signals a strategic bet on mono-material replacement for high-value applications. Their positioning targets brand owners seeking parity with multi-material barriers while improving end-of-life recyclability. Expect pricing premia on functionality and enhanced co-development agreements with food and lidding converters.
-
Polifilm (Germany) — Polifilm’s POLIPURE line articulates a dual route: a direct mono-material proposition and a transitional barrier substrate for laminators. Their strength lies in printability and stiffness enhancements that make switching from PET/OPP/OPA operationally feasible for many converters.
-
CloudFilm (Qingdao, China) — Chinese manufacturers are moving up the value chain quickly, offering high-barrier variants and coated AlOx options suitable for food and pharmaceutical laminates. CloudFilm typifies the competitive pressure on pricing, lead times and local service that global buyers must now factor into sourcing strategies.
-
TOPESOL (China) — Technical differentiation is TOPESOL’s play: OTR and WVTR targets approaching foil-like performance enable PE-only constructions in aroma-sensitive and long-shelf-life categories. Proprietary high-barrier grades create defensibility for converters seeking foil replacement.
-
Longdapac, Novel Packaging, Silvalac, ISOFlex — These firms represent a spectrum from cost-competitive polymer-film producers to niche innovators focused on rigidity, downgauging and How2Recycle/consumer-facing compliance. Their strategies vary from commoditised supply to product-depth differentiation in targeted segments like coffee, pet food and medical pouching.
Two recent market events illustrate competitive dynamics: RKW’s mid-2025 EVOH-integrated MDO-PE launch, which accelerates commercialization timelines for mono-material barrier films; and a strategic collaboration announced in late 2025 between a major polymer producer and a cast-film specialist to deliver downgauged deep-freeze solutions. Both developments compress time-to-market for alternatives to conventional laminates.
Commercial implications for buyers, converters and investors
Our 2026 guidance is pragmatic: the pathway to commercial adoption is a mix of technical verification, contractual protections and staged scale-up. Key recommendations:
-
Procurement: implement layered sourcing with technology qualifiers and price collars. Short-term cost anomalies in HDPE can be offset by lifecycle savings from downgauging and simplified recycling streams.
-
Converters/Brand Owners: run parallel pilots for mono-material conversions on representative SKUs, prioritizing high-volume SKUs with moderate barrier requirements first. Use accelerated shelf-life and aroma-trace testing to de-risk rollouts.
-
Investors: look for platforms owning coating or co-extrusion IP, plus converters with multi-site capabilities and established blue-chip customer lists. Opportunistic roll-ups can generate margin expansion via supply-chain integration and broader service offerings.
Risk matrix and scenario planning
Key downside and upside scenarios are modelled in the report. Primary risks include raw-material price resurgence, slower-than-expected regulatory enforcement, and substitution by alternative barrier chemistries. Upside catalysts include rapid regulator-driven adoption, breakthroughs in downgauging that materially reduce per-unit film costs, and consolidation that yields capacity rationalisation and margin expansion. Our scenario engine quantifies P&L sensitivity across these vectors and is supplied with the report for direct use in board-level decision-making.
How PW Consulting supports your 2026 strategy
We designed this study to be more than a market map — it is a set of operational tools. PW Consulting offers tailored briefings that unpack: supplier scorecards with verifiable KPIs, contract-language playbooks for barrier-film procurement, pilot design templates, and an investment due diligence package with valuation adjustments for regulatory and feedstock risk.
Next steps (call to action)
If your 2026 planning requires switching packaging architecture, hedging raw-material exposure, or evaluating M&A in the flexible-barrier film space, PW Consulting’s full High Barrier MDO-PE Film Market report contains the detailed segmentation tables, company revenue schedules, regional and application-level forecasts and downloadable financial models not disclosed in this release. Visit the PW Consulting report page or contact our strategic advisory desk to request the complete dataset, schedule a private briefing, or commission a customised scenario run tailored to your portfolio or operating geography.
For detailed analysis of this topic, please visit the official page: High Barrier Mdo Pe Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com