

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cold Roof Coating Market Poised to Reach USD 8.61 Billion by 2032, Growing at a 7.15% CAGR

Cold Roof Coating Market Outlook 2026: Strategy Briefing from PW Consulting
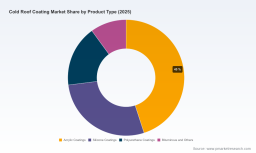
PW Consulting today publishes an executive briefing drawn from our forthcoming Cold Roof Coating Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The market for cold (reflective) roof coatings is on a sustained growth path — our model pegs a compound annual growth rate (CAGR) of 7.15% across the 2026–2032 forecast window. In monetary terms, the market expands from roughly USD 5.3 billion in 2025 to an anticipated USD 8.6 billion by 2032 (USD, revenue unit: Million).
Cold Roof Coating Market
Why this matters for 2026 decision-makers
- Policy and procurement timelines are converging. Building codes, municipal heat-island mitigation programs, and corporate net-zero commitments are moving from guidance to procurement criteria. Products that are CRRC-rated and demonstrate lifecycle energy savings are increasingly prerequisites for large public and private contracts.
- Standards and testing have become a practical constraint and opportunity. ANSI/CRRC S100-2025 introduced revised protocols for liquid-applied coatings and polymer/composite materials that materially affect how products are validated. The standard update, and CRRC’s move to accredit independent international testing labs, changes time-to-market and compliance cost calculations.
- Margins are under pressure from raw material volatility. Resin feedstocks, titanium dioxide pigments, and specialty additives experience price swings that flow directly into production cost models. At the same time, higher-value chemistries such as silicone formulations command meaningful price premiums due to longer service life and reduced maintenance cycles.
- Commercial product strategies are being reshaped by warranty and performance programs. Recent industry actions—ranging from extended warranty programs to CRRC-listings and Title 24 compliance claims—shift value toward manufacturers that can pair validated performance with strong installer networks and risk-sharing warranties.
What PW Consulting’s report delivers (practical, operational, decision-ready)
Our full Cold Roof Coating Market report is explicitly designed as a playbook for 2026 planning cycles. It blends market-level sizing with actionable modules that procurement, product, and corporate strategy teams can use immediately. Highlights include:
Cold Roof Coating Market
- Forward-looking market size and revenue models (2026–2032) with scenario analysis under alternative regulatory and raw material cost paths.
- Unit-cost and margin models for the principal technology classes, enabling SKU-level pricing stress tests and profitability sensitivity runs.
- A compliance and specification matrix tied to ANSI/CRRC S100-2025 and common regional building-code requirements, with recommended test pathways to optimize time-to-certification.
- Go-to-market playbooks for new entrants and incumbents: distribution channel mapping, installer certification programs, specification-sales frameworks, and warranty design options.
- Supplier and raw-material risk heatmaps plus mitigation steps (hedging approaches, alternative chemistries, strategic sourcing buffers).
- Commercial tools for end-users: lifecycle cost comparison templates, HVAC load reduction calculators, and retrofit vs. replacement decision flows.
- M&A and partnership scouting: candidate profiles, valuation heuristics, and integration playbooks focused on technology, channel reach, and testing/certification assets.
To preserve competitive advantage for subscribers, the report deliberately withholds granular split tables in this public briefing. The full dataset, including downloadable models and transaction-ready slides, is available through the PW Consulting report portal.
Cold Roof Coating Market
Market structure and competitive dynamics — what to expect in 2026
The cold roof coating market exhibits moderate concentration. The top three global players represent roughly one-third of market revenue, and the top five approach the mid‑40s percentage share — a structure that allows both scale-driven firms and regional specialists to coexist. Competitive advantage is driven by a combination of validated performance (CRRC, ASTM), channel control (distribution + contractor networks), and technical differentiation (polymer chemistry, ceramic additives, UV-stable pigments).
- Scale and specification leadership: Established coatings multinationals with broad architectural and industrial portfolios are leveraging global labs, long-standing customer relationships, and deep distribution to defend large accounts. These firms invest in formulation R&D and program-level warranty support to command specification lists for commercial projects.
- Technical differentiation: Players focused on higher-margin chemistries (e.g., silicone systems, proprietary ceramic dispersions, insulative nanomaterials) compete on lifecycle cost and reduced maintenance frequency rather than entry price.
- Restoration and service-first providers: Brands offering system-level solutions (liquid-applied membranes, fiber reinforcement, integrated waterproofing) tie coatings to broader roof-restoration value propositions, enabling long-term service contracts and installer exclusives.
- Specialists and regional champions: Local manufacturers and niche innovators use code and incentive familiarity plus installer networks to defend regional volumes—particularly where procurement favors local-sourcing or compliance with specific jurisdictional standards.
Notable company positioning and recent moves
Key incumbents and innovators are setting the pace in different dimensions:
- Sherwin-Williams — Leverages pigment and formulation depth to serve commercial and industrial systems with infrared-reflective pigments and integrated application systems.
- PPG Industries — Competes on high-reflectivity formulations and global architectural reach; positions high-SRI products for large-scale deployments.
- AkzoNobel — Focused on elastomeric, durable roof coatings targeted at weather resistance and long-term performance in commercial roofing.
- RPM (Tremco) — Packages liquid-applied coatings within roof-restoration systems and installer-backed warranty offerings.
- BASF & Dow — Play the materials-infrastructure role: dispersions, elastomers, and digital tools (e.g., energy-savings calculators) that support specification and OEM formulation strategies.
- Sika, GAF, Henry (Carlisle) and others — Combine waterproofing systems or high-stability pigments with installer networks and product warranties to secure large project pipelines.
- Specialists (NanoTech Materials, Castagra, Neogard/Hempel) — Differentiate through ceramic/nano additives, VOC-free formulations, and CRRC/Title-compliant product launches. Recent examples include new eco-friendly fiber-reinforced product rollouts and extended warranty programs that aim to convert retrofit markets.
Recent industry milestones — such as CRRC’s 2025 standard updates and its accreditation of independent international test labs — materially change compliance timelines and elevate the strategic value of in-house or partner lab capacity. Separately, product launches and warranty programs announced in 2024–2026 illustrate the dual front of technology and commercial risk-transfer initiatives shaping buyer decisions.
Risks, catalysts, and near-term watch items
- Raw material price volatility: Acrylic and silicone resin feedstocks, pigment availability and specialty additives will influence margins and could compress low-margin segments unless pass-through mechanisms or hedges are in place.
- Regulatory and standards shifts: Additional CRRC refinements or regional code updates could accelerate demand but raise near-term certification cost and time-to-specification.
- Installer capacity and labor dynamics: High-quality application is a gating factor for warranty-backed products; installer certification programs and labor availability will be central to scaling advanced solutions.
- Technology substitutions: Proprietary ceramic blends, nanomaterials, and hybrid systems could reprice the performance-per-dollar equation and create new premium tiers.
- Green procurement incentives: Municipal and corporate incentive programs tied to SRI/reflectance metrics will be accelerants for adoption in retrofit markets.
How companies should act in 2026
- Manufacturers: Prioritize CRRC testing pathways, align SKU mix to risk-adjusted margin models, and build installer certification ecosystems tied to warranty products.
- Distributors / installers: Differentiate via integrated specification support, performance documentation, and managed-service agreements that reduce owner perceived risk.
- Building owners / facility managers: Use lifecycle cost tools to evaluate payback; demand certified performance claims and warranty alignment with expected service intervals.
- Private equity / investors: Focus diligence on asset-light platform plays that can scale installer networks or on technology plays that deliver genuine lifecycle delta versus commodity acrylics.
- Policymakers and utilities: Structure incentives around demonstrated energy savings and long-run maintenance reductions to maximize public benefit.
Next steps and how to get the full intelligence
This briefing is intended to frame the strategic choices and operational levers that PW Consulting’s Cold Roof Coating Market report covers in depth. Our work combines granular forecasting, SKU-level margin modeling, compliance playbooks, supplier risk matrices, and M&A-ready diligence packages. For teams preparing 2026 budgets, R&D roadmaps, procurement specifications, or transaction screening — the full dataset and executable templates are available through the PW Consulting report portal.
Contact PW Consulting for access to the report, companion models, and a briefing session tailored to your organization’s role in the cold roof coatings value chain.
For detailed analysis of this topic, please visit the official page: Cold Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com