

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyelectrolyte Market to Reach USD 4,952.42 Million by 2032 at a 5.31% CAGR, Led by Asia Pacific's USD 1,380 Million Share

Polyelectrolyte Market Outlook 2026: Strategic Signals for Executive Decision-Making
Executive summary
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a concise preview of our latest Polyelectrolyte Market report (base year 2025). The global polyelectrolyte market is on a steady growth trajectory with a compound annual growth rate (CAGR) of 5.31% through the 2026–2032 forecast window. Our modelling shows the market expanding from an estimated USD 3,450 Million in 2025 to approximately USD 4,952 Million by 2032, with the next twelve months representing a pivotal planning horizon for procurement, capacity investment, and portfolio restructuring.
Polyelectrolyte Market
This communication follows a ‘trailer’ principle: it surfaces the analytical architecture, strategic implications, and actionable frameworks contained in the full report while intentionally withholding the granular segment-level tables and proprietary split data that executive teams rely upon for transaction- and bid-level decisions. Those detailed exhibits and scenario worksheets are available in the full report on our website or through a direct client briefing.
Polyelectrolyte Market
Why 2026 is a strategic inflection point
-
Consolidation meets regulation: The market’s top-tier concentration metrics—CR3 ≈ 34.8% and CR5 ≈ 47.5%—indicate a competitive environment in which a small group of global and regional players influence pricing, technology diffusion, and supply reliability. For buyers and investors, 2026 is the first full planning year in which the interplay of consolidation and tighter environmental standards will materially affect contract structures and CAPEX timing.
Polyelectrolyte Market -
Supply chain and input-cost volatility: Polyacrylamide and acrylamide-input dynamics have shown regional divergence through 2025. Notably, China’s domestic polyacrylamide pricing softened across the year, while Northeast Asia and Europe displayed modest upward pressure in late 2025. Acrylamide production remains linked to petroleum-derived feedstocks, keeping polymer producers exposed to crude-price and logistics volatility—an exposure that will shape hedging and sourcing strategies in 2026.
-
Policy-driven demand acceleration: Stricter wastewater discharge and chemical-safety regulations are accelerating upgrades in municipal and industrial treatment plants. That regulatory push is lifting demand for higher-performance polyelectrolytes and creating windows for product substitution and premiumization—opportunities that are measurable at the product-line and customer-segment level in our full analysis.
Key market dynamics that will drive decisions in 2026
-
Volume growth with selective premiumization. Our topline forecast (2026 base-up projection) anticipates both steady volume expansion and pockets of above-market-value demand where treatment specifications and environmental enforcement require specialty chemistries. Procurement teams should expect a mix of commoditized buying behavior for bulk grades and value-based negotiations where performance and compliance matter.
-
Regional cost arbitrage and localization pressure. Variances in regional feedstock prices and energy inputs continue to produce cost differentials. Manufacturers are responding with localized capacity builds and contract diversification; buyers should plan multi-sourcing strategies and conditional bilateral agreements to mitigate single-source exposure.
-
Technology and formulation as differentiation levers. R&D investment is focusing on higher molecular-weight polymers, tailored charge densities, and formulations that reduce sludge volumes or improve dewaterability. These technical attributes create clear procurement evaluation criteria beyond price—criteria we quantify and prioritise in our supplier scorecards.
-
Environmental and health compliance shaping product choice. Regulatory frameworks are tightening across wastewater discharge and chemical handling. As a result, lifecycle assessments, disclosure of residual monomers, and product stewardship are becoming procurement-filtering conditions rather than optional value-adds.
Competitive landscape — what corporate strategists need to know
The competitive map combines global leaders, regional champions, and capacity-intense producers from Asia. Major multinational players maintain integrated product portfolios and extensive manufacturing footprints, enabling them to defend premium segments and large municipal contracts. Regional producers, particularly in Asia, are scaling rapidly with high-volume production capabilities and cost-competitive offerings focused on industrial flocculation and mining applications.
-
Global integrated suppliers: Companies with multi-site manufacturing and established brand portfolios (water-focused product lines and paper-chemicals heritage) will continue to leverage scale, applied R&D, and service models to capture municipal and industrial megaprojects.
-
Emerging high-volume manufacturers: Several large-capacity producers from Asia pursue aggressive local and export growth, using cost advantage and production scale to contest commoditized segments—an important consideration for price-sensitive buyers and OEM partners.
-
Specialty and service-oriented players: Firms that bundle chemical supply with engineering, monitoring, and plant-optimization services are winning share in high-complexity contracts where performance guarantees and OPEX reduction are central contract features.
Our competitive profiles in the full report include manufacturing footprints, product portfolios, strategic moves (capacity additions, partnerships), and supplier strength matrices. Executive summaries for each major supplier are provided to help buyers shortlist partners by capability and risk tolerance—information we do not publish in full within this press release to preserve client exclusivity.
Actionable frameworks included in the report
This study is built to be operationally useful for 2026 planning cycles. The full deliverable contains:
-
Scenario-based demand models (short, medium, long) calibrated to macroeconomic outlooks and regulatory intensity, enabling rapid sensitivity testing for CAPEX and procurement budgets.
-
Supplier scorecards and a procurement playbook that translate performance attributes (molecular weight, charge density, residual monomer levels) into negotiation levers and service level KPIs.
-
Supply-chain risk heatmaps and mitigation options, including dual-sourcing templates, stock-sizing heuristics, and contract clauses for feedstock pass-throughs.
-
Unit-cost models and margin buckets for producers—useful for private-equity diligence and for strategists assessing the economics of vertical integration or toll-manufacturing partnerships.
-
Regulatory scenario matrices (compliance pathways) showing where substitution premium opportunities will emerge under varying enforcement regimes.
-
Deal origination lists and M&A screening criteria focused on bolt-on targets and capacity plays that align with regional demand growth and product-mix optimization.
Strategic implications by function (what each executive should prioritize)
-
Procurement: Move from purely price-based sourcing to a hybrid model that prices in service, technical support, and compliance risks. Use our supplier scorecards to re-bid material contracts with conditional performance payments tied to dewatering or polymer-efficiency metrics.
-
Operations & manufacturing: Reassess production footprints versus feedstock exposure. Where upstream acrylamide dependence creates volatility, consider tolling arrangements or incremental on-site monomer storage as hedges.
-
R&D & product: Prioritize formulations that reduce sludge volume and energy intensity—these attributes will be monetizable through performance contracts and are increasingly demanded by municipal buyers.
-
Corporate development & investment: Target acquisition candidates that add technical depth or localized capacity in markets where trade barriers and logistics costs blunt export economics.
-
Risk & compliance: Integrate lifecycle assessments and residual-monomer disclosure into supplier selection criteria. Prepare for incremental compliance costs by modeling them into 2026 procurement cycles.
How to use this report in your 2026 planning
The primary value of our report is practical integration: marrying market forecasts (historical 2020–2025 base and forecast 2026–2032) with executable procurement and investment playbooks. For CFOs, the topline growth and concentration metrics provide a basis for scenario budgeting. For procurement heads, our negotiation templates and supplier heatmaps shorten sourcing cycles. For M&A teams, the deal pipeline and valuation sensitivity tables accelerate target screening and transaction structuring.
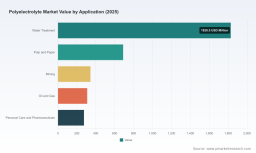
We emphasize that while this press release highlights thematic drivers and top-level forecasts—total market estimates and aggregate growth rates—the detailed regional, type, and application split tables that underpin contract-level decisions are available only in the full report and through PW Consulting client briefings. That granular intelligence is where actionable savings and strategic advantage are crystallized.
Closing and next steps
Polyelectrolytes remain a mission-critical input across water treatment, pulp & paper, mining, oil & gas, and specialty applications. The market’s steady CAGR of 5.31% combined with regulatory uplift and regional cost differentials creates a landscape where timely strategic choices in 2026 can materially improve commercial outcomes.
To access the full dataset, supplier matrices, and scenario tools that support near-term decisions, visit the PW Consulting report page or contact our industry desk to schedule a tailored briefing. Our full report equips executive teams to convert macro signals into procurement savings, defensible CAPEX choices, and prioritized M&A roadmaps—without the noise.
For detailed analysis of this topic, please visit the official page: Polyelectrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com