

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Pancreatic Enzymes & Supplements Market to Reach USD 4,869.65 Million by 2032, Expanding at a 7.24% CAGR

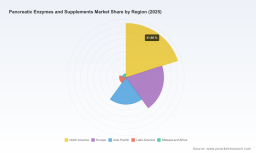
Pancreatic Enzymes and Supplements Market 2026: Strategic Imperatives for Life Sciences Leaders
PW Consulting’s latest market intelligence — the Pancreatic Enzymes And Supplements Market report (base year 2025, forecast 2026–2032) — frames an industry at an inflection point. After a period of steady expansion through the first half of the decade, the global market surpassed USD 2.98 billion (2025, USD Million) and is projected to continue growing at a compound annual growth rate of 7.24% across our 2026–2032 forecast horizon. By 2032, our model projects a multi-billion-dollar opportunity underpinned by persistent clinical need, constrained raw-material supply, and concentrated commercial leadership. For executives planning resource allocation, M&A, manufacturing investments, or market-entry strategies in 2026, the implications are immediate: act with precision, prioritize supply resilience, and build evidence that secures formulary and payer access.
Pancreatic Enzymes And Supplements Market
Why 2026 Is a Strategic Pivot Year
Several structural features of the pancreatic enzyme ecosystem raise urgency for strategic decisions in 2026. First, the category is clinically essential for patients with exocrine pancreatic insufficiency (EPI) arising from cystic fibrosis, chronic pancreatitis, pancreatectomy and other etiologies. That clinical imperative sustains demand even when pricing and reimbursement pressures mount.
Pancreatic Enzymes And Supplements Market
Second, the category’s supply architecture remains tightly coupled to animal-derived pancreatin and pancrelipase APIs. Manufacturing complexity, source concentration, and periodic capacity limitations have created regional availability disruptions in recent years, and our risk-mapping indicates these constraints will continue to influence commercial performance and patient access into 2026 and beyond.
Pancreatic Enzymes And Supplements Market
Third, market concentration is high: PW Consulting’s competitive analysis shows a compact set of branded prescription PERT players and a handful of API producers that together exert outsized influence on supply, pricing, and innovation pathways. This concentration creates both strategic barrier and tactical opportunities for entrants and incumbents alike.
What the Report Delivers — Practical, Actionable Outputs
- Robust market sizing and a granular forecast model for 2026–2032, including scenario analyses that stress-test demand under supply disruption, payer tightening, and alternative therapy adoption scenarios.
- Clinical and regulatory landscape mapping that synthesizes FDA precedent, prescribing information updates, and the post-2000s NDA environment that governs current PERT approvals — essential reading for regulatory and clinical affairs teams.
- Supply-chain deep dives covering API sourcing, critical-path manufacturing steps, and an independent assessment of global capacity bottlenecks — enabling procurement and operations teams to build mitigation strategies.
- Commercial playbooks for formulary positioning, payer engagement, and patient-assistance design that balance access with sustainable revenue management.
- Competitor intelligence dossiers with product profiles, recent regulatory and commercial developments, and tactical recommendations for partnership, licensing, or targeted M&A.
- Risk and quality matrices aligned to GMP and regulatory expectations, plus a remediation checklist for contract manufacturers and API suppliers.
We designed the report to be a “doer’s manual” for 2026: executives will find the not only the what and the why, but also the how — from drafting an alternative API sourcing strategy to structuring value-based agreements with payers. Note: in line with our “trailer” principle we surface strategic direction and insights in this release but withhold the full proprietary segment tables and granular regional/application splits to drive subscription access to the full dataset.
Competitive Landscape: Who Matters and Why
The market is dominated by established prescription PERT brands and a small set of specialized API manufacturers. Leading commercial PERT brands — marketed by global pharmaceutical firms and specialty players — remain central to treatment patterns for EPI. At the same time, specialist API producers supply the bio-derived pancreatin and pancrelipase that current formulations require.
- AbbVie Inc. — Markets Creon, the most widely used delayed-release pancrelipase capsule for a range of EPI indications. AbbVie’s scale and channel reach make Creon a commercial fulcrum for many healthcare systems.
- VIVUS LLC — Markets Pancreaze and has recently expanded copay support programs that materially affect patient out-of-pocket costs and brand retention among commercially insured populations (copay assistance program expanded in February 2026).
- Digestive Care, Inc. — Markets Pertzye, notable for its bicarbonate-buffered enteric-coated microsphere formulation variant; a differentiated product profile that influences therapy choice for select prescribers.
- Aimmune Therapeutics, Inc. — Markets Zenpep and Viokace, offering both enteric-coated and non-enteric formulations used in conjunction with proton-pump inhibitors in adults, reflecting strategic product diversity within the PERT class.
- Specialist API manufacturers — Companies such as Nordmark Pharma, Shenzhen Hepalink, and Scientific Protein Laboratories manufacture pancreatin/pancrelipase APIs extracted from porcine sources and therefore sit at the center of supply-chain risk and quality assurance conversations.
Recent developments highlight the interplay between quality, regulation, and commercial access. Notably, an FDA warning letter issued in October 2025 to a pancreatin API manufacturer underscores the operational and compliance risks embedded in biological sourcing and processing. Simultaneously, multiple prescription product labeling updates during 2024–2025 and aggressive patient support programs from certain brands continue to reshape market dynamics.
Strategic Implications — What Leaders Must Do in 2026
PW Consulting recommends a prioritized set of strategic actions tailored for three cohort types: incumbent brand holders, API suppliers/CMOs, and new entrants (including consumer-focused OTC supplement players):
- For incumbents: Fortify supply resilience. Establish dual-sourcing arrangements for API, invest in quality-capacity upgrades for owned or contracted manufacturing, and develop contingency allocation protocols to maintain continuity for high-risk patient groups.
- For API producers and CMOs: Proactively invest in regulatory remediation and transparency. The FDA’s heightened scrutiny on biologically derived APIs means quality and documentation now directly influence commercial negotiation strength with formulary committees and brand owners.
- For new entrants and OTC players: Differentiate via evidence. With prescription brands entrenched and no approved generics in the current landscape, OTC offerings must either pursue clear clinical positioning for adjunctive uses or invest in real-world evidence to support claims and channel acceptance.
- Across all players: Re-examine commercial models to balance access and margin. Copay assistance programs are effective short-term patient-access levers but can obscure long-term payer negotiation needs; structured value-based outcomes agreements and indication-specific pricing should be explored where feasible.
Risk Management and Regulatory Readiness
Key 2026 risk vectors include API supply shocks, regulatory enforcement actions, and payer-driven formulary consolidation. Our report’s risk workbook quantifies these scenarios and provides mitigation pathways: manufacturing harmonization checklists, audit-ready documentation templates, and strategic supplier scorecards. Firms that preemptively align quality systems to the stricter end of FDA and global GMP expectations will gain commercial advantage in contracting and tender processes.
Where to Focus Investment and Partnership Capital
Investment and partnership theses that emerge from our analysis are pragmatic and prioritized for near-term ROI:
- Targeted capacity investments that reduce lead times for capsule filling and pouching, rather than speculative expansion of API extraction capacity alone.
- JV or off-take agreements with trusted API producers that include explicit quality KPIs and penalty/relief clauses tied to supply continuity.
- Clinical and HEOR investments demonstrating outcomes and cost-offsets, which materially influence formulary placement and payer negotiations.
- Manufacturing modernization initiatives (automation, contamination control) that materially reduce the risk of regulatory actions and product recalls.
Executive Takeaway
PW Consulting’s analysis concludes that the pancreatic enzymes and supplements market will remain financially attractive through 2032, driven by clinical necessity and disciplined brand economics. However, the pathway to capturing value in 2026 is narrow and operationally intensive: companies must manage supply chains, shore up regulatory compliance, and craft payer-facing value propositions that withstand scrutiny. With CR3 concentration levels indicating that a small number of players command the lion’s share of commercial influence, strategic moves such as alliance formation, selective vertical integration, and targeted HEOR investment will determine who leads the next phase of growth.
Accessing the Full Intelligence
This release highlights the strategic framing and practical implications uncovered in our Pancreatic Enzymes And Supplements Market report. To protect the integrity of our proprietary models and the tactical insight that informs executable decisions, we intentionally limit detailed regional and application-level splits in this summary. Subscribers and corporate clients can access the complete dataset — including scenario-modeled segment tables, supplier maps, and executable playbooks — through PW Consulting’s report portal. For a consultation to translate these findings into a 90–180 day operational plan, contact our advisory team directly.
PW Consulting — translating market intelligence into decisive strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pancreatic Enzymes And Supplements Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com