

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
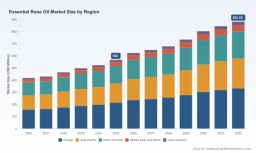
PW Consulting: Essential Rose Oil Market Set to Reach USD 882.66 Million by 2032 at a 6.5% CAGR, with Europe Holding USD 213.72M in 2025

Essential Rose Oil Market — Strategic Outlook 2026: PW Consulting Releases Actionable Intelligence for Executive Decision-Making
PW Consulting today publishes its Essential Rose Oil Market Report (base year 2025), a strategic briefing designed to inform 2026 sourcing, innovation, and M&A decisions across fragrance houses, cosmetic brands, contract manufacturers, and raw material traders. Combining an independently modelled market-size trajectory, a competitive map of incumbent growers and global processors, and a practical playbook for supply-chain resilience, the report translates sector complexity into executable options for senior management.
Essential Rose Oil Market
Why this report matters for 2026
-
A defined growth runway: Our model shows the global essential rose oil market expanding from USD 418.5 Million in 2020 to USD 568.0 Million in 2025, with a compounded annual growth rate of 6.5% through 2032, reaching an expected USD 882.66 Million by 2032. The near-term projection for 2026 is USD 624.27 Million. These headline figures frame the addressable economics for premium naturals strategies and validate continued investment in rose-derived formulations.
Essential Rose Oil Market -
Seasonal and concentration risk: Despite growth, supply dynamics remain fragile because production is highly concentrated geographically and intensely seasonal. Our synthesis of field-level reporting shows cultivation and harvesting continue to rely on a large seasonal workforce, with a very narrow harvest window—facts that materially affect spot availability, quality variation, and cost volatility.
Essential Rose Oil Market -
Strategic inflection points for buyers: The combination of predictable demand growth and constrained supply creates clear decision levers for 2026: diversify sourcing, invest in supplier partnerships and certifications, and consider structured offtake or backward integration to secure high-purity material for premium product tiers.
What’s inside the report — operational, not academic
-
Granular market modelling (2020–2032): time-series revenue scenarios under three demand-growth and price-volatility assumptions, enabling stress-testing of procurement strategies and SKU-level margin sensitivity.
-
Supply-chain blueprint: an operational map from seed to distillate, highlighting pinch points (labor, distillation capacity, storage, and logistics), break-even distillation economics, and a proprietary scorecard for supplier resilience.
-
Commercial playbook for 2026: contract templates, suggested offtake structures, and negotiation levers tailored to different buyer archetypes (boutique perfumers, global fragrance houses, CPG formulators).
-
Sustainability & traceability toolkit: roadmaps for implementing GEO/PO/chain-of-custody approaches and certification prioritization (organic, ethical trade), tied to product premiumization and regulatory expectations in key markets.
-
M&A and partnership shortlists: screened acquisition targets and JV archetypes with estimated integration risks and expected synergies, including practical valuation heuristics specific to essential oil assets.
-
Risk register and hedging playbook: scenario-based mitigation for crop failure, labor unrest, geopolitical exposure, and price spikes—complete with decision trees for when to shift from spot buying to multi-year contracts or equity partnerships.
-
Go-to-market implications: marketing stratagems and claims frameworks to translate traceability investments into consumer value while staying compliant with claims regulations across major geographies.
Note: To preserve the report’s commercial integrity and encourage full due diligence, we are intentionally omitting detailed split tables (regional, type, and application percentages) from this release. The full dataset and interactive dashboards are available through our report portal.
Competitive landscape — who matters and why
The rose oil value chain is a two-tier ecosystem: regionally anchored cultivators and distillers in source countries, and global fragrance/flavor houses and distributors that convert raw material into finished aromas and formulations. Our analysis profiles the strategic posture of leading participants and their implications for buyers in 2026.
-
Regional growers and distillers (Bulgaria-centric leadership): Several established Bulgarian distilleries combine field ownership or long-term grower relationships with extraction capabilities. Their competitive advantages include provenance and traceability from contiguous cultivation areas, control over agronomy and harvest timing, and the ability to certify organic and ethical attributes. These operators remain the primary gatekeepers of high-grade raw material during the short annual harvest window.
-
Global fragrance houses and ingredient suppliers: Major firms with global reach leverage industrial-scale sourcing, technical application support, and diversified product portfolios. Their strengths are contract coverage, formulation expertise, and buyer access, enabling them to smooth short-term supply shocks through inventory and blending strategies. Firms that announced sustainable sourcing strategies and acquisition plans are positioning to capture premium margins whether through proprietary blends or exclusive supply agreements.
-
Distributors and regional exporters: Players with strong documentation and quality-validation capabilities serve as commercial bridges between small distillers and global formulators. They are increasingly active in certification-enabled markets, offering traceability bundles that command pricing premiums with luxury and natural-focused brands.
Market concentration metrics indicate a moderately fragmented sector: the top three companies control roughly one-third of market share, while the top five account for just under half. This structure creates room for strategic consolidation, selective partnerships, and private-equity interest—opportunities we highlight for acquirers and potential divestors alike.
Recent industry movements shaping 2026 strategy
-
Strategic re-alignment: Global fragrance leaders have signalled increasing focus on sustainable, ethically sourced naturals as part of multi-year growth plans. These directional shifts mean buyers should expect competitive bidding for certified supplies and deeper commercial linkages that privilege long-term partners.
-
Certifications matter: Producers obtaining ethical sourcing certifications are already capturing contract advantages in premium segments. Certification is increasingly a non-negotiable commercial asset for access to certain customer channels.
-
Portfolio consolidation by distributors: Recent acquisitions in related essential-oil portfolios illustrate how distributors and traders are scaling to offer broader coverage and inventory depth—an important consideration for manufacturers seeking single-source procurement simplification.
-
Operational investments at source: Expandable distillation capacity and organic acreage investments by regionally-rooted operators point to an industry gradually professionalizing post-harvest management—reducing quality variance over time but not eliminating seasonal scarcity.
Raw material realities that will shape commercial outcomes
-
High input intensity: Rose oil extraction is resource and labor intensive—industry estimates indicate thousands of kilograms of petals are required to produce a single kilogram of essential oil. This underlying biology and labor need amplifies both unit cost and the potential for supply shocks.
-
Price volatility and premium signals: Market observers reported that organic Bulgarian rose oil reached historically high export price points in recent years, signalling how certification and scarcity can drive significant price differentiation. Buyers should be prepared for episodic price spikes tied to crop outcomes and certification premiums.
-
Geographic concentration: The supply base is dominated by a few traditional cultivation regions. This geographic concentration supports strong provenance narratives but also concentrates climate, labor, and regulatory risk.
-
Labor dynamics: A large seasonal workforce underpins the harvest window, and any changes in labor availability, wage levels, or regulation can materially affect yield, quality, and unit economics.
Direct implications for 2026 corporate decisions
-
Sourcing strategy: Prioritize multi-channel sourcing that mixes direct partnerships with regional distillers, validated distributors for short-term coverage, and contractual offtake agreements for high-purity requirements.
-
Certification and premiumization: Consider targeted investment in certification pathways for core SKUs where the brand value justifies the cost, and design SKU ladders to segregate premium-certified claims from mainstream formulations to optimize margin capture.
-
Risk management: Implement a three-tier risk mitigation approach—inventory buffers, flexible quality blending rules, and pre-negotiated escalation clauses for force majeure events tied to harvest outcomes.
-
M&A and partnerships: For companies seeking control of upstream economics, selective acquisitions or JVs with regionally established distillers offer immediate supply security and provenance control. For others, exclusive supply contracts with certification premiums will protect brand positioning without capital intensity.
-
R&D and formulation: Invest in lower-dose reformulations and aroma-modulation technologies to stretch scarce high-grade material across high-value SKUs, reducing exposure to raw-material cost swings.
How PW Consulting supports executive action
Our Essential Rose Oil Market Report is designed as an executive toolkit—not merely a descriptive study. Alongside the full dataset and dashboards, purchasers receive custom scenario workshops, supplier due-diligence templates, and a templated procurement playbook adaptable to different buyer risk appetites. We also provide a tailored M&A target memo on request, focusing on integration risks and synergies for critical upstream assets.
For procurement heads, R&D chiefs, and corporate development teams mapping 2026 priorities, the report condenses complex bio-economic realities into prioritized, actionable pathways. To review the full regional/type/application breakdowns, the detailed supplier matrix, and the interactive financial model, please consult the report portal linked in our release notice.
Contact
PW Consulting — Strategy & Industry Intelligence. For licensing, bespoke advisory, or to request the full dataset and scenario workshop, access the report page via our official portal or contact our client services team.
For detailed analysis of this topic, please visit the official page: Essential Rose Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com