

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Special Electronic Chemicals for Photoresist Market to Reach USD 4,146.57 Million by 2032, Growing at a 5.51% CAGR

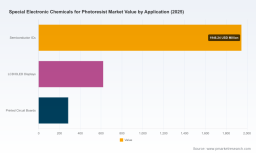
Special Electronic Chemicals For Photoresist Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting today releases an executive synthesis of our Special Electronic Chemicals For Photoresist Market study, built on a detailed base year of 2025 and a seven-year forecast horizon through 2032. The global market for electronic chemicals used in photoresist and photolithography processes reached approximately USD 2,850.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.51% over the 2026–2032 forecast window, reaching broadly above USD 4.1 Billion by 2032. For corporate leaders making capital, sourcing, R&D and M&A decisions in 2026, this study functions as a decision-grade intelligence product: it diagnoses structural shifts, quantifies exposure to regulatory and raw-material shocks, and presents executable playbooks for suppliers, integrated device manufacturers (IDMs), fabless companies and private equity investors.
Special Electronic Chemicals For Photoresist Market
What this means for 2026 strategies — high-level takeaways
- Growth is solid but selective: the market trajectory supports incremental capacity investments AND targeted innovation plays. The headline CAGR masks pockets of rapid technology-driven demand and areas of substitution risk.
- Concentration matters: the top three suppliers account for a meaningful majority of market share, and the top five firms capture an even larger portion of industry revenue — a dynamic that shapes pricing leverage, access to advanced formulations and partner selection for scaling fabs.
- Regulatory risk is now commercial: PFAS-related reviews and evolving U.S. state-level restrictions create short- to medium-term compliance and reformulation demands for key chemistries, particularly in photoacid generators (PAGs) and fluorinated additives.
- Raw-material purity and sourcing resilience are non-negotiable for leading-edge nodes: sub-10 nm processes impose impurity thresholds at parts-per-million and below, materially constraining qualified suppliers and increasing the value of vertically integrated or strategically partnered supply chains.
- Localization and capacity redundancy will be decisive: recent factory and JV announcements signal supplier commitment to localized capacity, which will influence lead times, qualification cycles and commercial terms for 2026 procurement cycles.
Why the market is primed for strategic plays in 2026
Photoresist and related electronic chemical demand remains tightly coupled to capital intensity and node transitions in semiconductors and advanced displays. While headline growth is steady, the underlying drivers are heterogeneous: pockets of aggressive investment in leading-edge fabs and display production are increasing demand for higher-specification resists, photoacid generators and electronic-grade solvents, while legacy nodes and some PCB applications exhibit slower growth or substitution potential.
Special Electronic Chemicals For Photoresist Market
Supply-side moves in the past 24 months underline this bifurcation. Major suppliers are expanding capacity and forming regional manufacturing footprints to reduce lead times and accelerate customer qualification. Examples include capacity and site expansions announced by leading manufacturers, and joint ventures intended to place production closer to key fab clusters. These developments both respond to and reinforce buyer preferences for supply security and technical co-development.
Special Electronic Chemicals For Photoresist Market
Competitive landscape — reading the playbook of incumbents and challengers
The market is shaped by a mix of large, vertically integrated chemical firms and smaller specialty formulators focused on niche applications. The incumbents maintain competitive advantage through scale, proprietary polymer platforms, and deep co-development relationships with leading fabs. Key strategic patterns observed across the competitive set include:
- Technology leadership via formulation depth: suppliers with advanced resist chemistries for EUV and immersion ArF continue to command premium access to leading-edge fabs. Players who maintain differentiated polymer and additive IP benefit from stickier customer relationships.
- Localized capacity and capacity-as-strategy: recent land acquisitions and new manufacturing site planning reveal a clear prioritization of geographic proximity to customers. This reduces qualification friction and mitigates logistics and trade-risk exposures.
- Sustainability and regulatory-driven product development: several leading suppliers are actively developing lower-PFAS footprint chemistries and non-fluorinated alternatives for specific lithography chemistries to anticipate regulatory constraints and customer procurement mandates.
- Specialist niche defenders: smaller firms and European niche suppliers focus on high-purity specialty products for research, electron-beam lithography and custom microfabrication segments, maintaining attractive margin profiles despite limited scale.
For executives benchmarking partners or acquisition targets, the competitive indicators to prioritize are not merely revenue or facility counts, but proprietary resin portfolios, PAG roadmaps, solvent purity management capabilities, and demonstrated regulatory foresight.
Regulatory and raw-material dynamics that will shape 2026 outcomes
Regulatory attention to PFAS and related fluorinated chemistries has moved from long-term risk to near-term commercial planning. Ongoing evaluations under major regulatory frameworks, and the uneven patchwork of state-level restrictions, will impose variable compliance costs across geographies. For companies exposed to PAGs and fluorochemical precursors, active scenario planning is required: reformulation timelines, customer acceptance cycles, and regulatory-driven supply chain reporting will all affect margin and time-to-market.
On raw materials, the industry faces two intersecting constraints: purity thresholds that tighten dramatically for advanced nodes, and concentrated supply of key monomers and specialty solvents. Our field research and supplier audits show that ultra-high-purity solvents and polymer resins operate at impurity ceilings measured in single-digit parts-per-million or lower for critical applications — a technical boundary that increases supplier qualification time and raises the value of in-house analytical capabilities and solvent-recovery programs.
What the PW Consulting report contains — practical, decision-ready modules
- Market-sizing and scenario model: 2020–2025 historical baseline and a 2026–2032 forecast with alternative demand scenarios and sensitivity to node adoption rates and display demand shocks.
- Competitive benchmarking: granular supplier capability mapping (technology, capacity posture, geographic footprint, customer concentration) and a CR-based concentration risk dashboard.
- Technology and formulation matrix: assessment of polymer platforms, PAG families, solvent systems, and hardmask/spin-on technologies with IP and reformulation risk scoring.
- Regulatory impact and mitigation playbooks: PFAS/TSCA scenarios, state-restriction implications, recommended product stewardship responses and contractual protections for buyers and sellers.
- Supply-chain stress-testing: procurement levers, dual-sourcing templates, inventory policies, and purchase-offtake structuring for capacity-constrained chemistries.
- Value-creation templates for investors: due-diligence checklists, margin improvement levers, bolt-on acquisition targets, and JV structuring examples tailored to high-barrier specialty chemistries.
- Operational toolkits: supplier scorecards, qualification timelines, analytical method checklists, and sample contractual clauses to manage raw-material substitution and regulatory change.
Priority actions for executive teams in 2026
- Re-evaluate supplier qualification timelines: build six- to twelve-month cushions for first-article approvals when qualifying alternate high-purity solvent and resin suppliers.
- Invest in regulatory-forward R&D: accelerate development of non-fluorinated or low-PFAS photoacid chemistries and build customer acceptance plans before hard mandates appear.
- Pursue strategic capacity partnerships: where capital intensity is high, consider JVs, capacity reservation agreements or local tolling arrangements to secure supply without full greenfield exposure.
- Operationalize purity and analytics: upgrade in-house impurity analytics and in-process monitoring to reduce qualification friction and support faster crash-repair during contamination events.
- Embed concentration risk into commercial planning: use supplier concentration metrics in pricing, inventory and renegotiation strategies to avoid single-source dependency shocks.
Case signals to watch in 2026 — leading indicators of structural change
- New site and capacity announcements by major suppliers and their pace of commissioning — these indicate where lead times and qualification friction will ease or persist.
- JV formations and regional operational setups near major fab clusters — these reveal supplier prioritization of localized supply models.
- Public movements on PFAS policy and state-level restriction timelines — they will materially affect reformulation urgency and contract terms.
- Customer trade-off decisions between cost, time-to-qualify and chemical performance — these will drive which chemistries scale and which become niche.
PW Consulting’s Special Electronic Chemicals For Photoresist Market study is designed to move beyond descriptive market commentary to provide executable intelligence for 2026 decision cycles. We present a clear synthesis of macro growth, supplier behavior and regulatory pressure — while retaining the proprietary, subsegment-level modeling and supplier scorecards that are essential to transactional and operational decisions. In this executive summary we have intentionally presented the high-value strategic insights and withheld detailed subsegment tables and granular regional/application splits to preserve the exclusive, actionable analytics contained in the full report.
For access to the full dataset, supplier scorecards, scenario models and operational toolkits — including the proprietary subsegment forecasts and regional/application breakdowns — visit the PW Consulting report page or contact our advisory team to request a briefing and licensing options. PW Consulting’s industry practitioners stand ready to support M&A diligence, procurement redesign, and regulatory contingency planning backed by the report’s empirical models and supplier-level intelligence.
For detailed analysis of this topic, please visit the official page: Special Electronic Chemicals For Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com