

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop Cloud Terminal Market Set to Expand at a 4.98% CAGR Through 2032, Report Finds

Desktop Cloud Terminal Market — Strategic Imperatives for 2026 Decision-Makers
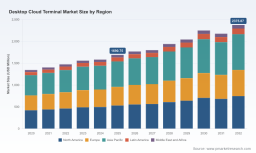
PW Consulting today releases its authoritative Desktop Cloud Terminal Market briefing, tailored for CXOs, IT procurement leads and strategy teams preparing decisions in 2026. The global market for desktop cloud terminals has moved decisively from niche consolidation to broad enterprise adoption: by our accounting the market reached roughly USD 1.69 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 4.98% through the forecast window, driving the market toward roughly USD 2.38 billion by 2032. This report is crafted as a practical playbook — it surfaces the strategic inflection points, vendor dynamics and execution risks that will determine winners and losers next year, while reserving the granular segment-level datapacks for subscribers of the full study.
Desktop Cloud Terminal Market
Why 2026 Is a Pivotal Year
Several converging forces make 2026 an inflection year for desktop cloud terminals:
Desktop Cloud Terminal Market
- Cloud-native desktop adoption is broadening beyond early adopters. Organizations that pursued hybrid work during the pandemic are now revalidating long-term endpoint architectures under cost, security and sustainability constraints.
- Security frameworks such as zero-trust mandates and data-governance regulation are translating into specific procurement requirements for cloud endpoints and the clouds that host them.
- Data center economics are changing: rising energy costs tied to AI workloads are altering the total cost of ownership calculus for hosted desktop estates.
- Geopolitical trade controls and supply-chain constraints are forcing multinationals to rethink vendor sourcing and regional deployment models.
Each of these dynamics elevates the desktop cloud terminal from a commodity peripheral to a strategic technology choice that touches security, procurement, real estate and sustainability agendas.
Desktop Cloud Terminal Market
What the PW Consulting Report Delivers (Practical, Actionable)
The study is designed to move teams from high-level interest to executable decisions. Key deliverables include:
- Top-line market sizing and a transparent forecasting model covering 2026–2032, with scenario sensitivity to energy prices, regulatory constraints and DaaS adoption curves.
- Outcome-focused migration roadmaps — from pilot to scale — including templates for phased device refresh, service-level objectives (SLOs) and change-management milestones.
- A procurement playbook: RFP templates, evaluation scorecards and negotiation levers tailored to combinations of hardware vendors, hypervisor/platform partners and DaaS operators.
- TCO and ROI frameworks that fold in device CAPEX, lifecycle management, remote support costs, network and cloud hosting fees, plus sustainability metrics for enterprise ESG reporting.
- Risk heatmaps and contingency planning modules that quantify exposure to supply-chain disruption, export-control regimes and localized data-sovereignty requirements.
- Vendor benchmarking and competitive profiles (executive-level) that highlight strategic positioning, technical differentiators, go-to-market partnerships and recent product or certification moves.
- Strategic scenario analyses (three high-probability trajectories) to stress-test vendor selection and capacity planning decisions.
We deliberately present this output as a “trailer”: practical tools and frameworks that empower in-house teams to act now, while detailed segment matrices and the interactive model are securely accessible in the full report package.
Competitive Landscape: Who Matters and Why
The competitive field is composed of established PC OEMs, specialized thin/zero-client manufacturers and software-centric endpoint providers. Market concentration is moderate: the leading three firms account for roughly 42% of market volume, while the top five approach the mid-50s in aggregate share — a structure that combines scale advantages with room for niche and software-enabled challengers.
- Dell Technologies (Round Rock, Texas) — Strengths: broad channel footprint, Wyse portfolio optimized for Citrix, VMware Horizon and Microsoft Azure Virtual Desktop. Strategic posture: deep integration with enterprise IT stacks and multi-monitor, hybrid-work features. Recent move: launched a Wyse model in late 2025 with enhanced Windows 365 Cloud PC support and multi-display capabilities, signaling focus on DaaS compatibility.
- HP Inc. (Palo Alto, California) — Strengths: mature thin client line-up and enterprise services. Strategic posture: certification-led interoperability; delivers reliable endpoints for large-scale VDI and government deployments. Recent move: certification and compatibility updates with Citrix Horizon and Azure Virtual Desktop in late 2025, reflecting a defensive strategy built on platform trust.
- Lenovo Group (Beijing / Morrisville) — Strengths: leverages PC engineering for compact, cost-efficient thin clients and edge devices. Strategic posture: commodity-hardening with compute refresh (e.g., Ryzen-based models) to close performance gaps and appeal to performance-sensitive VDI workloads.
- IGEL Technology (Reading, UK) — Strengths: software-led differentiation through a secure, lightweight OS for cloud endpoints. Strategic posture: positioning as the secure, manageable endpoint layer with rapid protocol updates. Recent move: shipped a major OS iteration mid-2025 with native support for emerging cloud desktop protocols and zero-trust capabilities.
- 10ZiG Technology (Bristol, UK) — Strengths: specialist zero- and thin-client hardware with broad protocol support (PCoIP, Blast, RDP). Strategic posture: targeted vertical playbooks and deep VDI protocol optimization.
- Huawei Technologies (Shenzhen, China) — Strengths: strong regional presence and integrated cloud-desktop solutions compatible with local enterprise deployments. Strategic posture: competing on integrated stacks where regulatory alignment enables adoption.
- Acer (New Taipei City, Taiwan) — Strengths: value-oriented hardware and channel reach in SMB and education segments. Strategic posture: cost-effective endpoints for large-scale rollouts where price per seat remains a primary decision driver.
Across the vendor set, differentiation is amplifying along two axes: software and partnerships. Firms that pair compact hardware with a robust endpoint OS, lifecycle management and certified integrations with hyperscalers gain meaningful procurement leverage. Conversely, hardware-centric suppliers are pursuing performance upgrades and platform certifications to defend installed bases.
Regulatory, Energy and Geopolitical Headwinds
Decision-makers must plan against three non-negotiable constraints:
- Data governance and sovereignty rules — mandates in key jurisdictions require control over where and how desktop images and user data are stored and processed, creating compliance overlays for cross-border designs.
- Zero-trust and endpoint security standards — public sector and regulated firms increasingly require adherence to formal maturity models, effectively raising the bar for acceptable endpoint configurations.
- Supply-chain and export-control risks — controls on advanced compute hardware and regional supplier constraints introduce sourcing risk that can change lead times and component availability within months.
Layered on top, rising data-center energy costs—driven in part by AI workloads—alter hosted-desktop economics. Our models show sensitivity: modest increases in hosting OPEX can materially change the break-even horizon for migrating to a fully cloud-hosted desktop estate versus hybrid models.
Actionable Recommendations for 2026
PW Consulting’s operative advice for 2026 centers on a dual agenda: secure short-term wins and build optionality for disruptive shifts.
- Run targeted pilot programs that pair at least two hardware form factors with two software stacks (a hyperscaler DaaS + an on-prem VDI) to collect real performance and support-cost telemetry before committing at scale.
- Require vendor interoperability evidence as a gating criterion: certifications, independent lab results, and third-party reference sites that reflect your stack (hypervisor, protocol, identity provider).
- Embed security and compliance requirements into RFPs, including zero-trust alignment, patch cadence SLAs and supply-chain provenance clauses.
- Negotiate commercial terms that align incentives: volume-linked refresh credits, cloud-hosting discounts and warranty + remote-management bundles to reduce lifecycle support expenses.
- Quantify sustainability impact in procurement decisions: include energy consumption per seat and expected lifetime carbon metrics in vendor scoring to align with ESG goals.
- Develop a contingency sourcing plan that maps alternative suppliers and supports staged flexibility, mitigating risk from export controls or regional restrictions.
- Consider software-first contracts: where possible, separate hardware and software contracts to avoid vendor lock-in and preserve upgrade flexibility as protocols and security needs evolve.
How to Use This Study
PW Consulting designed this report for three archetypal users:
- Enterprise CIO/CTO teams who need a roadmap to replace legacy desktops while balancing security and cost pressures.
- Procurement and vendor management leaders seeking proven RFP templates, scoring methodologies and negotiation levers.
- Corporate strategy and M&A teams scanning the supplier landscape for consolidation targets or partnership opportunities supported by validated market sizing and concentration metrics.
The public briefing above highlights the most consequential insights and decision levers. The full PW Consulting Desktop Cloud Terminal Market report contains the detailed models, downloadable TCO calculators, vendor scorecards and the segmentation datasets that enterprise teams rely on when writing contracts and budgets. Those detailed spreadsheets and the interactive scenario model are available only in the subscriber package — intentionally withheld here to ensure readers engage directly with the full research platform and its validation materials.
Next Steps
For teams mapping 2026 budgets and 3–5 year endpoint strategies, our recommendation is simple: use the next 60–90 days to set a strategic working group with representation from IT ops, security, procurement and finance. Deploy the study’s pilot checklist, run at least one multivendor proof-of-concept and use the PW Consulting scorecard to convert qualitative vendor claims into quantitative procurement outcomes.
PW Consulting stands ready to brief executive teams and run bespoke workshops to apply these findings to your unique estate and risk profile. The full report, interactive financial models and the complete vendor benchmark pack can be accessed through PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Desktop Cloud Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com