

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Electronic Grade Adhesives Market to Rise from USD 6,380.0M (2025) to USD 9,797.7M by 2032 at 6.32% CAGR — Asia‑Pacific Leads with USD 3,522.3M

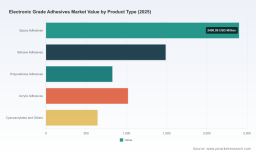
Electronic Grade Adhesives Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Electronic Grade Adhesives frames a pragmatic, execution-oriented roadmap for executives planning investments, sourcing, and product development across the electronics and semiconductor value chain in 2026. The report synthesizes historical performance (2020–2025), delivers a seven-year forecast (2026–2032) and translates technical, regulatory and supply-side signals into concrete strategic options — while reserving the detailed segment tables and proprietary supplier scoring for readers who access the full report.
Electronic Grade Adhesives Market
Why this report matters in 2026
- Actionable market sizing anchored to a 2025 base-year: the electronic-grade adhesives market reached approximately USD 6,380 Million in 2025 after steady expansion from 2020. Our topline historical series (2020–2025) and forward-looking model project continued expansion through 2032, reaching roughly USD 9,798 Million by 2032 under a core-case CAGR of 6.32% for the forecast period.
- Decision focus: Procurement managers, product leaders, and M&A teams need to convert material science trends and regulatory shifts into supply-chain design, portfolio pivots, and capital deployment plans. This study translates technical drivers — from underfill reliability to thermal interface innovation — into investment-ready hypotheses for 2026 action.
- “Trailer” approach to intelligence: we reveal the market architecture, competitive dynamics, cost drivers and risk scenarios to establish credibility, but hold detailed subsegment shares, price curves, and our proprietary supplier-score matrices behind the report gateway to incentivize direct engagement.
Topline market dynamics and what they imply
The adhesives market serving electronics and semiconductor packaging has shown resilient growth across recent cycles. From a market base of around USD 4,832 Million in 2020, the sector expanded to approximately USD 6,380 Million by 2025. Our forecast anticipates continued steady growth, driven by semiconductor packaging complexity, miniaturization of consumer devices, electrification in automotive and broader industrial digitization.
Electronic Grade Adhesives Market
Key implications for executives in 2026:
Electronic Grade Adhesives Market
- Capacity planning must assume sustained mid-single-digit growth: the 6.32% CAGR embedded in our core forecast implies steady demand for both commodity and differentiated adhesive formulations.
- Product roadmaps should prioritize thermal management and reliability-grade chemistries: higher power-densities and fine-pitch assemblies put premium on thermally conductive, low-outgassing, and lead-free formulations.
- Supply security and cost pass-through deserve renewed attention: raw-material volatility and regional regulatory shifts materially affect formulations, throughput and qualification cycles.
Raw materials, regulation and cost pressure — the operational triangle
Three supply-side forces are shaping strategy windows in 2026:
- Raw-material price dynamics. Northeast Asia and European epoxy resin markets have seen firmer price points in early 2026, reflecting tightness in feedstocks such as bisphenol A and epichlorohydrin and persistent demand from electrical laminates and electronics segments. These movements create a two-speed margin environment: commodity epoxies under pressure, while specialty halogen-free and low-impurity grades command premium pricing.
- Regulatory impetus. Continued regulatory scrutiny — notably the EU REACH classification pathway for bisphenol A as an SVHC — is accelerating formulation shifts toward low-impurity and halogen-free epoxy systems for electronics. For companies selling into EU and global OEMs that adopt REACH-aligned specifications, reformulation timelines are now a procurement and qualification priority for 2026.
- Trade and supply policy. Recent determinations affecting cross-border resin flows have altered near-term sourcing strategies. While some trade remedies were not sustained in early rulings, the interpretive uncertainty has led many manufacturers to diversify supplier lists and vertically secure key intermediates.
What the report provides — practical, executable content
This study is intentionally operational. It is built for executives who must act fast and pragmatically on partial information. Deliverables include:
- Top-down and bottom-up market sizing with scenario variants (baseline, upside, downside) calibrated to technology adoption and macro inputs.
- Seven-year forecast (2026–2032) with sensitivity testing to raw material price paths, regional demand shocks and packaging technology shifts.
- Vendor scorecards and go-to-market playbooks evaluating technical capabilities, channel strategies, geographic footprint and vertical focus. (Note: full scorecards and scoring weights are provided in the full report.)
- Operational playbooks covering qualification timelines, sample economics, and process replication protocols to accelerate application engineering cycles in high-reliability markets.
- Procurement tools: a supplier-risk heatmap, contract language templates for raw-material pass-through, and a six-month cost-monitoring cadence tailored to adhesives buyers.
Competitive landscape — who matters and why
The market exhibits moderate concentration: our concentration metrics indicate that the top three suppliers account for a significant, but not dominant, share (CR3 ~36.5%), while the top five represent close to half of the market (CR5 ~49.1%). This structure creates space for global leaders to leverage scale while enabling medium-sized specialists to capture niche, high-margin pockets related to advanced packaging and light-curable systems.
- Henkel AG & Co. KGaA (Düsseldorf) — A leading integrated supplier with a broad portfolio across underfills, die attach adhesives and thermal materials. Recent factory and lab investments (including expansion of application engineering facilities) reinforce Henkel’s strategy of coupling material innovation with on-site process replication for OEMs and OSATs.
- 3M Company (St. Paul) — Strong in structural and fast-curing systems, with a growing distribution footprint via channel partnerships. 3M’s focus on thermal stability and fast-cure chemistries aligns with OEM demand for accelerated production and miniaturization.
- Dow Inc. (Midland) — Notable for silicone-based systems that serve harsh-environment and display applications. Dow’s DOWSIL line remains relevant where primerless adhesion and environmental resilience are required.
- H.B. Fuller, Sika, Momentive, Wacker, Shin-Etsu — Regional and global players offering complementary portfolios for PCB protection, sensor sealing and thermal management; many pursue targeted M&A and application-engineering expansion to capture automotive and industrial electronics growth.
- Dymax, DELO, YINCAE, NAMICS — Specialist suppliers focused on light-curable systems, precision bonding and advanced underfills for fine-pitch semiconductor packaging. These firms are primary beneficiaries of high-reliability packaging trends.
- Huntsman — A key epoxy-resin and formulated-system supplier, particularly relevant for encapsulants and potting compounds used in high-performance electronics.
Recent corporate moves highlight two strategic themes: (1) closer proximity to customers via R&D and application labs (e.g., new R&D centers and lab expansions) to shorten qualification cycles; (2) channel and distribution agreements to accelerate aftermarket reach and small-batch production adoption. Examples include new R&D activities in Silicon Valley, multiple lab expansions in Southeast Asia, and distribution partnerships that broaden access to specialty formulations.
Risks, blindspots and what to hedge in 2026
- Material availability and price volatility: maintain dual-sourcing and examinate backward-integration where feedstock exposure is material to unit economics.
- Regulatory compliance and reformulation risk: accelerate REACH-aligned reformulation workstreams if selling into or through European OEMs; anticipate extended qualification windows.
- Qualification lead times: procurement and product teams must account for multi-stage testing (thermal cycling, drop, moisture sensitivity) when planning product launches — schedule slippage remains the most common execution failure.
- Technology displacement: light-curable and novel thermally conductive adhesives are adoption risks to legacy epoxies; targeted product development and selective partnerships can mitigate loss of share.
Strategic recommendations for 2026
- Prioritize supplier relationships that provide co-development and on-site process replication capabilities — the ability to qualify adhesives within a customer’s assembly environment is a competitive differentiator.
- Execute a two-track portfolio strategy: protect commodity-margin through scale efficiencies while selectively investing in premium formulations for thermal management and fine-pitch packaging.
- Use procurement contracts to transfer active raw-material risks and to secure capacity for critical intermediates during project qualification phases.
- Accelerate targeted partnerships with equipment and materials specialists to shorten qualification cycles for light-curable and low-outgassing systems used in high-density assemblies.
Next steps — where to get the full intelligence
PW Consulting’s Electronic Grade Adhesives Market report is designed as a decision engine for 2026. The full dossier includes detailed subsegment tables, regional and application splits, price models, proprietary supplier-scorecards, and downloadable procurement templates that are intentionally withheld from this preview. For teams building sourcing strategies, technical roadmaps, or M&A theses this year, the full report converts the themes above into executable workplans and model-ready inputs.
Visit the PW Consulting report page to access the complete dataset, supplier heatmaps and our interactive scenario model. PW Consulting’s analysts are available to conduct tailored briefings and walk-throughs for procurement, R&D and corporate development teams preparing for 2026 execution.
For detailed analysis of this topic, please visit the official page: Electronic Grade Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com