

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recycled Rare Earth Market Poised for Rapid Growth — 12.7% CAGR Signals Major Investment Opportunity

PW Consulting: Recycled Rare Earth Market — Strategic Brief for 2026 Decision-Makers
Executive Snapshot
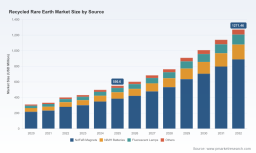
As decarbonization, electrification, and onshoring policies reshape critical material supply chains, recycled rare earths are rapidly moving from niche sustainability projects to core components of commercial strategy. PW Consulting’s new Recycled Rare Earth Market report — based on a rigorous base year of 2025 and a forecast horizon through 2032 — captures this transition with a practical, decision-oriented lens. Our analysis shows the recycled rare earth market expanding from roughly USD 550.6 Million in 2025 at a compound annual growth rate (CAGR) of 12.7%, with a projection that it will cross the USD 1.2 billion threshold by 2032. For corporate leaders planning capital, sourcing, or product strategy in 2026, this is not a theoretical trend: it is a fast‑moving commercial frontier.
Recycled Rare Earth Market
Why 2026 Is a Turning Point
Policy and commercial signals that crystallized in 2024–2025 continue to set the stage for near-term market reconfiguration. Export controls and secondary‑resource regulations introduced by major producing countries, paired with tariff measures and procurement preferences in importing markets, are creating both supply disruption risk and commercial windows for domestic recycling and closed‑loop supply models. Meanwhile, OEM commitments and new recycling facilities are converting pilot‑scale demonstrations into predictable supply streams.
Recycled Rare Earth Market
For executive teams that must decide in 2026 whether to build, buy, or partner for recycled rare earth feedstock, the margin for error is narrowing. Our report turns that narrowing window into actionable options—identifying where near-term investments can convert into medium‑term strategic advantage, and where tactical partnerships are the lower‑risk route to access recycled REEs.
Recycled Rare Earth Market
Market Trajectory — What the Numbers Signal
-
Historic momentum: The market more than doubled in the 2020–2025 period, evidence of accelerating collection, processing innovation, and commercial acceptance.
-
Sustained growth outlook: A projected CAGR of 12.7% across the 2026–2032 forecast period supports the business case for capacity build‑outs and long‑term offtake contracts.
-
Scale inflection ahead: Our scenario work highlights a transition from fragmented pilot capacity in 2025 to industrial‑scale hubs by the late 2020s — a structural shift that will alter sourcing economics and supplier bargaining power.
Key Demand and Supply Drivers
-
Demand pull from electrification and high-performance magnets: Continued adoption of high‑energy permanent magnets across EV powertrains, wind turbines, and industrial motors underpins long‑term material demand.
-
Policy accelerants: Tariffs, strategic procurement, and export controls are incentivizing domestic recycling and alternative supply chains in several consuming nations. These measures are driving investment decisions in recycling capacity and influencing siting choices.
-
Cost and circularity: Improved hydrometallurgical and short‑loop magnet‑to‑magnet processes are reducing the economic gap with primary production and creating attractive total‑cost propositions for manufacturers seeking secure, lower‑carbon feedstock.
-
Collection and logistics constraints: The pace of scaling recycled rare earths will be constrained by collection streams, disassembly logistics, and reverse‑supply‑chain economics unless coordinated collection programs and standardized material specifications are implemented.
Competitive Landscape — Who Matters and Why
The competitive field is heterogeneous, comprising technology innovators, integrated processors, and specialist recyclers. These actors are pursuing differentiated paths — short‑loop magnet-to-magnet recycling, mixed rare earth oxide (MREO) production, and pre‑processing services that feed larger refining facilities. Key participants we analyze in the report include both established metals recyclers and new entrants building industrial hubs.
-
Cyclic Materials (Toronto) — Operating North America’s first facility producing recycled MREO from end‑of‑life magnets and expanding to a larger campus in the U.S., Cyclic is a textbook example of an operator scaling proprietary hydrometallurgical routes into hub‑and‑spoke processing networks.
-
MP Materials Corp. (USA) — An integrated rare earth producer implementing commercial‑scale magnet recycling to create closed‑loop supply for permanent magnets; their model illustrates integration from feedstock recycling to magnet manufacturing and strategic OEM collaborations.
-
American Resources Corporation (via Electrified Materials) — Expanding pre‑processing capabilities domestically to aggregate manufacturing scrap and end‑of‑life magnet materials, positioning itself as a key aggregator for downstream processors.
-
Hitachi Metals — A legacy materials firm applying proprietary magnet recycling methods, demonstrating how incumbent OEM suppliers can adapt manufacturing capabilities into circular supply offers.
-
HyProMag / Mkango — Advancing hydrogen processing and short‑loop magnet refurbishment at scale, representing an alternative pathway that preserves magnetic properties with a lower material footprint.
-
Specialists and regional recyclers (e.g., Geomega, Umicore, Accurec, REEcycle, Carester) — A mix of technology developers and service providers that will be critical to regional supply resilience and niche processing requirements.
Our competitive analysis does more than name players: the report maps capabilities to commercial needs (feedstock aggregation, metallurgical conversion, magnet remanufacture, regulatory compliance), and assesses where partnership, equity investment, or offtake contracting can unlock faster access to recycled feedstock.
Regulatory and Geopolitical Considerations
-
Export controls and secondary‑resource regulations from major producing countries have raised both the strategic importance and near‑term uncertainty of cross‑border supply. Policymakers’ moves to protect technologies and materials create arbitrage opportunities for onshore recyclers but also increase compliance burdens for downstream users sourcing global feedstock.
-
Tariff regimes and procurement preferences in key consuming markets are likely to favor domestically processed recycled material and may shorten the time horizon for commercially viable domestic recycling projects.
-
Companies must therefore embed regulatory scenario planning in commercial decisions, using multi‑jurisdictional compliance frameworks and traceability systems to avoid disruptions and preserve market access.
Practical Strategic Recommendations for 2026 Decisions
PW Consulting translates market signals into a sequenced set of actions for corporate leaders. Below are the pragmatic levers we recommend prioritizing in 2026:
-
Secure optionality through layered contracts: Combine short‑term offtake with staged capacity commitments. Where capex is uncertain, prefer anchor offtakes with staggered startup milestones tied to feedstock quality and traceability metrics.
-
Fast‑track feedstock aggregation partnerships: Work with scrappers, OEMs, and electronics recyclers to standardize disassembly and packaging specifications to increase feedstock yield and predictability.
-
Prioritize technology and process diligence: Conduct metallurgical piloting and head‑to‑tail lifecycle assessments before committing to large capital projects; evaluate both hydromet and hydrogen‑based short‑loop solutions against quality and energy intensity metrics.
-
Map regulatory scenarios to investment triggers: Build decision trees that link regulatory shifts to go/no‑go capital triggers and contractual flex provisions.
-
Use modular capacity strategies: Favor hub‑and‑spoke or scalable modular facilities to manage collection variability and reduce stranded asset risk.
-
Embed traceability and ESG KPIs: Recycled rare earths’ commercial premium will depend on auditable claims for origin, carbon footprint, and circularity—build those capabilities into early contracts and reporting systems.
What the Report Delivers — Practical, Not Theoretical
PW Consulting’s Recycled Rare Earth Market report is designed for executives making 12–36 month deployment decisions. The deliverables include:
-
A dynamic market model calibrated to 2025 base year inputs and multiple 2026–2032 scenarios, enabling custom sensitivity runs for price, feedstock availability, and policy shifts.
-
Supplier and technology scorecards that evaluate process maturity, throughput scalability, capital intensity, and ESG metrics — presented as decision matrices to support build vs. partner choices.
-
Operational playbooks for feedstock collection programs, reverse logistics, and pre‑processing specifications to improve recovered rare earth yield and reduce processing variability.
-
Commercial contracting templates and offtake structures tailored to recycled material characteristics, including quality bands, acceptance testing, and escalation clauses tied to regulatory outcomes.
-
Investment prioritization and M&A frameworks to identify high‑value acquisition targets, minority equity partnership structures, and earn‑out mechanics that align incentives across the circular value chain.
-
Regulatory impact maps and compliance checklists for multi‑jurisdictional sourcing strategies, including traceability requirements and risk‑mitigation tactics for export control events.
Next Steps — How to Use This Intelligence in 2026
Decision-makers should treat recycled rare earths not as an optional green premium but as a strategic resource class requiring the same rigor applied to primary sourcing: scenario‑based planning, contractual staging, technology validation, and regulatory hedging. In 2026, companies that align procurement, R&D, and public affairs around a coherent recycled‑REE strategy will secure both supply resilience and potential cost and carbon advantages as the market scales.
Access the Full Report
This release is a strategic summary intended to demonstrate the report’s practical value. For the full dataset, segmented modelling, supplier heatmaps, and downloadable commercial templates, PW Consulting invites stakeholders to access the complete Recycled Rare Earth Market report on our website. Our client services team is also available for bespoke briefings, scenario workshops, and transaction support to convert market insight into executable deals.
PW Consulting — actionable intelligence for leaders building the circular critical‑materials economy.
For detailed analysis of this topic, please visit the official page: Recycled Rare Earth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com