

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Head Lice Infestation Drug Market to Reach USD 474M by 2032
By pmarketresearch, 2026-07-13
Head Lice Infestation Drug Market: Strategic Imperatives for 2026
Executive summary
As the Head Lice Infestation Drug market moves into 2026, executive teams face a compact but structurally dynamic landscape. Our analysis at PW Consulting shows the market expanded steadily through the 2020–2025 base period, and at a compound annual growth rate (CAGR) of 5.5% it is forecast to continue expanding across the 2026–2032 planning horizon. This growth trajectory—underpinned by recurrent treatment demand, episodic outbreaks tied to school and community cycles, and evolving product innovation—creates a window for both incumbent optimization and new entrant disruption.
Head Lice Infestation Drug Market
From a strategic perspective, three structural features define near-term opportunity and risk: predictable recurring demand, product-level commoditization pressure as patent cliffs approach, and an asymmetric reimbursement and regulatory environment that favors certain commercial strategies. The full report (base year 2025; forecast 2026–2032) translates these dynamics into decision-grade intelligence for pricing, portfolio, supply chain, and M&A planning.
Head Lice Infestation Drug Market
Why this matters for 2026 decision-makers
- Timing around patent expiries: Several high-impact assets face patent expirations in the next 18–24 months. This compresses the runway for premium pricing and elevates the importance of lifecycle extensions, formulation patents, and brand equity investments in 2026.
- Channel economics and reimbursement gaps: The market is dominated by a mix of OTC and prescription offerings, with prescription products largely outside Medicare/Medicaid coverage. For 2026, go-to-market choices (OTC switch, pharmacy distribution, DTC education) will materially affect net realized price and volume.
- Resistance and efficacy differentiation: Differentiated mechanisms of action—particularly those with ovicidal activity—are driving clinical and commercial preference in key cohorts. Where resistance profiles remain favorable, those assets warrant prioritized support and territorial protection.
- Consolidation window: Market concentration is moderate but meaningful; the top three and five firms account for a sizable share of market revenue. That concentration creates both room for bolt-on M&A and the need for incumbents to defend share through efficiency and targeted innovation.
What the report delivers (practical, executable content)
- Market sizing and validated growth scenarios (historical 2020–2025, base 2025, modeled 2026–2032), with sensitivity testing across epidemiological, pricing, and reimbursement variables.
- Commercial playbooks: SKU rationalization, retail vs. pharmacy channel models, promotional impact ladders, and unit economics templates for OTC vs. prescription pathways.
- Regulatory and patent heat maps that prioritize jurisdictions and assets for life-cycle management or defensive filings.
- Supply chain risk register and mitigation options, including raw-material concentration analyses and secondary-sourcing feasibility for critical actives.
- M&A & partnership blueprint: target screening criteria, valuation ranges under multiple scenarios, and integration checklists focused on speed-to-market for newly launched therapeutic formats.
- Competitive response playbooks for the generic-entry phase—pricing corridors, bundling and loyalty tactics, and over-the-counter differentiation strategies.
- Implementation dashboards and KPI templates to translate strategy into 90/180/360-day action plans.
Competitive landscape — who matters and why
Competition is a mix of specialty pharma, branded over-the-counter incumbents, and regional players with strong retail relationships. In practical terms, companies that combine credible clinical differentiation, pharmacy distribution muscle, and cost-efficient manufacturing will hold disproportionate advantage in 2026.
Head Lice Infestation Drug Market
- Arbor Pharmaceuticals (Sklice, ivermectin lotion) — Positioned with a differentiated single-application format and broad age labeling, Sklice’s route to OTC acceptance and the timing of its patent life are central strategic levers. The coming patent expiry window elevates the need for formulation patents, post-marketing evidence, and branded loyalty programs before generic entrants accelerate downward price pressure.
- Cipher Pharmaceuticals (Natroba, spinosad suspension) — Spinosad’s biologically-derived ovicidal activity and nit-combing independence are strong clinical selling points for pediatric caregivers. Cipher’s priority is maintaining supply-chain security for the bacterial-derived active and defending clinical positioning through head-to-head real-world evidence and educational campaigns.
- Taro Pharmaceuticals (Ovide, malathion lotion) — As a prescription asset with a favorable resistance profile, malathion occupies an important clinical niche. Taro’s commercial strategy should emphasize prescriber education, formulary positioning where applicable, and leveraging the resistance advantage in geo-targeted outbreaks.
- Oystershell NV (RID lines) — With OTC pyrethrins/piperonyl butoxide formulations and active clinical trial programs, Oystershell illustrates the classic retail-to-clinic feedback loop: OTC penetration can be amplified by contemporary safety and efficacy data. Their recent recruiting-stage trial indicates active pipeline investment toward reinforcing label claims.
- Prestige Brands (Nix, permethrin) — A legacy OTC brand with extensive retail shelf presence, Nix’s strengths lie in brand recognition and multi-channel distribution. The strategic questions for 2026 center on packaging innovation, consumer education to reduce repeat-dose failures, and defensive promotional tactics as price competition intensifies.
- Azurity Pharmaceuticals — As parent of Arbor and a platform for anti-parasitic offerings, Azurity is well positioned to orchestrate portfolio-level lifecycle plays, including line extensions or co-promotions that preserve value ahead of generic entries.
- Sanofi — With historical involvement in pediculicide commercialization, Sanofi’s role is less about volume leadership and more about potential strategic options—co-promotion, licensing, or targeted R&D collaborations leveraging existing regulatory expertise.
Recent developments and regulatory/reimbursement dynamics
- Clinical development: As of mid-2025, Oystershell initiated a recruiting-phase trial comparing pyrethrin-based formulations—an indicator that clinical reinforcement remains a live, value-driving activity for OTC players.
- Reimbursement gaps: Several prescription pediculicides are not covered by major public payers in key markets. This asymmetry favors OTC pathways for market expansion but also makes out-of-pocket affordability a recurring barrier in price-sensitive cohorts.
- Patent timing: Key patents covering some commercially important lotions are set to expire within the next 12–24 months; this shifts 2026 planning from growth-through-innovation to growth-through-defensibility—patent, brand, and channel.
- Mechanism and resistance: Assets with ovicidal activity or novel mechanisms (e.g., spinosad-derived formulations) are commanding clinical preference in pediatric segments, while malathion currently presents the strongest resistance profile among prescription options.
- Regulatory practice: Standard treatment algorithms and no-nit policies remain in place for several established actives, with recommended repeat applications for certain non-ovicidal chemistries—an operational reality that shapes packaging, labeling, and patient adherence interventions.
Strategic playbook for 2026
To convert market growth into durable share gains, companies must orchestrate a multi-dimensional program that balances short-term revenue protection with medium-term structural positioning. Key actions for 2026 include:
- Pre-generic preparation: Map out three defensive tracks—(1) regulatory and formulation patents; (2) rapid SKU and packaging refreshes that raise switching costs; and (3) focused loyalty campaigns tied to caregiver education.
- Channel optimization: Reassess the OTC vs. prescription mix by geography and cohort. In markets where public reimbursement is absent, consider value-priced bundles, subscription programs for recurrent infestations, and retail partnerships to maintain margins.
- Clinical and real-world evidence: Invest selectively in trials that close gaps for safety, ovicidal claims, or ease-of-use advantages. Positioning based on demonstrated fewer repeat treatments or better ovicidal performance can justify premium price positioning even after generics enter.
- M&A and partnership play: Pursue bolt-ons that add manufacturing redundancy for key actives or acquire brands with strong retail positioning to accelerate shelf-share defenses before price erosion intensifies.
- Supply chain fortification: Secure secondary sources for biologically derived actives, qualify contract manufacturers for rapid capacity scaling, and stress-test logistics against seasonal demand spikes tied to school calendars.
- Regulatory and payer engagement: Build dossier-ready materials to pursue favorable listing or reimbursement where feasible, and design pragmatic co-pay support or patient-assistance programs to sustain adherence in uncovered cohorts.
What we do not disclose here—and why you need the full report
This introduction intentionally demonstrates the analytic depth and strategic line-of-sight available in PW Consulting’s Head Lice Infestation Drug Market study while withholding granular segment-level data and proprietary revenue breakdowns. Detailed regional and application splits, SKU-level price elasticity matrices, modeled scenarios by channel, and the full list of prioritized acquisition targets are reserved for the complete report and subscriber portal. That level of granularity is essential to operationalize the recommendations above and to stress-test any acquisition or launch decision.
Next steps for executives
If your 2026 planning cycle includes portfolio rationalization, M&A, pricing resets, or a move to OTC strategy, now is the time to translate market-level momentum into executable plans. PW Consulting’s full report provides the playbooks, templates, and transaction-ready analysis required to compress decision timelines and reduce execution risk.
Contact PW Consulting for access to the full Head Lice Infestation Drug Market study, the detailed financial models, and a bespoke briefing tailored to your portfolio and strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Head Lice Infestation Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chlorine Dioxide Generator Market Poised for 3.26% CAGR
By pmarketresearch, 2026-07-13
Chlorine Dioxide Generator Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present a forward-looking briefing designed to crystallize the strategic choices facing executives, investors, and product teams entering the chlorine dioxide (ClO2) generator and service market in 2026. This preview surfaces the actionable themes, competitive signals, regulatory inflection points, and operational levers that will determine winners and laggards — while preserving the granular segmentation and proprietary models in our full study to encourage direct engagement with the source report.
Chlorine Dioxide (Chlorine Dioxide Generator) Market
Why this market matters to corporate strategy in 2026
Chlorine dioxide technologies occupy an increasingly influential position across sterilization, water treatment, and industrial hygiene. After steady growth through the early 2020s, the market reached a meaningful scale by our base year (2025) and is forecast to continue expanding through our 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 3.26%. The total market progressed from under USD 170 Million in the early 2020s to roughly USD 215 Million by 2025, with near-term uplift to about USD 226 Million in 2026 and an anticipated expansion toward the upper end of the forecast by 2032.
Chlorine Dioxide (Chlorine Dioxide Generator) Market
For executives, that profile implies a market that is neither hyper-growth nor static: it rewards differentiated technologies, validated safety claims, and close regulatory alignment. Strategic moves in 2026 that emphasize validated performance, operational scalability, and regulatory certainty will disproportionately capture the margin-accretive opportunities that exist despite modest headline CAGR.
Chlorine Dioxide (Chlorine Dioxide Generator) Market
Core strategic implications
-
Regulatory credibility is a market maker. Since formal regulatory acceptance — notably FDA acknowledgment of chlorine dioxide for contract sterilization (2021) and subsequent EPA registration of a ClO2 sterilant (2025) — adoption conversations have shifted from “is it acceptable?” to “how can we operationalize it with validated processes?” Companies that can demonstrate validated residuals, robust validation protocols, and documented 510(k) support will unlock premium adoption among medical device OEMs and contract sterilizers.
-
Validation and clinical-grade evidence drive price differentiation. Recent peer-reviewed studies (published by major providers in early and mid-2026) that document sterilization efficacy and minimal residual toxicity are pivotal. Buyers in regulated sectors — medical devices, hospitals, and certain food segments — will pay for validated processes that reduce regulatory friction and shorten time-to-market.
-
Scale and capacity expansions are tangible signals of demand bifurcation. Select contract sterilizers have announced capacity increases in 2024–2026, indicating pockets of high-volume demand and the commercial viability of chlorine dioxide approaches as an EtO alternative. Monitoring capacity investments provides a near-real-time indicator of OEM outsourcing trends and potential consolidation pressure on smaller providers.
-
Market structure favors focused specialists but leaves room for consolidation. The market concentration is low-to-moderate: a fragmented competitive landscape means the top few players do not yet dominate. This structure creates opportunities for both niche leaders (e.g., specialized sterilization services) and acquisitive platforms seeking roll-up scale and standardized validation offerings.
Competitive landscape: what to watch
Two types of competitors are shaping the landscape: specialized service providers that combine proprietary chemistries and process validation, and equipment/system suppliers enabling in-situ generation. Providers who integrated end-to-end validation services and publicized peer-reviewed evidence in 2026 have accelerated buyer confidence. Notable public signals include:
-
ClorDiSys Solutions — a recognized supplier of Pure CD gas sterilization technologies and contract sterilization. Recent peer-reviewed publications (early and mid-2026) that document sterilization viability and residual toxicity testing significantly strengthen the commercial value proposition for device manufacturers seeking EtO alternatives. ClorDiSys’s FDA-registered facility status and its emphasis on validation support position it as a partner of choice for regulated customers pursuing robust 510(k) pathways.
-
Boulder Sterilization — an established contract sterilizer that has incrementally expanded capacity across 2024–2026. Their strategy of offering chlorine dioxide alongside EtO and presenting quick-turn processing for complex devices signals demand from high-mix, time-sensitive OEMs. Capacity additions from Boulder’s divisions provide early evidence of outsourcing momentum and illustrate the operational scaling challenges for incumbent sterilizers.
Collectively, these players illustrate two effective approaches: (1) invest in rigorous science and regulatory positioning to command premium service contracts; (2) scale capacity and operational throughput to serve OEMs with high-volume, time-sensitive needs. Strategic entrants should choose one or combine both with caution and clear capital plans.
Report contents — what the full study delivers
Our complete Chlorine Dioxide Generator Market report is built as a decision-focused playbook, combining quantitative models with practical, executable guidance. Key inclusions are:
- Market sizing and forecast model (base year 2025; forecast 2026–2032) with adjustable scenarios and sensitivity to regulation, adoption velocity, and price movements.
- Demand-side analysis: procurement drivers by buyer cohort (e.g., medical OEMs, contract sterilizers, water utilities, food processors), buying cycles, and validation requirements.
- Supply-side mapping: supplier archetypes, capability matrices (validation, sterilization throughput, automation), and supply chain risk heat maps.
- Technology assessment: comparative analysis of chemical vs electrolytic generation approaches, lifecycle OPEX/CapEx trade-offs, and adoption curves across regulated and non-regulated applications.
- Regulatory playbook: timelines, submission templates, common validation pitfalls, and recommended evidence packages for 510(k) and equivalent pathways.
- Commercial go-to-market playbook: channel strategies, partnership templates for contract sterilizers and OEMs, pricing frameworks, and procurement negotiation levers.
- Scenario-based M&A and partnership model: acquisition targets, integration checklist, and pro forma return scenarios under conservative and accelerated adoption assumptions.
- Operational checklists and vendor scorecards: templates for on-site validation, residual testing, quality systems, and O&M plans for generator deployments.
To respect this preview’s “trailer” remit, we intentionally omit the granular regional and application splits from this summary. The full report contains detailed segmentation, unit economics, and downloadable financial models that unlock those insights for subscribers.
Risk matrix and mitigation tactics for 2026 initiatives
Investment and operational decisions in 2026 should be evaluated against a concise risk framework:
- Regulatory risk: While FDA and EPA actions have been constructive, evolving guidance or differing jurisdictional interpretations can delay projects. Mitigation: invest early in validated residual testing and alignment with region-specific submission requirements.
- Technology selection risk: Chemical and electrolytic generation have distinct operational profiles and cost structures. Mitigation: run pilot installations and life-cycle cost analysis before enterprise-scale rollouts.
- Supply chain and materials risk: Consumable supply disruptions can impact uptime and contractual SLAs. Mitigation: diversify suppliers and establish safety-stock strategies tied to throughput commitments.
- Commercial adoption risk: Conservative buyer procurement cycles in regulated sectors can elongate revenue ramp. Mitigation: secure partnership pilots with contract sterilizers or anchor OEMs to de-risk timelines.
Practical playbook: five near-term actions for leaders
- Prioritize validation-first investments: Allocate R&D and regulatory resources to build peer-reviewed evidence and residual testing data packages. This shortens buyer approval cycles and supports premium positioning.
- Align with contract sterilizers as distribution partners: Instead of only selling equipment, structure partnerships that bundle validation services, turn-key sterilization, and 510(k) support to accelerate market access for device OEMs.
- Model multiple adoption scenarios: Use the report’s scenario tools to stress-test investments under conservative, baseline, and accelerated uptake cases through 2032 — particularly since growth is steady but not explosive.
- Invest in capacity optionality: For service providers, design modular capacity expansions to capture demand surges without committing to upfront excess fixed cost.
- Monitor competitor science and capacity moves closely: Publicized studies and capacity announcements are leading indicators of broader acceptance and potential consolidation; act on these signals decisively.
Conclusion — the 2026 inflection window
The chlorine dioxide generator market in 2026 sits at an inflection between validation-led adoption and operational scaling. With a stable macro trajectory (CAGR ~3.26% across our forecast) and total market size that rose meaningfully by 2025, opportunities favor firms that can combine rigorous scientific validation with flexible operational models. Fragmentation in the competitive landscape creates acquisition and partnership possibilities, while regulatory clarity has made commercial pathways tangible for risk-averse buyers.
PW Consulting’s full study converts these strategic observations into executable plans: granular segmentation, downloadable financial models, vendor benchmarking, regulatory templates, and prioritized roadmaps tailored to investors, OEMs, and contract service providers. For decision-makers preparing capital allocation, M&A diligence, or go-to-market strategies in 2026, the full report is designed as the operational playbook that bridges insight to implementation.
Next step
If your team is evaluating entry strategies, procurement choices, or M&A targets in the chlorine dioxide space, PW Consulting can provide the complete report package, customized advisory, and scenario modeling to inform board-level decisions in 2026. The full intelligence includes the detailed regional and application-level segmentation and the spreadsheet models referenced above — intentionally withheld here to preserve the value of the complete deliverable.
For detailed analysis of this topic, please visit the official page: Chlorine Dioxide (Chlorine Dioxide Generator) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicon Nitride Ceramics Market to Grow at 6.86% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Silicon Nitride Ceramics Market: Strategic Imperatives for 2026 Decision-Makers
As advanced materials converge with electrification, high-speed computing, and high-reliability manufacturing, silicon nitride (Si3N4) ceramics are moving from niche engineering curiosity to strategic line item on corporate roadmaps. PW Consulting’s latest market study—anchored on a 2025 base year and a detailed historical review from 2020–2025, with scenario-driven forecasts through 2032—translates that structural shift into actionable intelligence for executives planning capital allocation, product roadmaps, supply-chain redesign, and M&A in 2026.
Silicon Nitride Ceramics Market
Headline market context (what we measured)
Our macro model shows steady expansion over the past half-decade: the global silicon nitride ceramics market grew from a low three-figure base in 2020 to a materially larger market by the 2025 base year. Looking forward, the market is forecast to grow across the 2026–2032 horizon at a compound annual growth rate of 6.86%, reaching the high two-hundred‑million USD scale by 2032 in our central scenario. These headline dynamics are driven by technology-led demand in mobility electrification, power electronics, semiconductor manufacturing, and medical implants—each of which exerts different technical and commercial requirements on silicon nitride materials and processing.
Silicon Nitride Ceramics Market
Why this matters for 2026 decisions
- Capital allocation: The projected mid-single-digit CAGR and the sector’s step-change demand profile mean that capacity investments have multi‑year payback profiles but are sensitive to lead times, raw-material swings, and regulatory cost inflation. Companies that allocate capital without integrated supply‑chain modelling risk both underutilization and missed early-adopter opportunities.
- Supply‑chain resilience: Standard-grade Si3N4 powder supply is geographically concentrated, creating systemic risk vectors for companies that depend on “just-in-time” procurement. In addition, metallurgical silicon feedstock and nitrogen inputs have demonstrated price volatility in prior years—our modelling captures single‑year swings that can materially alter gross margins at the manufacturing node.
- Technology positioning: Advanced applications—power semiconductor substrates, EV bearings, and biomedical implants—require different processing routes and certification pathways. Firms that hedge across process technologies while securing tight technical partnerships with OEMs can convert incremental material performance improvements into differentiated, higher-margin product lines.
What PW Consulting’s report delivers (practical contents)
The full study is purpose-built to support board-level and operational decisions in 2026. It is organized to be directly actionable rather than purely descriptive, and includes:
Silicon Nitride Ceramics Market
- Executive synthesis and scenario planning (base, upside, downside) aligned to macroeconomic, energy, and raw-material stress tests.
- A detailed historical market model (2020–2025) and a transparent forecasting engine (2026–2032) with driver-level inputs so clients can re-run scenarios with proprietary assumptions.
- Supply-chain mapping and sensitivity models covering powder-to-component conversion, sintering and hot-press routes, and advanced additive manufacturing flows.
- Regulatory and ESG risk matrix focused on emissions and waste streams from nitride production, plus practical mitigation playbooks for compliance and cost control.
- Competitor and capability assessment with profiles of the leading technology providers, manufacturing specialists, and materials integrators—highlighting strategic strengths, technological edges, and likely moves in the next 12–18 months.
- Commercial go-to-market playbooks for three archetypal companies: incumbent manufacturers, materials specialists, and new entrants with licensing/R&D-first strategies.
- M&A and strategic partnership frameworks, including valuation sensitivities when raw-material volatility or capacity under-commitment is a factor.
To honour the “trailer” principle and preserve the value of our proprietary segmentation work, this overview deliberately omits detailed region-by-region and application-by-application breakdowns; those granular deliverables are available in the full report and interactive models.
Competitive landscape: who matters and why
The market demonstrates a mix of long-established ceramics manufacturers, materials innovators, and diversified industrial groups. Competitive dynamics are driven less by a single dominant global player and more by differentiated technical portfolios, capacity footprints, and market access to high-growth end markets.
- KYOCERA Corporation (Tokyo) — deep IP in fine Si3N4 ceramics for bearings, seals, and wear applications. Their recent launch of an optimized Si3N4 grade designed for extreme thermal‑mechanical loads underscores a strategy of product-led wins in mobility and industrial applications.
- CoorsTek Inc. (Golden, CO) — specializes in tight‑tolerance silicon nitride components and engineered balls/blanks for high-stress uses. Their capability to manufacture components to extreme dimensional and material standards positions them for growth where performance limits are the gating factor.
- SINTX Technologies (Salt Lake City, UT) — active at the intersection of industrial and biomedical applications, with FDA‑registered implants and emerging partnerships for 3D‑printed components. Their recent supply agreement targeting Si3N4‑polymer compounds for additive manufacturing highlights the growing convergence of materials and digital manufacturing.
- CeramTec GmbH (Landsberg am Lech) — offers substrates for power electronics and structurally robust high‑temperature components. Their portfolio is tuned to the needs of electrification and high-power semiconductor packaging.
- Morgan Advanced Materials, 3M, Denka, UBE, Toshiba Materials/Niterra, and International Syalons — these firms combine materials breadth, process know-how, and in several cases, global manufacturing footprints. Recent moves—capacity expansions and corporate restructuring—signal a defensive and offensive positioning ahead of projected demand growth.
Recent corporate developments captured in our study provide leading indicators of where supply and capabilities are headed. Examples include new material introductions tailored for high-stress seals and bearings, capacity increases aimed at automotive demand, supply agreements integrating Si3N4 into polymer matrices for additively manufactured implants, and strategic acquisitions that consolidate capabilities for EV bearings and power‑electronics substrates.
Industry dynamics and risk map
- Raw-material volatility: Metallurgical silicon and nitrogen-feedstock sourcing drive much of the cost-base. Our stress scenarios account for volatility spikes that have historically exceeded single‑year double‑digit swings, with direct pass-through implications for component-level pricing.
- Geopolitics and concentration risk: A significant share of standard-grade powder production is regionally concentrated, creating exposure to export control risk and trade friction. For manufacturers this elevates the strategic value of diversified sourcing and local buffer capacity.
- Regulatory pressure: Tighter environmental standards for nitride production raise both capex and opex for powder and component manufacturers; firms that front-load cleaner processes gain both compliance certainty and lower long-run operating risk.
- Labor and process complexity: High‑temperature sintering and specialty finishing require skilled labor—another bottleneck that can lengthen lead times and increase fixed costs.
Priority strategic moves for 2026
Based on our modelling and client engagements, PW Consulting recommends executives prioritize a short list of pragmatic actions in 2026 to navigate the period of sustained growth and elevated uncertainty:
- Run integrated supply-cost scenarios before committing capital: Test plant expansions and contract terms against raw-material and energy stress cases; use staged investment triggers linked to demand milestones.
- De-risk feedstock sourcing: Diversify powder suppliers and evaluate on-shore blending/repurposing strategies to reduce exposure to export constraints and single-source failures.
- Enter targeted technology partnerships: Collaborate with OEMs in EV, power electronics, and medical devices to co-develop specs that secure offtake and accelerate certification timelines.
- Prioritize process automation and workforce upskilling: Reduce unit-cost sensitivity to specialized labor and shorten ramp-up timelines for new capacity.
- Use M&A defensively and offensively: Pursue tuck-ins for process know-how or regional capacity where time-to-market matters; retain capital discipline and insist on scenario-based valuation adjustments tied to material-price pathways.
- Layer regulatory and ESG compliance into product pricing: Shift from viewing environmental upgrades as cost centers to treating them as market-access enablers that can justify premium positioning in regulated end markets.
How the full PW Consulting study helps you act
The full report provides the granular inputs and validated assumptions you need to translate the strategic moves above into board-level decisions: a modular financial model, supplier risk heatmaps, a prioritized target list for technical partnerships and M&A, and commercially tested go-to-market playbooks for materials, components, and system integrators. The public summary you are reading is designed to signal the depth and orientation of our work; the proprietary sections—segment-level demand by application and region, supplier scorecards, and live scenario models—are available to licensed clients who require immediate, executable recommendations for 2026.
If your 2026 plan depends on supply security, differentiated material performance, or timely certification in tightly regulated end markets, the decisions you make in the coming 12 months will define your market position for the remainder of the decade. PW Consulting’s silicon nitride ceramics study is built to convert market signals into defensible, executable strategy—backed by scenario-protected financials and a cross-functional playbook for operations, procurement, R&D, and corporate development.
Contact PW Consulting to access the interactive model and the full report to see the segmentation and granular forecasts that support board-level investment and transaction decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Silicon Nitride Ceramics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Blood Bank Market 2026: Strategic Preview for Executives — PW Consulting
Introduction — Why this briefing matters for 2026 decisions
As healthcare systems recalibrate in the wake of pandemic-era shocks, aging populations, and accelerating technological change, blood banking is transitioning from an operational utility to a strategic node in hospital and national health infrastructure. Our latest market study — built on an expanded historical base (2020–2025) and a forward-looking forecast (2026–2032) — synthesizes demand-supply dynamics, regulatory pivots, and competitive positioning that will determine who captures value across the blood value chain over the next decade.
Blood Bank Market
Key macro anchors from the study: the market reached an estimated USD 18.46 Billion in the base year (2025) and is projected to expand at a compound annual growth rate of 5.5% through our forecast horizon, reflecting steady secular demand plus accelerating investment in automation and safety technologies. Market concentration is meaningful: the three largest players account for roughly 55% of industry activity, and the top five approach 68% — a structure that shapes pricing power, partnership incentives, and M&A opportunities.
Blood Bank Market
Market snapshot and structural read
Two simultaneous forces define the near-term opportunity set. First, predictable, healthcare-driven demand (elective surgeries resuming at scale, chronic disease treatment, and trauma care) creates a stable consumables base. Second, structural change — standards updates, automation, pathogen-inactivation technologies, and supply-side consolidation — is shifting margins and capital requirements. Our historical tracking (2020–2025) shows modest year-to-year variability as systems absorbed shocks, while the forecast (2026–2032) anticipates an accelerated climb as technology adoption and regulatory-driven upgrades lift both unit economics and capital intensity.
Blood Bank Market
The concentration profile indicates a market where national blood services and large networks retain operational control over collections and distribution, while a smaller set of equipment and technology vendors command leverage through proprietary devices and consumables. This duality creates distinct playbooks for operators, suppliers, and investors.
Strategic inflection points for 2026 decision-making
- Regulatory and standards modernization: The effective implementation of updated AABB Standards (35th edition) in 2026 and formal regulatory recognitions such as FDA updates to labeling and information distribution materially change compliance roadmaps. Executives must budget for accelerated compliance cycles, certify new processes, and revalidate supplier contracts to avoid service interruptions.
- Quality and safety investments: Pathogen-reduction systems and enhanced testing are shifting capital from low-tech collection to integrated processing lines. Buyers that front-load validation and pilot programs will gain a time-to-market advantage as regulators and hospitals favor products with demonstrable risk reduction.
- Workforce and operational resilience: Localized labor shortages — evidenced in recent regional alerts — expose the fragility of collection-heavy models. Expect higher operating variability in geographies with constrained staffing unless operators invest in automation, cross-training, and redesigned donor logistics.
- Consolidation and partnership dynamics: Given the high CR3/CR5 ratios, larger networks will continue to pursue scale via M&A, regional partnerships, and vertical contracting with equipment suppliers. Smaller centers face strategic choices: specialize, partner with larger networks, or seek acquisition.
- Procurement and cost discipline: Raw consumables, capital equipment, and third-party processing will be primary levers to protect margins. Strategic sourcing programs and long-term supplier agreements — combined with scenario-based inventory planning — will be decisive in 2026 procurement cycles.
Competitive landscape — who shapes the market and why
The industry is populated by three broad actor types: national public services, independent community networks, and technology suppliers. Each plays a distinct strategic role:
- National and regional blood services (examples include large national organizations and established regional centers) maintain primary responsibility for donor recruitment, broad logistics, and stewardship of national inventories. Their scale provides leverage in negotiations and a mandate to prioritize public health objectives.
- Community and independent centers operate closer to hospital customers and can be important local partners — nimble in procurement and responsive to acute demand spikes, but often capital-constrained for major technology upgrades.
- Equipment and technology vendors provide automation, pathogen reduction, testing platforms, and software that convert operational complexity into predictable, high-margin offerings. Strategic relationships (pilots, exclusive supply, bundled service models) will be the primary route to scale for these vendors.
Close observers should watch a defined group of market actors that collectively influence adoption curves and competitive benchmarks: major national networks and service providers, a handful of equipment OEMs, and specialist technology licensors. These players are actively responding to standards updates, accelerating capital refresh cycles, and exploring vertically integrated offerings that combine collection, processing, and data-driven inventory management.
Regulatory and standards noise — implications for 2026
- AABB’s 35th edition standards (effective April 1, 2026) recalibrate quality system essentials and inspection expectations — a prompting event for capital planning, vendor requalification, and updated SOPs.
- FDA recognition of updated Circular of Information labeling requirements obliges annual hard-copy distribution and tighter change-control practices; this increases the administrative burden on both operators and device manufacturers.
- Accreditation scope changes (including out-of-hospital transfusion activities) expand oversight and create new compliance touchpoints for emergency services and novel care pathways.
What the PW Consulting report delivers — practical, operational, and judgmental intelligence
The full report translates macro projections into actionable architecture for executives and investors. Key deliverables include:
- Granular demand model and scenario forecasts by product, application, and region (including sensitivity runs tied to adoption rates and regulatory change). Note: high-resolution segment numbers and region/application breakdowns are available in the full dataset.
- CapEx proxy models and three-year investment roadmaps for automation, pathogen-reduction, and cold-chain modernization.
- Supplier scoring and vendor shortlists with procurement playbooks tailored to large networks and independent centers.
- M&A playbook and target-screening filters that combine strategic fit, operational synergies, and regulatory exposure.
- Compliance timeline and gap-analysis against the latest AABB and FDA developments, plus recommended remediation steps.
- Operational dashboards and KPI templates for inventory resilience, donor throughput, and cost-per-component metrics.
- Commercial launch templates for novel services (e.g., prehospital transfusion programs, contracted processing for hospitals) with pricing and reimbursement considerations.
How to use this research in 2026 — a practical checklist for leadership
- Allocate a regulatory readiness fund: Ensure budgets and timelines cover AABB-driven process upgrades and labeling/documentation changes.
- Initiate near-term pilots: Prioritize two-to-three vendor pilots for automation or pathogen-reduction technologies with pre-defined success metrics and a 6–12 month go/no-go decision gate.
- Stress-test workforce models: Model contingency plans for donor collection and laboratory staffing under multiple labor-stress scenarios; build cross-site staffing arrangements with neighboring centers.
- Revisit procurement strategy: Move from spot buys to multi-year, outcome-linked contracts where feasible; include clauses that protect supply continuity and price stability under demand shocks.
- Define M&A criteria now: For both acquirers and sellers, articulate thresholds for scale, geographic fit, and technology ownership that align with the concentration realities of the market.
- Embed operational KPIs into executive scorecards: Link supply-chain resilience, compliance readiness, and donor-engagement metrics directly to incentive plans.
Why PW Consulting’s approach matters
We combine high-resolution quantitative modeling with on-the-ground verification: interviews with national services and community centers, vendor product benchmarking, and regulatory horizon-scanning. The result is a report that not only forecasts where the market will go but prescribes how organizations should adjust pathways, prioritize investments, and structure partnerships to capture the emerging upside.
Call to action — where to get the full intelligence
This briefing is a strategic preview intended to inform board-level prioritization and 2026 investment cycles. The full report contains the segment-level data, regional splits, application-specific forecasts, and proprietary models that underpin these recommendations. Accessing that evidence will convert the directional guidance above into executable plans with specific ROI estimates, implementation timelines, and vendor shortlists.
For executives preparing 2026 budgets, investors scanning acquisition targets, and vendors positioning product roadmaps, the difference between opportunistic moves and sustained advantage will be decided by speed of adoption and quality of execution. The complete PW Consulting study delivers the quantitative backbone and the operational playbooks you need to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Blood Bank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phenoxy Resins Market to Reach USD 186.15 Million by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
Phenoxy Resins (CAS 26402-79-9): Strategic Outlook for 2026 Decision‑Making
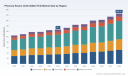
As PW Consulting’s senior strategy advisors, we present a targeted, executive‑grade preview of our comprehensive Phenoxy Resins (CAS 26402‑79‑9) market study. Built on a base year of 2025 and a historical series covering 2020–2025, the report translates granular market intelligence into boardroom-ready guidance for 2026. The study quantifies an established growth trajectory (compound annual growth rate of 5.8% through our 2026–2032 forecast window) and tracks the market’s evolution from its early‑decade baseline to the near‑term inflection points critical to procurement, R&D and M&A choices.
Phenoxy Resins (CAS 26402-79-9) Market
Why this study matters for decisions in 2026
2026 is a turning point: raw material volatility, revised industrial emissions legislation, and accelerating end‑market decarbonization are converging to reshape demand, pricing and product roadmaps for phenoxy resins. Our analysis synthesizes these forces into actionable scenarios for commercial leaders and technical executives.
Phenoxy Resins (CAS 26402-79-9) Market
-
Clear market momentum. Our end‑to‑end model captures the market’s steady expansion since 2020 and its projected continuation through 2032 at a mid‑single digit CAGR. This macro trajectory is not evenly distributed — pockets of accelerated demand, shifting formulations and margin compression are already visible to well‑positioned players.
Phenoxy Resins (CAS 26402-79-9) Market -
Regulatory and cost inflection points. With tighter VOC limits finalized for industrial coatings in recent years and raw material exposure to petrochemical cycles, immediate and medium‑term strategic moves will determine which firms protect margins and which cede share.
-
Competitive concentration. The market exhibits moderate concentration among leading producers; this structure creates both defensive and opportunistic paths for new entrants and incumbents pursuing adjacencies or scale plays.
What the full report delivers — practical, transaction‑ready content
We designed the study as a practitioner’s toolkit. The full deliverable provides the evidence base and operational templates that support decisions across procurement, product management, M&A and compliance programs. Highlights include:
-
Robust market sizing and trend decomposition (historical 2020–2025 and forecast 2026–2032), including scenario variants that stress raw material shocks, VOC‑driven reformulation and accelerated electrification in automotive and electronics.
-
Demand driver analytics by end‑use and formulation class, with elasticity estimates and price sensitivity matrices for customer segments.
-
Supply chain heatmaps and supplier scorecards that benchmark feedstock exposure, contract vulnerability, logistics risk and capacity flexibility.
-
Regulatory impact playbooks — compliance cost estimates, reformulation timelines, and a prioritized list of technical experiments to accelerate water‑based and low‑VOC offerings.
-
Commercial playbooks: value‑based pricing frameworks, distributor/channel strategies, tender defense templates and go‑to‑market options for differentiated grades.
-
M&A and partnership screening: criteria‑based lists of strategic targets, integration risk checklists and synergies models calibrated to typical consolidation pathways in this resin space.
-
Operational KPIs and a dynamic forecasting model (delivered as a client tool) that allows sensitivity testing across feedstock, pricing, capacity and product mix assumptions.
Market dynamics shaping 2026 strategies
Several structural and episodic forces should frame any 2026 strategy:
-
Upstream raw material volatility. Bisphenol A and epichlorohydrin remain principal feedstocks. Their exposure to broader petrochemical cycles creates recurring margin pressure for resin producers and requires disciplined procurement and hedging strategies by buyers and sellers alike.
-
Regulatory tightening. The EU’s updated Industrial Emissions Directive and stricter VOC rules for large coating operations are accelerating reformulation toward water‑borne solutions. Firms that anticipated this trend and invested in low‑VOC grades have clearer commercial momentum; laggards face either accelerated R&D expense or loss of market access in regulated jurisdictions.
-
Formulation shifts. The technical tradeoffs between solvent‑based and water‑based phenoxy chemistries — performance, processing and life‑cycle emissions — are driving differentiated product plays. Successful players combine laboratory know‑how with application engineering to reduce customer switching costs.
-
Pricing events and margin management. Recent producer actions illustrate the tight link between feedstock and list prices; for example, global price revisions for epoxy and phenoxy products in 2026 underscore how manufacturers manage margin erosion when naphtha and logistics costs spike. Strategic pricing discipline and contract clauses for pass‑throughs are now table stakes.
-
Concentration and competitive dynamics. The market’s top‑tier consolidation creates an environment of selective collaboration and competitive differentiation. A moderate top‑three/top‑five concentration level means scale matters for feedstock sourcing and global customer programs, but nimble specialists can still capture premium niches.
Competitive landscape — profiles that matter in 2026
Our competitive analysis synthesizes public disclosures, primary interviews and commercial win/loss data to map strategic positioning for the leading producers. Selected profiles:
-
DIC Corporation (Tokyo, Japan) — A diversified chemical platform offering phenoxy resins within its epoxy and specialty resin portfolio. Strengths include global customer reach and integrated sales channels; near‑term focus areas include margin preservation via price adjustments in response to feedstock cost inflation. ( https://www.dic-global.com/en/)
-
Mitsubishi Chemical Corporation (Tokyo, Japan) — Known for high‑molecular‑weight phenoxy grades marketed under a recognized brand for electronics, semiconductor packaging and automotive applications. Their competitive edge is engineering depth and customer co‑development for high‑performance segments. ( https://www.m-chemical.co.jp/en/)
-
Kukdo Chemical (Seoul, South Korea) — A leading producer with solution and solid grades tailored to electronics and industrial coatings. Kukdo’s strengths are cost‑competitive production and rapid response product development for regional OEMs. ( https://www.kukdo.com/en/)
-
Gabriel Performance Products (Akron, Ohio, U.S.) — Supplier of specialty PK‑series and micronized phenoxy resins, now operating within a larger chemical platform. Gabriel is positioned to serve technical coatings and adhesives markets where micronization and handling properties create differentiation. ( https://www.gabepro.com/)
-
Nan Ya Plastics Corporation (Taipei, Taiwan) — Integrated resin producer with downstream epoxy capabilities; capability to offer combined resin systems provides commercial leverage in adhesives and performance materials. ( https://www.nypc.com.cn/)
-
Hexion Inc. (Columbus, Ohio, U.S.) — Offers phenoxy resins within a wide resin portfolio for automotive and electronics segments; scale and application engineering are key competitive assets. ( https://www.hexion.com/)
Across these firms, the strategic levers are consistent: feedstock management, formulation leadership (especially water‑based), service and application engineering, and selective capacity investments. The market concentration profile supports both scale plays and targeted differentiation.
Recommended strategic moves for 2026
For executives making 2026 commitments, our pragmatic recommendations are prioritized by impact and execution horizon:
-
Immediate (0–6 months): embed feedstock pass‑through clauses into new contracts; run stress tests on existing contracts against a high‑price petrochemical scenario; launch a pricing‑defense task force to protect margins without sacrificing share.
-
Near term (6–18 months): accelerate development and commercialization of water‑based phenoxy grades where regulatory exposure is highest; co‑fund application trials with key customers to reduce adoption friction; reconfigure supply agreements to include flexible volumes and alternative sourcing options.
-
Medium term (12–36 months): evaluate bolt‑on acquisitions or strategic JV partners that supply epoxy or complementary resins to create system‑level offerings; invest selectively in micronization and powder processing capabilities where handling and formulation benefits command premium pricing.
-
Organizational: create a cross‑functional “resin strategy” cell combining procurement, R&D and commercial teams to operate the scenario model and execute rapid reprioritization as feedstock and regulation landscapes evolve.
How PW Consulting’s report unlocks decision value
Our study is designed to convert insight into execution. Beyond the market narrative, clients receive: a calibrated forecasting model with scenario toggles; supplier and target screening matrices; technical ranking criteria for reformulation projects; and a regulatory readiness checklist that ties compliance actions to product launch timelines. For leadership teams, the report functions as both a situational diagnostic and an operational playbook — enabling faster, evidence‑backed decisions in 2026.
We intentionally limit this preview to strategic conclusions and high‑level metrics to preserve the proprietary, segment‑level intelligence that drives competitive advantage. For full access to the detailed segmentation, end‑use breakouts, pricing ladders and company‑level share analysis that underlie these conclusions, please consult the report landing page.
Conclusion
Phenoxy resins are at an inflection. The combination of steady market growth, petrochemical cost exposure, regulatory tightening and application‑level shifts presents clear winners and losers in 2026. Companies that couple disciplined margin management with targeted technical investments — particularly in low‑VOC and water‑borne solutions — will secure preferred supplier status and superior returns. PW Consulting’s full study equips decision‑makers with the market maps, financial models and implementation templates necessary to navigate this next phase with confidence.
For detailed analysis of this topic, please visit the official page: Phenoxy Resins (CAS 26402-79-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive A/C Compressor Market to Reach USD 12.5B by 2032 at 4.05% CAGR
By pmarketresearch, 2026-07-13
Automotive Air‑Conditioning Compressors: Strategic Outlook for 2026 Decision‑Making
As automakers accelerate electrification, tightening refrigerant regulations converge with continued demand for climate comfort and thermal management, the Automotive Air‑condition Compressor market sits at an inflection point. This PW Consulting briefing distills the key market dynamics that will matter to executive teams in 2026 — revealing where the value pools are expanding, which competitive moves will shape supplier power, and what operational levers buyers and producers must prioritize. We provide an evidence‑based snapshot of market scale and trajectory while intentionally reserving granular segment tables and regional breakdowns for the full report to preserve the premium intelligence that underpins actionable decisions.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Market snapshot: measured growth, structural transformation
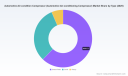
The global market for automotive air‑conditioning compressors has shown steady expansion through the 2020–2025 historical window and is projected to continue growing through the 2026–2032 forecast horizon. On an absolute basis the market increased from about USD 7.3 Billion in 2020 to approximately USD 9.5 Billion in 2025, and our base‑case projection points to roughly USD 12.5 Billion by 2032. This trajectory implies a mid‑single‑digit compound annual growth rate across the forecast horizon (4.05% CAGR for 2026–2032), reflecting the combined effects of electrification, regulatory shifts, and aftermarket replacement demand.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Two structural themes underlie the nominal growth: first, rapid adoption of electrified powertrains forces a re‑architecting of compressor technology (electric compressors, inverter controls, integration with heat pumps). Second, regulatory and sustainability pressures drive refrigerant transitions and efficiency upgrades, raising product complexity and engineering content per vehicle. For 2026 planning cycles, these trends translate into higher technology risk but also clearer pathways to margin enhancement for players who move early on electrified and high‑efficiency platforms.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Why this matters for 2026 corporate decisions
- Product roadmap prioritization: Firms making 3–5 year platform bets must align R&D spend with electrified compressor architectures (low‑vibration scrolls, high‑voltage designs, and integrated heat‑pump solutions). Delaying such investments risks OEM disqualification as electrified vehicle content ramps.
- Supply‑chain resilience and cost management: The industry remains exposed to aluminium, steel and copper price volatility. Procurement strategies that combine longer forward contracts, multi‑sourcing, and alloy optimization will materially protect margins through 2026.
- Regulatory compliance as a go‑to‑market driver: Refrigerant phase‑outs and regional regulatory differences mean OEM product specs will diverge across markets. Capturing share requires modular compressor platforms that can be adapted for low‑GWP refrigerants without substantial retooling.
- M&A and partnership prioritization: Market concentration indicators show that a moderate share of demand is clustered among leading suppliers, creating opportunities for bolt‑on acquisitions to accelerate capability in electrified compressors or to access critical OEM engagements.
- Aftermarket and reman strategies: As vehicle parc ages, aftermarket demand remains a steady revenue pool; services and remanufacturing can complement new‑equipment margins and provide recurring revenue during new‑vehicle cyclical downturns.
Competitive landscape: capabilities that decide the next cycle
The competitive map is neither atomized nor monopolistic — leading suppliers hold significant leverage, yet there is still room for technology challengers and regional specialists. Our analysis of core players highlights where each incumbent is positioned and what to expect from them in 2026.
- Sanden Corporation (Isesaki, Japan) — A long‑standing specialist in open scroll and other compressor technologies with deep OEM ties. Sanden’s strength is platform breadth across passenger and light commercial vehicles; their aftermarket channel and legacy relationships make them a default partner when OEMs seek proven reliability in transitional refrigerant environments.
- Hanon Systems (Daejeon, South Korea) — Hanon packages compressors within broader thermal management and HVAC systems, giving them an advantage when OEMs prioritize integration (e.g., combined cabin HVAC and battery thermal management). They are also advancing heat‑pump competencies that will be pivotal for EV HVAC efficiency.
- BorgWarner Inc. (Auburn Hills, USA) — Leveraging heritage from Delphi and systems engineering capability, BorgWarner is positioned around fuel‑economy and emissions outcomes. Their OE relationships and systems approach make them a likely partner for automakers seeking integrated electrified HVAC subsystems.
- MAHLE GmbH (Stuttgart, Germany) — MAHLE’s Compact Variable Compressor (CVC) technology and recent investments in high‑voltage compressors target high‑performance electrified platforms. Their product roadmap signals readiness to supply 800V systems for heavy electrification and fast‑charge thermal scenarios.
- ESTRA Automotive Systems (Daegu, South Korea) — A nimble supplier focused on high‑efficiency designs including variable swashplate and e‑compressor types. ESTRA acts as a technology fast follower and specialist for customers looking to optimize fuel economy and reduce NVH at lower development lead times.
- Mitsubishi Heavy Industries (Tokyo, Japan) — A supplier moving aggressively into electric compressors with scroll‑based, low‑vibration units and inverter controls suited to hybrids and battery electric vehicles. Recent product launches demonstrate their commitment to compact, efficient electric architectures suitable for OEM electrification programs.
Market concentration metrics show the top three suppliers collectively hold a significant portion of demand, while the top five capture roughly two‑thirds of the market. This concentration creates an environment where strategic alliances and targeted M&A can decisively reconfigure supplier position in 2026.
Technology and product trends shaping buy/sell decisions
- Electric compressors and inverterization: Adoption is accelerating across hybrid and battery EVs. Companies that can offer robust, low‑vibration electric scrolls and high‑voltage compatibility will command pricing premiums.
- Heat‑pump integration: Compressors that can be integrated within vehicle heat‑pump cycles offer distinct efficiency advantages and therefore higher specification ceilings from OEMs, especially in cold‑climate models.
- Modularity for refrigerant transitions: Compressor designs that accommodate low‑GWP refrigerants with minimal retooling reduce technical and time‑to‑market risk for OEMs operating across multiple regulatory regimes.
- NVH and reliability engineering: As customer expectations rise and vehicle acoustic standards tighten, low‑vibration designs (scroll and inverter control strategies) become differentiators in OEM supplier selection.
Regulatory and input‑cost headwinds (and how to plan for them)
Key external pressures that should be factored into 2026 budgets and contractual frameworks include:
- Refrigerant regulation: Policy action in regions like the EU is accelerating phase‑out of high‑GWP refrigerants. Manufacturers must be able to certify equipment for approved alternatives and demonstrate lifecycle global warming benefits.
- Raw material volatility: Aluminium, steel and copper price swings remain a principal driver of cost pressure. Hedging strategies, alloy substitution and design for material efficiency are essential mitigants.
- Thermal protector evaluations in hot climates: Thermal safety and protector requirements in extreme‑heat markets may necessitate product adaptations that affect BOM and service approach; such regulatory evaluations should be built into product qualification timelines.
What the full PW Consulting report delivers (practical, not theoretical)
PW Consulting’s comprehensive market study goes beyond directional analysis to provide the operational detail required for 2026 decision making. Key deliverables include:
- Forecast model with base year 2025 and annualized projections through 2032, including sensitivity scenarios for electrification pace and refrigerant regulation adoption.
- Competitive benchmarking across technology capabilities, OEM relationships, and aftermarket reach — with supplier scorecards to identify best‑fit partners for JV, supplier development or acquisition.
- Commercial playbook templates (pricing levers, contract clauses for raw‑material pass‑through, warranty structures for e‑compressors) ready for immediate use in supplier negotiations.
- Go‑to‑market roadmaps for OEMs and Tier‑1s on transitioning platforms to low‑GWP refrigerants and integrating heat pump systems.
- Deal‑flow and M&A heatmap identifying targets, valuation benchmarks, and integration risks for capability‑building transactions.
Note: To preserve the value of the underlying market intelligence, detailed regional splits, type‑level volumes and exact segment revenue figures are reserved for the full report and data pack available through our client portal.
Immediate 90‑day actions for executives
- Run a product‑portfolio stress test aligned to an EV‑first and a delayed‑EV scenario; identify which compressor platforms require accelerated investment.
- Implement a commodity risk mitigation plan focusing on aluminium and copper exposures, including a mix of spot coverage, forwards, and strategic hedges linked to production milestones.
- Open two strategic conversations: one with a thermal‑systems integrator (to secure heat‑pump co‑development) and one with a niche electric‑compressor specialist (for technology licensing or minority equity). Prioritize partners that can accelerate time‑to‑market for 800V and inverterized systems.
- Audit compliance readiness for low‑GWP refrigerants in key selling markets and budget a regulatory‑driven product variant program for 2026 production starts.
Conclusion — how PW Consulting helps you convert insight into advantage
For 2026, decisions on R&D allocation, supplier strategy, and M&A will determine which companies capture the higher margins and richer content opportunities arising from electrified HVAC and regulatory change. PW Consulting’s study quantifies the growth trajectory, evaluates competitive positions, and supplies the commercial tools required to act now. If your team is preparing budget sign‑offs, platform investments, or supplier restructurings next year, the full report delivers the segment‑level intelligence and scenario models you will need to de‑risk those choices and capture upside.
Contact PW Consulting to access the complete report and data pack, including downloadable models, supplier scorecards, and an implementation playbook tailored to your role (OEM, Tier‑1, investor, or aftermarket player).
For detailed analysis of this topic, please visit the official page: Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Healthcare & Medical System Integrators Market to Expand at 11.02% CAGR
By pmarketresearch, 2026-07-13
Healthcare and Medical System Integrators Market: Strategic Playbook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive introduction to our newest market research on Healthcare and Medical System Integrators. This preview outlines the strategic value the full study delivers to leaders making investment, procurement, partnership, and M&A decisions in 2026. It demonstrates the analytic depth of our work while preserving high‑value segment tables and proprietary breakouts for the full report—available on our site.
Healthcare and Medical System Integrators Market
Why this research matters for 2026
-
Healthcare system integration is no longer a back-office IT expense; it is an operational enabler shaping care delivery, regulatory compliance, and commercial models.
Healthcare and Medical System Integrators Market -
Decision windows in 2026 are compressed: budgets set in H1 drive vendor selection and platform bets that will determine interoperability posture for the next 3–5 years.
Healthcare and Medical System Integrators Market -
Our study frames those decisions with a forward-looking economic lens—quantifying market growth, profiling competitive moves, and translating regulations into operational checklists.
Market trajectory at a glance
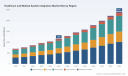
We model the integrator market with a robust historical series (2020–2025) and a seven-year forecast (2026–2032). Key topline sizing shows the market expanding from USD 700.5 Million in 2020 to USD 1,160.0 Million in 2025 (base year). Under our central scenario, the market grows at a compound annual growth rate (CAGR) of 11.02%—reaching USD 1,287.8 Million in 2026 and roughly USD 2,403.0 Million by 2032.
That growth is not linear; it reflects accelerating investments in cloud-native interoperability, AI-enabled EHR elements, and facility modernization programs that spike spending in 2026–2029. For buyers and investors, the implication is clear: the market is large enough to support specialist players and converging platform strategies, and rapid enough to punish delayed procurement cycles.
What the report delivers—practical, actionable content
We designed the report for operators, CIOs, acquirers, and strategy teams who need executable guidance, not only descriptive analysis. The full deliverable contains:
-
Proprietary market model with historicals and scenario-driven forecasts—downloadable and modifiable for custom sensitivity testing.
-
Vendor benchmarking and capability matrices that score providers across interoperability, clinical integration, device connectivity, managed services, and cloud operations.
-
Implementation playbooks: phased roadmaps, staffing profiles, procurement templates, and a risk mitigation checklist tailored to hospital systems and integrated delivery networks.
-
Regulatory and compliance mapping for US and EU markets—linking certification milestones to procurement triggers and contract clauses.
-
M&A and partnership tracker with deal valuations, strategic rationale, and integration risk assessments to support target screening and diligence.
-
Case studies and ROI models illustrating typical cost-to-value trajectories for horizontal consolidation vs. vertical integration approaches.
Competitive landscape—what incumbents and challengers are doing
The landscape is a blend of specialist integration engine providers, systems integrators with healthcare focus, and platform vendors moving into adjacent integration layers. Our competitive chapter profiles each major player with primary offerings, go-to-market motions, and strategic priorities. Highlights include:
-
iNTERFACEWARE Inc (Toronto): Known for its Iguana integration engine and a strong reputation in EHR interoperability and medical device data flows. Recent trade show and user‑community activity through HIMSS and its Iguana User Conference underline an emphasis on customer enablement and ecosystem stickiness.
-
Burwood Group, Inc (United States): A specialized IT consulting and integration firm now operating within a larger professional services umbrella following its strategic move to join Sikich—reinforcing a playbook focused on value‑based care enablement via integrated IT services.
-
FORTÉ (formerly AVI Systems, Minneapolis): Transitioned branding to signal broadened capabilities across collaboration and medical facility integration; the repositioning reflects an intent to capture consultative AV-led projects that interface with clinical workflows.
-
InterSystems Corporation (Boston): Continues to bridge enterprise information systems and clinical workflows; importantly, it has advanced AI-native EHR concepts and announced certification progress relevant to EU device regulation, positioning it for cross-border deployments where regulation is a gating factor.
-
Veradigm LLC (Chicago): Focused on connected care platforms and EHR integration, emphasizing data privacy and interoperability compliance as critical procurement differentiators in US and EU markets.
Collectively, the market exhibits moderate concentration: our competitive analysis estimates that the top-three players account for a meaningful share of the market, and the top-five increase that share further—indicative of an environment where scale and end‑to‑end capabilities influence large health system decisions. (Our summary metrics report a CR3 of 55% and a CR5 of 68%.)
Market dynamics and risks you must prioritize
Adoption drivers and systemic risks are tightly coupled in this market. Key dynamics covered in the report include:
-
Interoperability and standards: Payors and regulators are elevating expectations for data portability and certified interfaces—making compliance a procurement prerequisite, not a checkbox exercise.
-
Regulatory complexity: Vendors are adapting to region-specific certification regimes and device regulation. Recent vendor announcements signal progress on certification and KLAS-rated performance, but buyers should validate claims against audited evidence.
-
Technology convergence: AI-native EHR modules and cloud-first integration platforms change the supplier landscape; organizations must decide between incremental integration upgrades or platform replacement strategies.
-
Cost of expertise and workforce constraints: Skilled integration architects are scarce, elevating managed service models and vendor-provided implementation teams as viable options to accelerate time-to-value.
-
Consolidation and partner ecosystems: Strategic acquisitions and rebrands are reshaping go-to-market routes; expect more roll-ups and vertical moves as integrators seek scale and cross-sell synergies.
Scenarios for 2026 planning
Using our model and client workshops, we present three actionable scenarios that executives can adopt in 2026:
-
Consolidation Play: For systems seeking cost efficiencies—prioritize vendor rationalization, invest in a dominant integration platform, and negotiate long-term managed services to offset workforce scarcity.
-
Best-of-Breed Play: For organizations focused on rapid innovation—layer specialized engines for device telemetry and AI components on top of robust APIs, accepting higher integration overhead for advanced capabilities.
-
Regulatory-First Play: For cross-border health systems—sequence investments to prioritize certified components and compliance-driven integrations to avoid retrofitting costs and market entry delays.
The intelligence you won’t find in this preview (but will in the full report)
To preserve the strategic value of our proprietary work, this introduction deliberately omits the granular regional, type, and application-level breakouts that clients use for precise deal sizing and RFP scoping. The full report contains:
-
Regional and application revenue splits with trend-level granularity and confidence intervals.
-
Vendor scorecards with weighted capability scores and sourcing recommendations by buyer archetype.
-
A downloadable financial model and scenario files to adapt the forecast to your own assumptions.
These elements move the conversation from high-level strategy to procurement actions, risk‑reduction design, and diligence-ready analytics.
Implications and recommended next steps for 2026
-
Embed interoperability as a procurement criterion—require audited performance metrics and compliance evidence as part of RFPs.
-
Prioritize integration pilots that demonstrate clinical workflow benefits within 6–9 months; use those pilots to inform platform vs. point-solution decisions.
-
Build M&A watchlists and partnership funnels aligned to your strategic play (consolidation, best-of-breed, regulatory-first) and stress-test potential targets against the market’s 11%+ growth trajectory.
-
Reserve budget for managed services and talent partners—scarcity of skilled integrators will continue to drive premium for implementation capacity.
-
Request the detailed appendices and model from PW Consulting to convert the findings into a bespoke implementation roadmap and vendor shortlist.
Closing—how to use this insight
In 2026, winners will be the organizations that treat systems integration as a strategic asset: aligning vendor choices with regulatory trajectories, clinical outcomes, and long-term platform economics. This preview lays out the strategic contours; the full PW Consulting study supplies the necessary data, vendor assessments, and executable templates to move from strategy to procurement and execution.
To access the complete report, the downloadable model, and vendor scorecards, please visit the PW Consulting report page—where clients can also schedule a briefing with our advisory team to translate findings into a 90‑day action plan for 2026.
For detailed analysis of this topic, please visit the official page: Healthcare and Medical System Integrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PV Glass Market to Hit USD 51.65B by 2032 at 18.46% CAGR
By pmarketresearch, 2026-07-13
PV Glass (Solar Photovoltaic Glass) Market — 2026 Strategic Preview
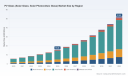
As governments accelerate clean-energy targets and module manufacturers chase incremental efficiency gains, photovoltaic (PV) glass has moved from a commoditized input to a strategic raw material. This preview summarizes the strategic value of PW Consulting’s full PV Glass Market study for corporate decision-making in 2026. It highlights the market’s macro trajectory, competitive dynamics, policy inflection points and the practical, playbook-style intelligence that executives will need to convert market growth into durable advantage — while deliberately withholding the granular segmentation tables and plant-level financials that are contained in the full report.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Macro trajectory you must plan around
The PV glass market is on a steep growth path. Our base-year framework (historical 2020–2025; base year 2025) shows the industry accelerating from a multi‑billion dollar market in 2020 to a materially larger market by 2025, and our forecast (2026–2032) projects continued robust expansion. PW Consulting’s forecast shows sustained high‑teens growth over the medium term (the modeled forecast CAGR is 18.46% for the forecast period), producing transformative scale by the end of the decade. That growth is driven by a mix of utility‑scale installations, new module types that demand higher-performance glass, and a renewed policy focus on domestic clean‑tech manufacturing in several large markets.
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Why this research matters for 2026 corporate decisions
- Capital allocation: With the market growing rapidly, choices about greenfield versus brownfield capacity, modular line investments (tempering, AR-coating, TCO capability) and timing have multi-year payback profiles. Our study maps where and when incremental capacity is likely to be absorbed under multiple demand scenarios.
- Procurement and price risk: Volatility in key feedstocks and periodic trade interventions can swing landed costs. The report gives a transparent price‑build model and hedging playbook so procurement leads can lock economically sensible multi‑year agreements without overpaying for optionality.
- Supply security for module manufacturers: Module OEMs face a new reality — glass availability and specification choice materially affect cell efficiency and BOS costs. The study supplies supplier scorecards and recommended contracting terms architects and buyers can operationalize in 2026.
- M&A and partnership targets: We identify the profile of acquisition targets and JV structures that generate rapid scale and market access, and include an M&A screening tool that ranks opportunities by strategic fit and integration complexity.
- Regulatory and trade strategy: With tariffs, anti‑dumping remedies and industrial incentives changing rapidly, the research provides a decision checklist for trade counsel and government affairs teams to prioritize lobbying, localization and tariff-mitigation strategies.
What’s in the full report (practical, operational content)
- Top‑line and bottom‑line market forecasts (2026–2032) with scenario variants and sensitivity analysis linked to module demand, glass pricing and feedstock cost curves.
- A supply‑demand model at line and plant level (availability, ramp schedules, utilization thresholds and likely export flows) — presented with visual dashboards and downloadable Excel modules.
- Price‑build and input‑cost model (including soda ash and silica trends), and supplier‑negotiation templates for fixed, index‑linked and hybrid contracting.
- Supplier scorecards and capability matrices (capacity, technology stack: float/tempered/AR/TCO, quality, vertical integration) with an acquisition/partner suitability index.
- Regulatory tracker and policy impact assessment covering tariffs, trade remedies and industrial incentive programs across key markets.
- Capex timelines, typical greenfield and brownfield economics, and a playbook for rapid line commissioning with risk checklists for permitting, utilities and feedstock logistics.
- Three forward scenarios (base, upside, downside), an executive risk matrix, and an actionable 90‑day strategic checklist for executive teams.
Market dynamics and near‑term catalysts
Several forces are converging in 2026 to re‑shape supplier economics and customer strategies:
PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
- Policy-driven localisation: Industrial policies in major economic blocs are nudging procurement and capex towards domestic or preferential suppliers. This is creating near-term demand pockets for locally produced PV glass and encouraging module OEMs to rethink sourcing footprints.
- Trade interventions and tariff timing: Several trade remedies and tariff regimes remain active or are scheduled for review in 2026. These create windows of procurement risk and opportunity for firms that calibrate contracts and inventory proactively.
- Feedstock cost volatility: Soda ash and other raw-material price swings have periodically reset margins. During 2025 soda ash experienced downward pressure from oversupply; procurement teams should bake in scenario buffers, but also seek to capture cost advantages where they appear.
- Technology segmentation: Different glass technologies (ultra‑clear float, AR‑coated, TCO coatings, tempered/textured surfaces) are not interchangeable from a module performance standpoint. Upstream producers that can cost‑effectively deliver specific glass specs will command premium access to high‑value module programs.
- Consolidation and market concentration: The industry exhibits a moderate level of concentration at the top. The three largest players control a significant share of global capacity, and the top five command a clear majority — a structure that influences price discovery, contractual norms and the speed of technology diffusion.
Competitive landscape — strategic implications from the leader set
Understanding incumbent strategies is essential to anticipate capacity moves, pricing behavior and technology adoption. Key dynamics we highlight:
- Xinyi Solar Holdings : A dominant global player with a material share of the market and strong scale in low‑iron tempered glass. Its investments in Southeast Asia capacity expansion are intended to combine cost competitiveness with proximity to major module assembly hubs. For competitors and buyers, Xinyi’s moves mean capacity discipline and aggressive fulfilment timelines—module OEMs should evaluate long‑term supply contracts and contingency plans.
- Flat Glass Group : A large producer prioritizing ultra‑clear float and AR‑coated glass. Its technology focus positions it well to serve high‑efficiency c‑Si module programs. For investors, Flat’s strategy underlines the premium for AR capability in higher‑value segments.
- NSG Group (Nippon Sheet Glass) : With expertise in TCO‑coated products suited to thin‑film technologies, recent commissioning of a TCO line in the United States is a tactical response to thin‑film OEM demand and localization trends. Module manufacturers contemplating thin‑film adoption or expansion should view NSG as a potential strategic partner.
- AGC Inc. : AGC competes on ultra‑clear float and AR coatings designed for high‑efficiency modules. Its product set is attractive to OEMs pursuing incremental efficiency and lower LCOE through optical gains.
- Borosil Renewables : A leading domestic player in India that recently received board approval to expand capacity. The company’s domestic position and agility give it an advantage in a market where trade remedies and import measures materially affect sourcing economics.
- Guardian Industries : With product lines marketed for utility and concentrator applications, Guardian is an important supplier to North American utility‑scale projects and specialized module formats.
Collectively, these firms demonstrate three strategic playbooks that matter for 2026: (1) scale + cost leadership, (2) technology differentiation (AR/TCO/textures), and (3) geographic/localization plays aligned with trade policy. Your response should be calibrated to which playbook your company can credibly aspire to.
Scenario planning & risk matrix (executive highlights)
- Base case: Continued strong demand growth consistent with high‑teens CAGR in the forecast window; orderly capacity additions and moderate feedstock price movements. Contracts and procurement strategies that lock multi‑year volumes at indexed prices perform well.
- Upside: Faster module adoption and higher‑than-expected deployment cause a temporary tightness in supply for premium glass specs. This scenario favors firms with agile capacity expansions, fast commissioning, or exclusive off‑take agreements with module OEMs.
- Downside: Prolonged trade restrictions, delayed tariffs expirations or sharp raw‑material inflation compress margins and re‑orient flows towards protected/domestic suppliers. Here, companies with diversified supplier bases and in‑region production win.
90‑day playbook for 2026 executive teams
- Quantify exposure: Map your volume exposure to top suppliers and to products that have differentiated specs (AR, TCO, textured). Run the supplied sensitivity templates for price and lead‑time shocks.
- Secure optionality: Negotiate layered contracts (short‑term float + long‑term tranche) and include force‑majeure and tariff‑pass‑through clauses where appropriate.
- Capex prioritization: Re‑test any planned greenfield investments against our utilization thresholds and ramp‑risk checklist; consider brownfield acquisitions to accelerate time‑to‑market.
- Regulatory engagement: Align government affairs and procurement around the policy windows available in 2026 — especially where local content rules or incentives materially change landed cost economics.
- Competitor watch: Track announced and rumored capacity moves from leading players and module OEM programs that require premium glass; prioritize intelligence that impacts your 18‑month supply visibility.
Conclusion — the decision moment for 2026
For executives planning capital, procurement and market expansion in 2026, PV glass is no longer a background commodity risk — it is a strategic lever. PW Consulting’s full market study combines forecast rigor (2026–2032 outlook and an 18.46% forecast CAGR), supplier intelligence, regulatory tracking and executable playbooks to convert market trends into discrete decisions. The public preview above demonstrates the type of thinking we apply; the full report contains the detailed segmentation, plant‑level timelines, supplier scorecards, price models and Excel tools you will need to operationalize a winning 2026 strategy.
To access the complete dataset, model files and our confidential supplier scorecards that underpin the recommendations in this preview, visit the PW Consulting report page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: PV Glass (Solar Glass; Solar Photovoltaic Glass) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com