

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Blood Bank Market Set for 5.5% CAGR Through 2032

Blood Bank Market 2026: Strategic Preview for Executives — PW Consulting
Introduction — Why this briefing matters for 2026 decisions
As healthcare systems recalibrate in the wake of pandemic-era shocks, aging populations, and accelerating technological change, blood banking is transitioning from an operational utility to a strategic node in hospital and national health infrastructure. Our latest market study — built on an expanded historical base (2020–2025) and a forward-looking forecast (2026–2032) — synthesizes demand-supply dynamics, regulatory pivots, and competitive positioning that will determine who captures value across the blood value chain over the next decade.
Blood Bank Market
Key macro anchors from the study: the market reached an estimated USD 18.46 Billion in the base year (2025) and is projected to expand at a compound annual growth rate of 5.5% through our forecast horizon, reflecting steady secular demand plus accelerating investment in automation and safety technologies. Market concentration is meaningful: the three largest players account for roughly 55% of industry activity, and the top five approach 68% — a structure that shapes pricing power, partnership incentives, and M&A opportunities.
Blood Bank Market
Market snapshot and structural read
Two simultaneous forces define the near-term opportunity set. First, predictable, healthcare-driven demand (elective surgeries resuming at scale, chronic disease treatment, and trauma care) creates a stable consumables base. Second, structural change — standards updates, automation, pathogen-inactivation technologies, and supply-side consolidation — is shifting margins and capital requirements. Our historical tracking (2020–2025) shows modest year-to-year variability as systems absorbed shocks, while the forecast (2026–2032) anticipates an accelerated climb as technology adoption and regulatory-driven upgrades lift both unit economics and capital intensity.
Blood Bank Market
The concentration profile indicates a market where national blood services and large networks retain operational control over collections and distribution, while a smaller set of equipment and technology vendors command leverage through proprietary devices and consumables. This duality creates distinct playbooks for operators, suppliers, and investors.
Strategic inflection points for 2026 decision-making
- Regulatory and standards modernization: The effective implementation of updated AABB Standards (35th edition) in 2026 and formal regulatory recognitions such as FDA updates to labeling and information distribution materially change compliance roadmaps. Executives must budget for accelerated compliance cycles, certify new processes, and revalidate supplier contracts to avoid service interruptions.
- Quality and safety investments: Pathogen-reduction systems and enhanced testing are shifting capital from low-tech collection to integrated processing lines. Buyers that front-load validation and pilot programs will gain a time-to-market advantage as regulators and hospitals favor products with demonstrable risk reduction.
- Workforce and operational resilience: Localized labor shortages — evidenced in recent regional alerts — expose the fragility of collection-heavy models. Expect higher operating variability in geographies with constrained staffing unless operators invest in automation, cross-training, and redesigned donor logistics.
- Consolidation and partnership dynamics: Given the high CR3/CR5 ratios, larger networks will continue to pursue scale via M&A, regional partnerships, and vertical contracting with equipment suppliers. Smaller centers face strategic choices: specialize, partner with larger networks, or seek acquisition.
- Procurement and cost discipline: Raw consumables, capital equipment, and third-party processing will be primary levers to protect margins. Strategic sourcing programs and long-term supplier agreements — combined with scenario-based inventory planning — will be decisive in 2026 procurement cycles.
Competitive landscape — who shapes the market and why
The industry is populated by three broad actor types: national public services, independent community networks, and technology suppliers. Each plays a distinct strategic role:
- National and regional blood services (examples include large national organizations and established regional centers) maintain primary responsibility for donor recruitment, broad logistics, and stewardship of national inventories. Their scale provides leverage in negotiations and a mandate to prioritize public health objectives.
- Community and independent centers operate closer to hospital customers and can be important local partners — nimble in procurement and responsive to acute demand spikes, but often capital-constrained for major technology upgrades.
- Equipment and technology vendors provide automation, pathogen reduction, testing platforms, and software that convert operational complexity into predictable, high-margin offerings. Strategic relationships (pilots, exclusive supply, bundled service models) will be the primary route to scale for these vendors.
Close observers should watch a defined group of market actors that collectively influence adoption curves and competitive benchmarks: major national networks and service providers, a handful of equipment OEMs, and specialist technology licensors. These players are actively responding to standards updates, accelerating capital refresh cycles, and exploring vertically integrated offerings that combine collection, processing, and data-driven inventory management.
Regulatory and standards noise — implications for 2026
- AABB’s 35th edition standards (effective April 1, 2026) recalibrate quality system essentials and inspection expectations — a prompting event for capital planning, vendor requalification, and updated SOPs.
- FDA recognition of updated Circular of Information labeling requirements obliges annual hard-copy distribution and tighter change-control practices; this increases the administrative burden on both operators and device manufacturers.
- Accreditation scope changes (including out-of-hospital transfusion activities) expand oversight and create new compliance touchpoints for emergency services and novel care pathways.
What the PW Consulting report delivers — practical, operational, and judgmental intelligence
The full report translates macro projections into actionable architecture for executives and investors. Key deliverables include:
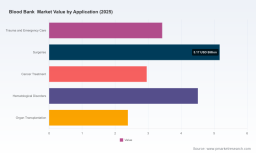
- Granular demand model and scenario forecasts by product, application, and region (including sensitivity runs tied to adoption rates and regulatory change). Note: high-resolution segment numbers and region/application breakdowns are available in the full dataset.
- CapEx proxy models and three-year investment roadmaps for automation, pathogen-reduction, and cold-chain modernization.
- Supplier scoring and vendor shortlists with procurement playbooks tailored to large networks and independent centers.
- M&A playbook and target-screening filters that combine strategic fit, operational synergies, and regulatory exposure.
- Compliance timeline and gap-analysis against the latest AABB and FDA developments, plus recommended remediation steps.
- Operational dashboards and KPI templates for inventory resilience, donor throughput, and cost-per-component metrics.
- Commercial launch templates for novel services (e.g., prehospital transfusion programs, contracted processing for hospitals) with pricing and reimbursement considerations.
How to use this research in 2026 — a practical checklist for leadership
- Allocate a regulatory readiness fund: Ensure budgets and timelines cover AABB-driven process upgrades and labeling/documentation changes.
- Initiate near-term pilots: Prioritize two-to-three vendor pilots for automation or pathogen-reduction technologies with pre-defined success metrics and a 6–12 month go/no-go decision gate.
- Stress-test workforce models: Model contingency plans for donor collection and laboratory staffing under multiple labor-stress scenarios; build cross-site staffing arrangements with neighboring centers.
- Revisit procurement strategy: Move from spot buys to multi-year, outcome-linked contracts where feasible; include clauses that protect supply continuity and price stability under demand shocks.
- Define M&A criteria now: For both acquirers and sellers, articulate thresholds for scale, geographic fit, and technology ownership that align with the concentration realities of the market.
- Embed operational KPIs into executive scorecards: Link supply-chain resilience, compliance readiness, and donor-engagement metrics directly to incentive plans.
Why PW Consulting’s approach matters
We combine high-resolution quantitative modeling with on-the-ground verification: interviews with national services and community centers, vendor product benchmarking, and regulatory horizon-scanning. The result is a report that not only forecasts where the market will go but prescribes how organizations should adjust pathways, prioritize investments, and structure partnerships to capture the emerging upside.
Call to action — where to get the full intelligence
This briefing is a strategic preview intended to inform board-level prioritization and 2026 investment cycles. The full report contains the segment-level data, regional splits, application-specific forecasts, and proprietary models that underpin these recommendations. Accessing that evidence will convert the directional guidance above into executable plans with specific ROI estimates, implementation timelines, and vendor shortlists.
For executives preparing 2026 budgets, investors scanning acquisition targets, and vendors positioning product roadmaps, the difference between opportunistic moves and sustained advantage will be decided by speed of adoption and quality of execution. The complete PW Consulting study delivers the quantitative backbone and the operational playbooks you need to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Blood Bank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com