

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive A/C Compressor Market to Reach USD 12.5B by 2032 at 4.05% CAGR

Automotive Air‑Conditioning Compressors: Strategic Outlook for 2026 Decision‑Making
As automakers accelerate electrification, tightening refrigerant regulations converge with continued demand for climate comfort and thermal management, the Automotive Air‑condition Compressor market sits at an inflection point. This PW Consulting briefing distills the key market dynamics that will matter to executive teams in 2026 — revealing where the value pools are expanding, which competitive moves will shape supplier power, and what operational levers buyers and producers must prioritize. We provide an evidence‑based snapshot of market scale and trajectory while intentionally reserving granular segment tables and regional breakdowns for the full report to preserve the premium intelligence that underpins actionable decisions.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Market snapshot: measured growth, structural transformation
The global market for automotive air‑conditioning compressors has shown steady expansion through the 2020–2025 historical window and is projected to continue growing through the 2026–2032 forecast horizon. On an absolute basis the market increased from about USD 7.3 Billion in 2020 to approximately USD 9.5 Billion in 2025, and our base‑case projection points to roughly USD 12.5 Billion by 2032. This trajectory implies a mid‑single‑digit compound annual growth rate across the forecast horizon (4.05% CAGR for 2026–2032), reflecting the combined effects of electrification, regulatory shifts, and aftermarket replacement demand.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Two structural themes underlie the nominal growth: first, rapid adoption of electrified powertrains forces a re‑architecting of compressor technology (electric compressors, inverter controls, integration with heat pumps). Second, regulatory and sustainability pressures drive refrigerant transitions and efficiency upgrades, raising product complexity and engineering content per vehicle. For 2026 planning cycles, these trends translate into higher technology risk but also clearer pathways to margin enhancement for players who move early on electrified and high‑efficiency platforms.
Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Why this matters for 2026 corporate decisions
- Product roadmap prioritization: Firms making 3–5 year platform bets must align R&D spend with electrified compressor architectures (low‑vibration scrolls, high‑voltage designs, and integrated heat‑pump solutions). Delaying such investments risks OEM disqualification as electrified vehicle content ramps.
- Supply‑chain resilience and cost management: The industry remains exposed to aluminium, steel and copper price volatility. Procurement strategies that combine longer forward contracts, multi‑sourcing, and alloy optimization will materially protect margins through 2026.
- Regulatory compliance as a go‑to‑market driver: Refrigerant phase‑outs and regional regulatory differences mean OEM product specs will diverge across markets. Capturing share requires modular compressor platforms that can be adapted for low‑GWP refrigerants without substantial retooling.
- M&A and partnership prioritization: Market concentration indicators show that a moderate share of demand is clustered among leading suppliers, creating opportunities for bolt‑on acquisitions to accelerate capability in electrified compressors or to access critical OEM engagements.
- Aftermarket and reman strategies: As vehicle parc ages, aftermarket demand remains a steady revenue pool; services and remanufacturing can complement new‑equipment margins and provide recurring revenue during new‑vehicle cyclical downturns.
Competitive landscape: capabilities that decide the next cycle
The competitive map is neither atomized nor monopolistic — leading suppliers hold significant leverage, yet there is still room for technology challengers and regional specialists. Our analysis of core players highlights where each incumbent is positioned and what to expect from them in 2026.
- Sanden Corporation (Isesaki, Japan) — A long‑standing specialist in open scroll and other compressor technologies with deep OEM ties. Sanden’s strength is platform breadth across passenger and light commercial vehicles; their aftermarket channel and legacy relationships make them a default partner when OEMs seek proven reliability in transitional refrigerant environments.
- Hanon Systems (Daejeon, South Korea) — Hanon packages compressors within broader thermal management and HVAC systems, giving them an advantage when OEMs prioritize integration (e.g., combined cabin HVAC and battery thermal management). They are also advancing heat‑pump competencies that will be pivotal for EV HVAC efficiency.
- BorgWarner Inc. (Auburn Hills, USA) — Leveraging heritage from Delphi and systems engineering capability, BorgWarner is positioned around fuel‑economy and emissions outcomes. Their OE relationships and systems approach make them a likely partner for automakers seeking integrated electrified HVAC subsystems.
- MAHLE GmbH (Stuttgart, Germany) — MAHLE’s Compact Variable Compressor (CVC) technology and recent investments in high‑voltage compressors target high‑performance electrified platforms. Their product roadmap signals readiness to supply 800V systems for heavy electrification and fast‑charge thermal scenarios.
- ESTRA Automotive Systems (Daegu, South Korea) — A nimble supplier focused on high‑efficiency designs including variable swashplate and e‑compressor types. ESTRA acts as a technology fast follower and specialist for customers looking to optimize fuel economy and reduce NVH at lower development lead times.
- Mitsubishi Heavy Industries (Tokyo, Japan) — A supplier moving aggressively into electric compressors with scroll‑based, low‑vibration units and inverter controls suited to hybrids and battery electric vehicles. Recent product launches demonstrate their commitment to compact, efficient electric architectures suitable for OEM electrification programs.
Market concentration metrics show the top three suppliers collectively hold a significant portion of demand, while the top five capture roughly two‑thirds of the market. This concentration creates an environment where strategic alliances and targeted M&A can decisively reconfigure supplier position in 2026.
Technology and product trends shaping buy/sell decisions
- Electric compressors and inverterization: Adoption is accelerating across hybrid and battery EVs. Companies that can offer robust, low‑vibration electric scrolls and high‑voltage compatibility will command pricing premiums.
- Heat‑pump integration: Compressors that can be integrated within vehicle heat‑pump cycles offer distinct efficiency advantages and therefore higher specification ceilings from OEMs, especially in cold‑climate models.
- Modularity for refrigerant transitions: Compressor designs that accommodate low‑GWP refrigerants with minimal retooling reduce technical and time‑to‑market risk for OEMs operating across multiple regulatory regimes.
- NVH and reliability engineering: As customer expectations rise and vehicle acoustic standards tighten, low‑vibration designs (scroll and inverter control strategies) become differentiators in OEM supplier selection.
Regulatory and input‑cost headwinds (and how to plan for them)
Key external pressures that should be factored into 2026 budgets and contractual frameworks include:
- Refrigerant regulation: Policy action in regions like the EU is accelerating phase‑out of high‑GWP refrigerants. Manufacturers must be able to certify equipment for approved alternatives and demonstrate lifecycle global warming benefits.
- Raw material volatility: Aluminium, steel and copper price swings remain a principal driver of cost pressure. Hedging strategies, alloy substitution and design for material efficiency are essential mitigants.
- Thermal protector evaluations in hot climates: Thermal safety and protector requirements in extreme‑heat markets may necessitate product adaptations that affect BOM and service approach; such regulatory evaluations should be built into product qualification timelines.
What the full PW Consulting report delivers (practical, not theoretical)
PW Consulting’s comprehensive market study goes beyond directional analysis to provide the operational detail required for 2026 decision making. Key deliverables include:
- Forecast model with base year 2025 and annualized projections through 2032, including sensitivity scenarios for electrification pace and refrigerant regulation adoption.
- Competitive benchmarking across technology capabilities, OEM relationships, and aftermarket reach — with supplier scorecards to identify best‑fit partners for JV, supplier development or acquisition.
- Commercial playbook templates (pricing levers, contract clauses for raw‑material pass‑through, warranty structures for e‑compressors) ready for immediate use in supplier negotiations.
- Go‑to‑market roadmaps for OEMs and Tier‑1s on transitioning platforms to low‑GWP refrigerants and integrating heat pump systems.
- Deal‑flow and M&A heatmap identifying targets, valuation benchmarks, and integration risks for capability‑building transactions.
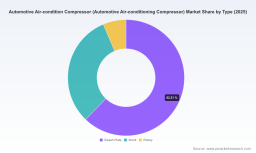
Note: To preserve the value of the underlying market intelligence, detailed regional splits, type‑level volumes and exact segment revenue figures are reserved for the full report and data pack available through our client portal.
Immediate 90‑day actions for executives
- Run a product‑portfolio stress test aligned to an EV‑first and a delayed‑EV scenario; identify which compressor platforms require accelerated investment.
- Implement a commodity risk mitigation plan focusing on aluminium and copper exposures, including a mix of spot coverage, forwards, and strategic hedges linked to production milestones.
- Open two strategic conversations: one with a thermal‑systems integrator (to secure heat‑pump co‑development) and one with a niche electric‑compressor specialist (for technology licensing or minority equity). Prioritize partners that can accelerate time‑to‑market for 800V and inverterized systems.
- Audit compliance readiness for low‑GWP refrigerants in key selling markets and budget a regulatory‑driven product variant program for 2026 production starts.
Conclusion — how PW Consulting helps you convert insight into advantage
For 2026, decisions on R&D allocation, supplier strategy, and M&A will determine which companies capture the higher margins and richer content opportunities arising from electrified HVAC and regulatory change. PW Consulting’s study quantifies the growth trajectory, evaluates competitive positions, and supplies the commercial tools required to act now. If your team is preparing budget sign‑offs, platform investments, or supplier restructurings next year, the full report delivers the segment‑level intelligence and scenario models you will need to de‑risk those choices and capture upside.
Contact PW Consulting to access the complete report and data pack, including downloadable models, supplier scorecards, and an implementation playbook tailored to your role (OEM, Tier‑1, investor, or aftermarket player).
For detailed analysis of this topic, please visit the official page: Automotive Air-condition Compressor (Automotive Air-conditioning Compressor) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com