

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phenoxy Resins Market to Reach USD 186.15 Million by 2032 at 5.8% CAGR

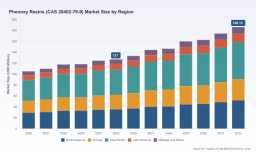
Phenoxy Resins (CAS 26402-79-9): Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s senior strategy advisors, we present a targeted, executive‑grade preview of our comprehensive Phenoxy Resins (CAS 26402‑79‑9) market study. Built on a base year of 2025 and a historical series covering 2020–2025, the report translates granular market intelligence into boardroom-ready guidance for 2026. The study quantifies an established growth trajectory (compound annual growth rate of 5.8% through our 2026–2032 forecast window) and tracks the market’s evolution from its early‑decade baseline to the near‑term inflection points critical to procurement, R&D and M&A choices.
Phenoxy Resins (CAS 26402-79-9) Market
Why this study matters for decisions in 2026
2026 is a turning point: raw material volatility, revised industrial emissions legislation, and accelerating end‑market decarbonization are converging to reshape demand, pricing and product roadmaps for phenoxy resins. Our analysis synthesizes these forces into actionable scenarios for commercial leaders and technical executives.
Phenoxy Resins (CAS 26402-79-9) Market
-
Clear market momentum. Our end‑to‑end model captures the market’s steady expansion since 2020 and its projected continuation through 2032 at a mid‑single digit CAGR. This macro trajectory is not evenly distributed — pockets of accelerated demand, shifting formulations and margin compression are already visible to well‑positioned players.
Phenoxy Resins (CAS 26402-79-9) Market -
Regulatory and cost inflection points. With tighter VOC limits finalized for industrial coatings in recent years and raw material exposure to petrochemical cycles, immediate and medium‑term strategic moves will determine which firms protect margins and which cede share.
-
Competitive concentration. The market exhibits moderate concentration among leading producers; this structure creates both defensive and opportunistic paths for new entrants and incumbents pursuing adjacencies or scale plays.
What the full report delivers — practical, transaction‑ready content
We designed the study as a practitioner’s toolkit. The full deliverable provides the evidence base and operational templates that support decisions across procurement, product management, M&A and compliance programs. Highlights include:
-
Robust market sizing and trend decomposition (historical 2020–2025 and forecast 2026–2032), including scenario variants that stress raw material shocks, VOC‑driven reformulation and accelerated electrification in automotive and electronics.
-
Demand driver analytics by end‑use and formulation class, with elasticity estimates and price sensitivity matrices for customer segments.
-
Supply chain heatmaps and supplier scorecards that benchmark feedstock exposure, contract vulnerability, logistics risk and capacity flexibility.
-
Regulatory impact playbooks — compliance cost estimates, reformulation timelines, and a prioritized list of technical experiments to accelerate water‑based and low‑VOC offerings.
-
Commercial playbooks: value‑based pricing frameworks, distributor/channel strategies, tender defense templates and go‑to‑market options for differentiated grades.
-
M&A and partnership screening: criteria‑based lists of strategic targets, integration risk checklists and synergies models calibrated to typical consolidation pathways in this resin space.
-
Operational KPIs and a dynamic forecasting model (delivered as a client tool) that allows sensitivity testing across feedstock, pricing, capacity and product mix assumptions.
Market dynamics shaping 2026 strategies
Several structural and episodic forces should frame any 2026 strategy:
-
Upstream raw material volatility. Bisphenol A and epichlorohydrin remain principal feedstocks. Their exposure to broader petrochemical cycles creates recurring margin pressure for resin producers and requires disciplined procurement and hedging strategies by buyers and sellers alike.
-
Regulatory tightening. The EU’s updated Industrial Emissions Directive and stricter VOC rules for large coating operations are accelerating reformulation toward water‑borne solutions. Firms that anticipated this trend and invested in low‑VOC grades have clearer commercial momentum; laggards face either accelerated R&D expense or loss of market access in regulated jurisdictions.
-
Formulation shifts. The technical tradeoffs between solvent‑based and water‑based phenoxy chemistries — performance, processing and life‑cycle emissions — are driving differentiated product plays. Successful players combine laboratory know‑how with application engineering to reduce customer switching costs.
-
Pricing events and margin management. Recent producer actions illustrate the tight link between feedstock and list prices; for example, global price revisions for epoxy and phenoxy products in 2026 underscore how manufacturers manage margin erosion when naphtha and logistics costs spike. Strategic pricing discipline and contract clauses for pass‑throughs are now table stakes.
-
Concentration and competitive dynamics. The market’s top‑tier consolidation creates an environment of selective collaboration and competitive differentiation. A moderate top‑three/top‑five concentration level means scale matters for feedstock sourcing and global customer programs, but nimble specialists can still capture premium niches.
Competitive landscape — profiles that matter in 2026
Our competitive analysis synthesizes public disclosures, primary interviews and commercial win/loss data to map strategic positioning for the leading producers. Selected profiles:
-
DIC Corporation (Tokyo, Japan) — A diversified chemical platform offering phenoxy resins within its epoxy and specialty resin portfolio. Strengths include global customer reach and integrated sales channels; near‑term focus areas include margin preservation via price adjustments in response to feedstock cost inflation. ( https://www.dic-global.com/en/)
-
Mitsubishi Chemical Corporation (Tokyo, Japan) — Known for high‑molecular‑weight phenoxy grades marketed under a recognized brand for electronics, semiconductor packaging and automotive applications. Their competitive edge is engineering depth and customer co‑development for high‑performance segments. ( https://www.m-chemical.co.jp/en/)
-
Kukdo Chemical (Seoul, South Korea) — A leading producer with solution and solid grades tailored to electronics and industrial coatings. Kukdo’s strengths are cost‑competitive production and rapid response product development for regional OEMs. ( https://www.kukdo.com/en/)
-
Gabriel Performance Products (Akron, Ohio, U.S.) — Supplier of specialty PK‑series and micronized phenoxy resins, now operating within a larger chemical platform. Gabriel is positioned to serve technical coatings and adhesives markets where micronization and handling properties create differentiation. ( https://www.gabepro.com/)
-
Nan Ya Plastics Corporation (Taipei, Taiwan) — Integrated resin producer with downstream epoxy capabilities; capability to offer combined resin systems provides commercial leverage in adhesives and performance materials. ( https://www.nypc.com.cn/)
-
Hexion Inc. (Columbus, Ohio, U.S.) — Offers phenoxy resins within a wide resin portfolio for automotive and electronics segments; scale and application engineering are key competitive assets. ( https://www.hexion.com/)
Across these firms, the strategic levers are consistent: feedstock management, formulation leadership (especially water‑based), service and application engineering, and selective capacity investments. The market concentration profile supports both scale plays and targeted differentiation.
Recommended strategic moves for 2026
For executives making 2026 commitments, our pragmatic recommendations are prioritized by impact and execution horizon:
-
Immediate (0–6 months): embed feedstock pass‑through clauses into new contracts; run stress tests on existing contracts against a high‑price petrochemical scenario; launch a pricing‑defense task force to protect margins without sacrificing share.
-
Near term (6–18 months): accelerate development and commercialization of water‑based phenoxy grades where regulatory exposure is highest; co‑fund application trials with key customers to reduce adoption friction; reconfigure supply agreements to include flexible volumes and alternative sourcing options.
-
Medium term (12–36 months): evaluate bolt‑on acquisitions or strategic JV partners that supply epoxy or complementary resins to create system‑level offerings; invest selectively in micronization and powder processing capabilities where handling and formulation benefits command premium pricing.
-
Organizational: create a cross‑functional “resin strategy” cell combining procurement, R&D and commercial teams to operate the scenario model and execute rapid reprioritization as feedstock and regulation landscapes evolve.
How PW Consulting’s report unlocks decision value
Our study is designed to convert insight into execution. Beyond the market narrative, clients receive: a calibrated forecasting model with scenario toggles; supplier and target screening matrices; technical ranking criteria for reformulation projects; and a regulatory readiness checklist that ties compliance actions to product launch timelines. For leadership teams, the report functions as both a situational diagnostic and an operational playbook — enabling faster, evidence‑backed decisions in 2026.
We intentionally limit this preview to strategic conclusions and high‑level metrics to preserve the proprietary, segment‑level intelligence that drives competitive advantage. For full access to the detailed segmentation, end‑use breakouts, pricing ladders and company‑level share analysis that underlie these conclusions, please consult the report landing page.
Conclusion
Phenoxy resins are at an inflection. The combination of steady market growth, petrochemical cost exposure, regulatory tightening and application‑level shifts presents clear winners and losers in 2026. Companies that couple disciplined margin management with targeted technical investments — particularly in low‑VOC and water‑borne solutions — will secure preferred supplier status and superior returns. PW Consulting’s full study equips decision‑makers with the market maps, financial models and implementation templates necessary to navigate this next phase with confidence.
For detailed analysis of this topic, please visit the official page: Phenoxy Resins (CAS 26402-79-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com