

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Healthcare & Medical System Integrators Market to Expand at 11.02% CAGR

Healthcare and Medical System Integrators Market: Strategic Playbook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive introduction to our newest market research on Healthcare and Medical System Integrators. This preview outlines the strategic value the full study delivers to leaders making investment, procurement, partnership, and M&A decisions in 2026. It demonstrates the analytic depth of our work while preserving high‑value segment tables and proprietary breakouts for the full report—available on our site.
Healthcare and Medical System Integrators Market
Why this research matters for 2026
-
Healthcare system integration is no longer a back-office IT expense; it is an operational enabler shaping care delivery, regulatory compliance, and commercial models.
Healthcare and Medical System Integrators Market -
Decision windows in 2026 are compressed: budgets set in H1 drive vendor selection and platform bets that will determine interoperability posture for the next 3–5 years.
Healthcare and Medical System Integrators Market -
Our study frames those decisions with a forward-looking economic lens—quantifying market growth, profiling competitive moves, and translating regulations into operational checklists.
Market trajectory at a glance
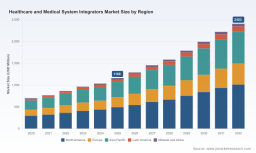
We model the integrator market with a robust historical series (2020–2025) and a seven-year forecast (2026–2032). Key topline sizing shows the market expanding from USD 700.5 Million in 2020 to USD 1,160.0 Million in 2025 (base year). Under our central scenario, the market grows at a compound annual growth rate (CAGR) of 11.02%—reaching USD 1,287.8 Million in 2026 and roughly USD 2,403.0 Million by 2032.
That growth is not linear; it reflects accelerating investments in cloud-native interoperability, AI-enabled EHR elements, and facility modernization programs that spike spending in 2026–2029. For buyers and investors, the implication is clear: the market is large enough to support specialist players and converging platform strategies, and rapid enough to punish delayed procurement cycles.
What the report delivers—practical, actionable content
We designed the report for operators, CIOs, acquirers, and strategy teams who need executable guidance, not only descriptive analysis. The full deliverable contains:
-
Proprietary market model with historicals and scenario-driven forecasts—downloadable and modifiable for custom sensitivity testing.
-
Vendor benchmarking and capability matrices that score providers across interoperability, clinical integration, device connectivity, managed services, and cloud operations.
-
Implementation playbooks: phased roadmaps, staffing profiles, procurement templates, and a risk mitigation checklist tailored to hospital systems and integrated delivery networks.
-
Regulatory and compliance mapping for US and EU markets—linking certification milestones to procurement triggers and contract clauses.
-
M&A and partnership tracker with deal valuations, strategic rationale, and integration risk assessments to support target screening and diligence.
-
Case studies and ROI models illustrating typical cost-to-value trajectories for horizontal consolidation vs. vertical integration approaches.
Competitive landscape—what incumbents and challengers are doing
The landscape is a blend of specialist integration engine providers, systems integrators with healthcare focus, and platform vendors moving into adjacent integration layers. Our competitive chapter profiles each major player with primary offerings, go-to-market motions, and strategic priorities. Highlights include:
-
iNTERFACEWARE Inc (Toronto): Known for its Iguana integration engine and a strong reputation in EHR interoperability and medical device data flows. Recent trade show and user‑community activity through HIMSS and its Iguana User Conference underline an emphasis on customer enablement and ecosystem stickiness.
-
Burwood Group, Inc (United States): A specialized IT consulting and integration firm now operating within a larger professional services umbrella following its strategic move to join Sikich—reinforcing a playbook focused on value‑based care enablement via integrated IT services.
-
FORTÉ (formerly AVI Systems, Minneapolis): Transitioned branding to signal broadened capabilities across collaboration and medical facility integration; the repositioning reflects an intent to capture consultative AV-led projects that interface with clinical workflows.
-
InterSystems Corporation (Boston): Continues to bridge enterprise information systems and clinical workflows; importantly, it has advanced AI-native EHR concepts and announced certification progress relevant to EU device regulation, positioning it for cross-border deployments where regulation is a gating factor.
-
Veradigm LLC (Chicago): Focused on connected care platforms and EHR integration, emphasizing data privacy and interoperability compliance as critical procurement differentiators in US and EU markets.
Collectively, the market exhibits moderate concentration: our competitive analysis estimates that the top-three players account for a meaningful share of the market, and the top-five increase that share further—indicative of an environment where scale and end‑to‑end capabilities influence large health system decisions. (Our summary metrics report a CR3 of 55% and a CR5 of 68%.)
Market dynamics and risks you must prioritize
Adoption drivers and systemic risks are tightly coupled in this market. Key dynamics covered in the report include:
-
Interoperability and standards: Payors and regulators are elevating expectations for data portability and certified interfaces—making compliance a procurement prerequisite, not a checkbox exercise.
-
Regulatory complexity: Vendors are adapting to region-specific certification regimes and device regulation. Recent vendor announcements signal progress on certification and KLAS-rated performance, but buyers should validate claims against audited evidence.
-
Technology convergence: AI-native EHR modules and cloud-first integration platforms change the supplier landscape; organizations must decide between incremental integration upgrades or platform replacement strategies.
-
Cost of expertise and workforce constraints: Skilled integration architects are scarce, elevating managed service models and vendor-provided implementation teams as viable options to accelerate time-to-value.
-
Consolidation and partner ecosystems: Strategic acquisitions and rebrands are reshaping go-to-market routes; expect more roll-ups and vertical moves as integrators seek scale and cross-sell synergies.
Scenarios for 2026 planning
Using our model and client workshops, we present three actionable scenarios that executives can adopt in 2026:
-
Consolidation Play: For systems seeking cost efficiencies—prioritize vendor rationalization, invest in a dominant integration platform, and negotiate long-term managed services to offset workforce scarcity.
-
Best-of-Breed Play: For organizations focused on rapid innovation—layer specialized engines for device telemetry and AI components on top of robust APIs, accepting higher integration overhead for advanced capabilities.
-
Regulatory-First Play: For cross-border health systems—sequence investments to prioritize certified components and compliance-driven integrations to avoid retrofitting costs and market entry delays.
The intelligence you won’t find in this preview (but will in the full report)
To preserve the strategic value of our proprietary work, this introduction deliberately omits the granular regional, type, and application-level breakouts that clients use for precise deal sizing and RFP scoping. The full report contains:
-
Regional and application revenue splits with trend-level granularity and confidence intervals.
-
Vendor scorecards with weighted capability scores and sourcing recommendations by buyer archetype.
-
A downloadable financial model and scenario files to adapt the forecast to your own assumptions.
These elements move the conversation from high-level strategy to procurement actions, risk‑reduction design, and diligence-ready analytics.
Implications and recommended next steps for 2026
-
Embed interoperability as a procurement criterion—require audited performance metrics and compliance evidence as part of RFPs.
-
Prioritize integration pilots that demonstrate clinical workflow benefits within 6–9 months; use those pilots to inform platform vs. point-solution decisions.
-
Build M&A watchlists and partnership funnels aligned to your strategic play (consolidation, best-of-breed, regulatory-first) and stress-test potential targets against the market’s 11%+ growth trajectory.
-
Reserve budget for managed services and talent partners—scarcity of skilled integrators will continue to drive premium for implementation capacity.
-
Request the detailed appendices and model from PW Consulting to convert the findings into a bespoke implementation roadmap and vendor shortlist.
Closing—how to use this insight
In 2026, winners will be the organizations that treat systems integration as a strategic asset: aligning vendor choices with regulatory trajectories, clinical outcomes, and long-term platform economics. This preview lays out the strategic contours; the full PW Consulting study supplies the necessary data, vendor assessments, and executable templates to move from strategy to procurement and execution.
To access the complete report, the downloadable model, and vendor scorecards, please visit the PW Consulting report page—where clients can also schedule a briefing with our advisory team to translate findings into a 90‑day action plan for 2026.
For detailed analysis of this topic, please visit the official page: Healthcare and Medical System Integrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com