

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicon Nitride Ceramics Market to Grow at 6.86% CAGR (2026–2032)

Silicon Nitride Ceramics Market: Strategic Imperatives for 2026 Decision-Makers
As advanced materials converge with electrification, high-speed computing, and high-reliability manufacturing, silicon nitride (Si3N4) ceramics are moving from niche engineering curiosity to strategic line item on corporate roadmaps. PW Consulting’s latest market study—anchored on a 2025 base year and a detailed historical review from 2020–2025, with scenario-driven forecasts through 2032—translates that structural shift into actionable intelligence for executives planning capital allocation, product roadmaps, supply-chain redesign, and M&A in 2026.
Silicon Nitride Ceramics Market
Headline market context (what we measured)
Our macro model shows steady expansion over the past half-decade: the global silicon nitride ceramics market grew from a low three-figure base in 2020 to a materially larger market by the 2025 base year. Looking forward, the market is forecast to grow across the 2026–2032 horizon at a compound annual growth rate of 6.86%, reaching the high two-hundred‑million USD scale by 2032 in our central scenario. These headline dynamics are driven by technology-led demand in mobility electrification, power electronics, semiconductor manufacturing, and medical implants—each of which exerts different technical and commercial requirements on silicon nitride materials and processing.
Silicon Nitride Ceramics Market
Why this matters for 2026 decisions
- Capital allocation: The projected mid-single-digit CAGR and the sector’s step-change demand profile mean that capacity investments have multi‑year payback profiles but are sensitive to lead times, raw-material swings, and regulatory cost inflation. Companies that allocate capital without integrated supply‑chain modelling risk both underutilization and missed early-adopter opportunities.
- Supply‑chain resilience: Standard-grade Si3N4 powder supply is geographically concentrated, creating systemic risk vectors for companies that depend on “just-in-time” procurement. In addition, metallurgical silicon feedstock and nitrogen inputs have demonstrated price volatility in prior years—our modelling captures single‑year swings that can materially alter gross margins at the manufacturing node.
- Technology positioning: Advanced applications—power semiconductor substrates, EV bearings, and biomedical implants—require different processing routes and certification pathways. Firms that hedge across process technologies while securing tight technical partnerships with OEMs can convert incremental material performance improvements into differentiated, higher-margin product lines.
What PW Consulting’s report delivers (practical contents)
The full study is purpose-built to support board-level and operational decisions in 2026. It is organized to be directly actionable rather than purely descriptive, and includes:
Silicon Nitride Ceramics Market
- Executive synthesis and scenario planning (base, upside, downside) aligned to macroeconomic, energy, and raw-material stress tests.
- A detailed historical market model (2020–2025) and a transparent forecasting engine (2026–2032) with driver-level inputs so clients can re-run scenarios with proprietary assumptions.
- Supply-chain mapping and sensitivity models covering powder-to-component conversion, sintering and hot-press routes, and advanced additive manufacturing flows.
- Regulatory and ESG risk matrix focused on emissions and waste streams from nitride production, plus practical mitigation playbooks for compliance and cost control.
- Competitor and capability assessment with profiles of the leading technology providers, manufacturing specialists, and materials integrators—highlighting strategic strengths, technological edges, and likely moves in the next 12–18 months.
- Commercial go-to-market playbooks for three archetypal companies: incumbent manufacturers, materials specialists, and new entrants with licensing/R&D-first strategies.
- M&A and strategic partnership frameworks, including valuation sensitivities when raw-material volatility or capacity under-commitment is a factor.
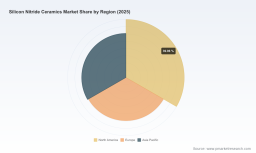
To honour the “trailer” principle and preserve the value of our proprietary segmentation work, this overview deliberately omits detailed region-by-region and application-by-application breakdowns; those granular deliverables are available in the full report and interactive models.
Competitive landscape: who matters and why
The market demonstrates a mix of long-established ceramics manufacturers, materials innovators, and diversified industrial groups. Competitive dynamics are driven less by a single dominant global player and more by differentiated technical portfolios, capacity footprints, and market access to high-growth end markets.
- KYOCERA Corporation (Tokyo) — deep IP in fine Si3N4 ceramics for bearings, seals, and wear applications. Their recent launch of an optimized Si3N4 grade designed for extreme thermal‑mechanical loads underscores a strategy of product-led wins in mobility and industrial applications.
- CoorsTek Inc. (Golden, CO) — specializes in tight‑tolerance silicon nitride components and engineered balls/blanks for high-stress uses. Their capability to manufacture components to extreme dimensional and material standards positions them for growth where performance limits are the gating factor.
- SINTX Technologies (Salt Lake City, UT) — active at the intersection of industrial and biomedical applications, with FDA‑registered implants and emerging partnerships for 3D‑printed components. Their recent supply agreement targeting Si3N4‑polymer compounds for additive manufacturing highlights the growing convergence of materials and digital manufacturing.
- CeramTec GmbH (Landsberg am Lech) — offers substrates for power electronics and structurally robust high‑temperature components. Their portfolio is tuned to the needs of electrification and high-power semiconductor packaging.
- Morgan Advanced Materials, 3M, Denka, UBE, Toshiba Materials/Niterra, and International Syalons — these firms combine materials breadth, process know-how, and in several cases, global manufacturing footprints. Recent moves—capacity expansions and corporate restructuring—signal a defensive and offensive positioning ahead of projected demand growth.
Recent corporate developments captured in our study provide leading indicators of where supply and capabilities are headed. Examples include new material introductions tailored for high-stress seals and bearings, capacity increases aimed at automotive demand, supply agreements integrating Si3N4 into polymer matrices for additively manufactured implants, and strategic acquisitions that consolidate capabilities for EV bearings and power‑electronics substrates.
Industry dynamics and risk map
- Raw-material volatility: Metallurgical silicon and nitrogen-feedstock sourcing drive much of the cost-base. Our stress scenarios account for volatility spikes that have historically exceeded single‑year double‑digit swings, with direct pass-through implications for component-level pricing.
- Geopolitics and concentration risk: A significant share of standard-grade powder production is regionally concentrated, creating exposure to export control risk and trade friction. For manufacturers this elevates the strategic value of diversified sourcing and local buffer capacity.
- Regulatory pressure: Tighter environmental standards for nitride production raise both capex and opex for powder and component manufacturers; firms that front-load cleaner processes gain both compliance certainty and lower long-run operating risk.
- Labor and process complexity: High‑temperature sintering and specialty finishing require skilled labor—another bottleneck that can lengthen lead times and increase fixed costs.
Priority strategic moves for 2026
Based on our modelling and client engagements, PW Consulting recommends executives prioritize a short list of pragmatic actions in 2026 to navigate the period of sustained growth and elevated uncertainty:
- Run integrated supply-cost scenarios before committing capital: Test plant expansions and contract terms against raw-material and energy stress cases; use staged investment triggers linked to demand milestones.
- De-risk feedstock sourcing: Diversify powder suppliers and evaluate on-shore blending/repurposing strategies to reduce exposure to export constraints and single-source failures.
- Enter targeted technology partnerships: Collaborate with OEMs in EV, power electronics, and medical devices to co-develop specs that secure offtake and accelerate certification timelines.
- Prioritize process automation and workforce upskilling: Reduce unit-cost sensitivity to specialized labor and shorten ramp-up timelines for new capacity.
- Use M&A defensively and offensively: Pursue tuck-ins for process know-how or regional capacity where time-to-market matters; retain capital discipline and insist on scenario-based valuation adjustments tied to material-price pathways.
- Layer regulatory and ESG compliance into product pricing: Shift from viewing environmental upgrades as cost centers to treating them as market-access enablers that can justify premium positioning in regulated end markets.
How the full PW Consulting study helps you act
The full report provides the granular inputs and validated assumptions you need to translate the strategic moves above into board-level decisions: a modular financial model, supplier risk heatmaps, a prioritized target list for technical partnerships and M&A, and commercially tested go-to-market playbooks for materials, components, and system integrators. The public summary you are reading is designed to signal the depth and orientation of our work; the proprietary sections—segment-level demand by application and region, supplier scorecards, and live scenario models—are available to licensed clients who require immediate, executable recommendations for 2026.
If your 2026 plan depends on supply security, differentiated material performance, or timely certification in tightly regulated end markets, the decisions you make in the coming 12 months will define your market position for the remainder of the decade. PW Consulting’s silicon nitride ceramics study is built to convert market signals into defensible, executable strategy—backed by scenario-protected financials and a cross-functional playbook for operations, procurement, R&D, and corporate development.
Contact PW Consulting to access the interactive model and the full report to see the segmentation and granular forecasts that support board-level investment and transaction decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Silicon Nitride Ceramics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com