

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Atomizing Copper Powder Market to Hit $494M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-13
Atomizing Copper Powder Market: Strategic Imperatives for 2026 Decision‑Making
Executive Teaser
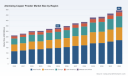
The atomizing copper powder market stands at a strategic inflection point as 2026 begins. PW Consulting’s new market study—anchored on a 2025 base year—projects the market to expand at a compound annual growth rate (CAGR) of 5.8% through 2032, with the addressable global market rising from a 2025 baseline to a materially larger value by 2032. Historical momentum from 2020–2025 underpins this trajectory, while today’s supply, regulatory and technology dynamics are re‑shaping near‑term choices for manufacturers, OEMs and investors. Market concentration remains low-to-moderate (CR3 ≈ 26.5%, CR5 ≈ 33.2%), signalling a fragmented supply landscape with differentiated technical and commercial niches—conditions that favour both targeted consolidation and nimble niche plays.
Atomizing Copper Powder Market
Why This Research Matters for 2026 Strategic Decisions
Executives and investment committees will confront high‑stakes choices in 2026: whether to greenfield or brownfield expand capacity, how to secure long‑term feedstock in a volatile raw‑material environment, which product grades to prioritize for additive manufacturing versus traditional powder metallurgy, and how to balance regulatory compliance with unit economics. This study is designed as a decision‑grade resource for these priorities. It translates market-level growth into scenario‑specific demand curves, risk matrices and executable playbooks so that procurement, R&D, operations and corporate development teams can move from hypothesis to investment-ready options within weeks—not months.
Atomizing Copper Powder Market
- Capital allocation: rapid screening of CAPEX alternatives with payback windows and sensitivity to metal price scenarios.
- Supply resilience: supplier scorecards and alternative sourcing pathways to mitigate feedstock volatility.
- Product strategy: priors for alloy and particle‑morphology development tied to high‑value end uses.
- Regulatory readiness: compliance roadmaps to limit the 2026‑era drag from environmental standards on powder handling and facility upgrades.
Primary Market Dynamics to Watch
Three converging dynamics will dominate boardroom conversations in 2026.
Atomizing Copper Powder Market
- Raw‑material volatility and pricing pressure. Industry production metrics show a substantial global throughput of atomized copper powder in the mid‑tens of thousands of metric tonnes annually and a market price environment that has oscillated materially through 2024–2025. The report models multiple pricing paths and the implications of each for margins across manufacturing routes (atomization vs electrolytic).
- Regulatory and compliance headwinds. Environmental regulation and stricter standards for metal powder handling are a real operational constraint: compliance-related constraints are already a primary contributor to capital project slowdowns and are explicitly modelled as a driver of retrofit timing and cost increases in the study.
- Technology and end‑market transition. Adoption of additive manufacturing (AM), higher‑performance powder metallurgy grades and advanced electrical/thermal applications is re‑shaping the demand mix. The research quantifies adoption pace and the premium attached to manufacturing‑ready powder specifications (particle size distribution, oxygen content, morphology) without disclosing proprietary segment-level values in this summary.
What the Report Contains — Practical, Executable Modules
The study is built as an operational toolkit for 2026 execution. Highlights include:
- Market sizing and forecast model (2020–2032) with scenario toggles—base, downside, and accelerated adoption scenarios—allowing users to test bespoke assumptions.
- Supply‑side mapping: detailed mill and route‑type coverage, manufacturing footprints, capacity estimates, and regional logistics overlays.
- Price and margin simulations: forward curves tied to metal cost drivers, energy inputs and regulatory compliance costs.
- Segment demand models by end application and grade (proprietary split tables included in the full report).
- Supplier scorecards and procurement playbooks: technical capability, quality certifications, commercial terms and suggested RFP templates.
- Facility upgrade and compliance playbook: CAPEX/OPEX models for emissions control, dust handling, and personnel safety tailored to common plant typologies.
- M&A and partnership roadmap: target archetypes, valuation heuristics and integration checklists designed for buyers and JV partners.
- Three strategic scenario playbooks and a 24‑month readiness checklist aligned to prioritized decisions (capacity, supplier contracts, regulatory upgrades).
Competitive Landscape — How Incumbents and Challengers Are Positioning
The sector is populated by specialists spanning legacy metal‑powder makers, advanced materials firms and regional aggregators. Our competitive analysis synthesizes public disclosures, site visits, and primary interviews to identify capabilities, strategic positioning and likely next moves for key players:
- Kymera International (Research Triangle Park, NC, USA; https://kymerainternational.com) — A technology‑led producer of both gas and water atomized copper powders. Strengths include AM and critical‑sector supply chains (medical, energy). Expect continued emphasis on qualification for high‑value applications and US‑based supply continuity.
- Pometon S.p.A. (Italy; https://www.pometon.com) — European specialist in water atomized powders and custom alloyed grades, with go‑to‑market focus on solar and EV supply chains. Their advantage is alloy customization and integration with downstream sintered part makers.
- Fukuda Metal Foil & Powder (Yamashina, Kyoto, Japan; https://www.fukuda-kyoto.co.jp/en) — Precision non‑ferrous powders, differentiated by tight quality control and certifications that appeal to electronics and medical segments.
- GRIPM Powder Materials (Beijing, China; https://en.gripm.com) — Integrated producer using atomization and electrolytic routes. Notably, a new facility in Thailand became operational in late 2024, expanding regional capacity and logistics options—an important strategic move for regional buyers seeking Nearshore alternatives.
- American Chemet Corporation (USA; https://www.americanchemet.com) — Concentrated on powder metallurgy grades for industrial customers; an attractive partner for sintered part suppliers.
- GGP Metal Powder AG (Germany; https://www.ggp-metalpowder.com) and Carl Schlenk AG (Germany; https://www.schlenk.de) — European players with a focus on AM and traditional powder metallurgy, respectively, where manufacturing quality and European regulatory compliance are differentiators.
- Mitsui Mining & Smelting (Tokyo, Japan; https://www.mitsui-kinzoku.com) and Makin Metal Powders (UK) (Rochdale; https://www.makin-metals.com) — Established suppliers with deep technical know‑how and selective exposure to specialty alloys and sintered component markets.
Collectively, the competitive field exhibits capability clustering—technical leadership in AM and custom alloys, regional cost advantage in Asia, and precision/quality strengths in Japan/Europe. These patterns create concrete pathways for buyers: qualifying a technical leader for high‑spec grades, contracting regional low‑cost suppliers for commodity grades, and layering inventory or offtake agreements to manage supply risk.
Strategic Implications and Recommended 2026 Actions
For executives planning 2026 moves, the report supports a short list of high‑impact actions:
- Implement a two‑track sourcing strategy: secure a core volume under medium‑term contracts with quality‑assured partners, and maintain a flexible secondary supplier pool to arbitrate spot volatility.
- Prioritise grade development linked to high‑value end users (e.g., AM‑ready powders), supported by co‑development agreements to shorten qualification timelines.
- Fast‑track compliance investments where regulatory risk threatens production continuity; use our retrofit cost templates to compare staged upgrades vs full replacements.
- Evaluate targeted M&A or capacity share deals to lift CR and access proprietary metallurgy capabilities—build the financial model on the range of scenarios the report provides.
- Convert market forecasts into procurement hedge triggers: deploy hedges or index‑linked contracts when modelled price thresholds are breached.
How PW Consulting’s Study Enables Execution — The Teaser
Our research is engineered to move organisations from insight to implementation. The full study includes download‑ready spreadsheets, supplier scorecards, RFP templates, CAPEX/OPEX calculators and a shortlist of actionable targets for strategic partnerships or acquisition. Importantly, while this article outlines the high‑value insights and the strategic frames, detailed segment tables (regional splits, type‑by‑application breakdowns, and contract‑level pricing scenarios) are intentionally withheld here to preserve the integrity of our proprietary models and to direct decision‑makers to the full intelligence package.
If you are evaluating capacity decisions, negotiating multiyear supply agreements, planning regulatory upgrades, or sizing an M&A play in 2026, PW Consulting’s Atomizing Copper Powder Market study provides the calibrated, decision‑grade inputs and playbooks to act with conviction. Access the full report to obtain the granular tables, scenario workbooks, and supplier contact mappings that underpin the strategies summarized above.
For detailed analysis of this topic, please visit the official page: Atomizing Copper Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aliphatic Isocyanates Market to Grow at 8.6% CAGR to USD 138.9M by 2032
By pmarketresearch, 2026-07-13
Aliphatic Isocyanates Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive primer on our Aliphatic Isocyanates Market study (base year 2025, historical window 2020–2025, forecast 2026–2032). This briefing is designed for executives who need immediate, actionable perspective heading into 2026: what the market trajectory implies for portfolio choices, supply-chain posture, regulatory readiness, and near-term M&A or partnering priorities. The piece demonstrates the analytical depth of our full study while intentionally withholding granular segment-level tables and proprietary splits — the precise, transaction-grade intelligence is available in the full report.
Aliphatic Isocyanates Market
Market trajectory at a glance
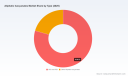
The global aliphatic isocyanates market has moved from a modest base in 2020 toward accelerating commercial relevance by 2025. Our firm-level reconciled series shows an increase from roughly USD 51.6 million in 2020 to USD 78.3 million in 2025. Under the scenarios embedded in this study, the market is expected to continue expanding through the forecast window, reaching an estimated USD 85.3 million in 2026 and projecting to approximately USD 138.9 million by 2032 — a compound annual growth rate of 8.6% for the forecast period.
Aliphatic Isocyanates Market
Those topline numbers mask meaningful structural shifts: demand is being reshaped by sustainability-driven formulation changes (low-VOC waterborne systems), by industrial coatings uptake in transport and infrastructure, and by higher-value specialty hardeners for two-component (2K) polyurethane coatings. For 2026 planning, this combination of steady baseline growth and product-value migration is the critical context for capital allocation and commercial strategy.
Aliphatic Isocyanates Market
Why this study matters for 2026 decisions
- Risk-weighted growth outlook: The 8.6% CAGR and year-on-year projections provide an actionable revenue map for product investment and capacity decisions. They enable realistic ramp plans for specialty grades versus commodity streams.
- Supply-chain sensitivity: Our modeling integrates feedstock volatility and regulatory cost drivers so procurement teams can stress-test contracts and hedging approaches before capital commitments.
- Regulatory and market-access playbook: The study translates recent regulatory events into compliance timelines and market access thresholds for coatings and transport sectors.
- Competitive positioning matrix: We provide a pragmatic view of where to compete — specialty performance, formulation systems, or price-led commodity plays — and the capability investments required for each path.
Dynamics reshaping the market (what to watch in 2026)
Four interlocking forces will determine winners and losers through 2026 and beyond:
- Raw-material and cost pressure: Feedstock swings materially affect margins in both specialty and commodity segments. Spot moves in late 2025 underscored how feedstock cost shocks can erode margin for unsecured supply positions and favor vertically integrated manufacturers.
- Regulatory tightening: Global regulatory regimes continue to converge on worker protection and emissions standards. European REACH updates and tightened training requirements for diisocyanates are operational realities; transatlantic compliance and California-level VOC/transport coatings standards are already shaping product roadmaps.
- Consolidation and concentration: The market remains concentrated: incumbents control a large majority of global capacity, which compresses competitive dynamics in core commodity grades while opening niches for differentiated specialty chemistries and service models.
- Asia-based capacity and pricing pressure: Competitive pressure from cost-advantaged producers in Asia is changing the dynamics of margin pools, particularly in commodity HDI/IPDI grades. At the same time, several Asian players are moving up the value chain with low-VOC, solvent-free offerings for transport and industrial coatings.
What the full report delivers (operational content)
- Robust market-sizing methodology and reconciled historical series (2020–2025) plus scenario-driven forecasts (2026–2032).
- Demand-driver analytics by end-use (coatings, adhesives, sealants and industrial applications) tied to real-world adoption curves and substitution elasticities.
- Supply-side mapping with plant-level capacity overlays, utilization scenarios, and a supplier concentration assessment that underpins competitive strategy.
- Cost-to-serve and feedstock sensitivity models that allow procurement and finance teams to stress-test margins under alternate price and carbon-cost trajectories.
- Regulatory impact matrix with compliance timelines, required product adjustments, and an operational checklist to de-risk market access.
- Commercial playbooks: go-to-market segmentation, distributor network design, and price-pack architecture for specialty versus commodity portfolios.
- Transaction intelligence: a screened list of M&A and JV targets, integration risk diagnostics, and expected payback ranges under conservative and aggressive scenarios.
- Action-oriented appendices, including supplier scorecards, negotiation playbooks for long-term offtake, and a prioritized 18-month implementation roadmap for market entry or defense.
Note: this primer omits the granular regional and application split tables and price-by-grade matrices that are part of the full deliverable; those core segmentation data are intentionally withheld here to protect the commercial value of the study and to drive direct engagement.
Competitive landscape — strategic readouts
The competitive field blends large integrated chemical groups, specialty isocyanate producers, and regional players scaling fast. Key strategic postures observed across the competitive set include:
- Global integrators (e.g., BASF, Covestro, Evonik): Broad product portfolios, strong R&D pipelines, and global distribution networks. Their advantage lies in formulation systems, combination offerings, and the ability to internalize some feedstock volatility through integration or long-term feedstock contracts. Expect continued emphasis on low-VOC and performance-grade lines targeted at premium coatings customers.
- Cost-advantaged regional champions (e.g., Wanhua): Rapid scale-up of competitive portfolios and expanded distribution agreements in Europe and neighboring markets. These players are increasingly pushing solvent-free, low-viscosity formulations suitable for modern transport coatings standards; their strategy mixes cost leadership with selective product innovation.
- Specialty-focused producers (e.g., Vencorex, niche Japanese producers): Focused on high-value hardeners and application-specific grades (2K waterborne polyurethanes, adhesives) where formulation expertise and certification speed are barriers to entry.
- Large chemical majors (e.g., Dow, Huntsman, Mitsui): Use broader chemical ecosystems to offer bundled solutions and to target industrial customers with lifecycle service propositions — a differentiator in large OEM accounts.
- Emerging & regional manufacturers: Some Chinese and Eastern European firms are closing quality gaps rapidly and pursue growth through local partnerships and aggressive pricing in commodity segments.
The market’s concentration dynamics — where the top few suppliers command a decisive share of capacity and sales — mean that challengers must pick distinct, defensible positions (innovation, service, or cost) rather than attempting broad-based competition across every segment.
Recent market signals and what they imply
- Product launches of next-generation aliphatic hardeners and low-VOC grades underscore a product race in performance waterborne systems — indicating R&D and certification as short-term gating factors for premium segments.
- Distribution partnerships and catalog upgrades reflect two complementary routes to market expansion: (a) broadened channel reach to convert regional demand, and (b) higher-grade product introductions to capture value in stricter regulatory regimes.
- Feedstock and input-cost volatility in late 2025 highlighted the commercial risk of short-term purchasing strategies. Companies with secured feedstock or integrated value chains demonstrated resilience in margin retention.
- Policy instruments like REACH updates and carbon border mechanisms are already influencing sourcing and contractual design; carbon and compliance costs should be embedded into 2026 price models rather than treated as contingency.
Immediate, prioritized actions for 2026 executives
- Lock selective long-term feedstock arrangements: Prioritize hedges or supply agreements for the grades that underpin your growth plan, with indexation and force majeure clauses aligned to operational tolerance.
- Defend or build a specialty spine: Invest 12–24 months of targeted R&D and certifications for low-VOC, solvent-free grades if you aim to capture premium transport- and industrial-coatings demand.
- Reassess distributor networks: Use targeted partnerships to accelerate entry into geographies where regulatory complexity favors local support or where logistics increase time-to-customer.
- Embed regulatory and carbon scenarios into pricing: Reprice offerings with transparent compliance surcharges and develop client-facing narratives that justify modest upcharges amid rising compliance costs.
- Prioritize M&A targets by capability, not simply scale: Look for bolt-ons that add formulation know-how, certificate-to-market speed, or access to strategic end-use channels.
Conclusion — the strategic payoff of the study
For 2026, the Aliphatic Isocyanates Market is not a pure volume story but a value-shift story: growth will come from both higher baseline demand and migration into performance, regulatory-compliant chemistries. Our study gives you the market sizing, competitor intelligence, regulatory timelines, and tactical playbooks to convert that macro trajectory into executable decisions — whether you are defending share, scaling a specialty portfolio, or screening acquisition targets.
To access the full segmentation tables, supplier scorecards, price-by-grade sensitivity models, and the 18-month implementation roadmap, please consult the complete PW Consulting Aliphatic Isocyanates Market report. The granular data and transaction-ready appendices in that deliverable are designed to support board-level capital allocation and commercial negotiations in 2026.
For detailed analysis of this topic, please visit the official page: Aliphatic Isocyanates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Interlinings & Linings Market to hit USD 4,491M by 2032 at 4.5% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Interlinings & Linings Market — Strategic Outlook for 2026 Decisions
Executive snapshot
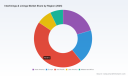
As companies plan their 2026 strategies, the interlinings & linings sector presents a textbook case of steady structural demand coupled with elevated input-price volatility and increasing sustainability pressure. PW Consulting’s latest Interlinings & Linings Market study uses 2025 as the base year (historical window 2020–2025, forecast horizon 2026–2032) and models a compound annual growth rate (CAGR) of 4.5% across the forecast period. Under our central scenario the overall market grows from a 2025 size of roughly USD 3.3 billion to approximately USD 4.49 billion by 2032, reflecting durability in apparel production, selective growth in technical and performance applications, and a gradual premium for sustainably manufactured content.
Interlinings & Linings Market
This report is intentionally framed as a decision tool for senior leaders: it goes beyond descriptive statistics to produce a set of operational playbooks, competitive scorecards, and actionable scenario models that translate market trajectories into boardroom priorities for 2026. To respect the "trailer" premise of this brief, detailed sub‑segment volume and revenue breakdowns are withheld here; the full dataset and proprietary segment matrices are available through the report portal.
Interlinings & Linings Market
Why 2026 is a pivot year
- Input volatility is no longer episodic. Polyester DTY costs and PTA-linked feedstocks have resumed upward momentum in early 2026, compressing gross margins for commodity-focused producers and increasing the relative attractiveness of recycled-polyester and bio‑based formulations.
- Sustainability is migrating from marketing to procurement. Certifications such as OEKO‑TEX remain the baseline; recycled-polyester content and biodegradable adhesive technologies are rapidly moving from niche to procurement conditionalities for tier-1 apparel buyers.
- Geopolitical supply-chain rebalancing favors regional capacity. Nearshoring and localized apparel production are prompting strategic investments into local interlining capacity—an early-mover advantage for players who can match localized quality with cost discipline.
- Moderate market concentration widens strategic options. The top three to five players capture a majority share of global revenues, creating both consolidation opportunities for roll-up strategies and white-space for specialist innovators focusing on premium or sustainability‑led niches.
What this study delivers (practical, transaction-ready content)
- Methodology and base-case model: transparent forecasts (2026–2032), sensitivity levers and scenario-built outputs you can re-run with bespoke assumptions.
- Demand driver diagnostics: apparel segment elasticities, technical textile use-cases, and a prioritized matrix of end-markets by strategic attractiveness (margin potential, growth, procurement stickiness).
- Supply chain maps: global capacity footprints, logistics choke-point analysis, and a supplier risk heatmap down to tier‑2 polymer inputs.
- Pricing & margin playbook: historical price pass-through benchmarks, raw‑material hedging recommendations, and price-improvement tactics by product family.
- Competitive benchmarking: scored profiles for incumbent and challenger firms, capacity change logs, capability gap analyses, and go/no-go M&A targets.
- Commercial playbooks: channel segmentation, OEM vs. branded-apparel strategies, specification negotiation templates and value-communication frameworks for sustainability premiums.
- Regulatory & standards matrix: certification pathways (OEKO‑TEX plus adjacent standards), customs/HS-code implications, and voluntary reporting best practices.
Competitive landscape — what to watch in 2026
The sector’s competitive set is a mix of global integrators, regionally focused specialists, and technical innovators. Our report profiles the leading players and recent moves that will shape competitive dynamics through 2026:
Interlinings & Linings Market
- Freudenberg Performance Materials (Germany) — a global reference point for scale and sustainability. The group’s push into high recycled‑content interlinings and advances in biodegradable adhesive systems position it to defend premium segments. Notably, Freudenberg expanded manufacturing capacity in Chennai in late 2025, signaling continued investment in localized Asian production capacity.
- Freudenberg & Vilene International Ltd (Hong Kong) — spans woven, knitted and non‑woven interlinings and continues to emphasize garment structure and quality. A 2025 ramp-up at its India site expanded local production capability and underscores the company’s regionalization strategy.
- Chargeurs Interlining (HK) and Chargeurs PCC (France) — these related entities combine global brand assets and technical product lines. Chargeurs PCC’s mid‑2025 executive appointments indicate a governance refresh to accelerate global scale and operational coordination across EMEA and Asia.
- Wendler Interlining H.K. Limited — a specialist with strength in shirt interlinings (woven/knit/non‑woven options), demonstrating how focused product differentiation can sustain margins in crowded markets.
Market concentration metrics in our model show that the top-three players capture a material share of the market, with the top-five expanding that lead. This structure creates both defensive headwinds for mid-sized players and acquisition windows for private equity and strategic buyers seeking scale or complementary capabilities.
Market dynamics and near-term risks
- Raw-material inflation: Polyester‑chain costs and PTA feedstock volatility have re-emerged as near-term margin pressures. Manufacturers without active hedging or alternative-fiber strategies will face compressed gross margins in 2026.
- Certification and procurement risk: OEKO‑TEX remains the default compliance threshold for polyester interlinings; buyers are increasingly requiring documented recycled content and validated life‑cycle claims.
- Trade and tariff stability: Interlinings are indexed under HS Code 590390 and, in the current window, have not experienced material tariff shocks. That said, regional trade policy shifts could alter the cost calculus for cross-border sourcing.
- Technology & product risk: Adhesive chemistry (fusible vs. sewn-in) and the scalability of biodegradable adhesives are differentiators. Firms that secure IP or scale production of high‑performance, low‑environmental-impact solutions will capture a premium.
Actionable playbook for 2026 (prioritized by time horizon)
- 0–6 months — Defensive liquidity & procurement:
- Implement a raw‑material sensitivity dashboard tied to polyester and PTA indices; establish hedging triggers and dual-sourcing clauses for critical inputs.
- Audit supplier OEKO‑TEX compliance across strategic SKUs and close any gaps in documentation to prevent procurement delisting.
- 6–18 months — Build commercial differentiation:
- Launch a sustainable‑content tier with validated third‑party claims (recycled content, lower-carbon adhesives) targeted at lead apparel accounts willing to pay a premium.
- Evaluate small-scale regional production hubs or toll manufacturing agreements to reduce landed costs and lead times for key customers.
- 18–36 months — Scale & consolidation:
- Pursue bolt‑on acquisitions focused on specialty adhesive chemistries or recycling feedstock capabilities to secure technology differentiation.
- Invest in digital specification tools that make it easier for OEMs to swap to your interlinings and capture stickiness via BOM integration.
Decision triggers we monitor
- Sustained polyester/PTA price step‑ups beyond seasonality — accelerates vertical integration and hedging strategies.
- Large apparel customers writing recycled‑content requirements into RFQs — triggers reallocation of R&D and capital to recycled-product lines.
- Regional capacity announcements by peers (new lines, expansions) — prompts re-evaluation of nearshoring vs. centralized sourcing in your supply model.
How to use this intelligence
Executives and strategic planning teams should use our study as a playbook to convert macro forecasts into executable actions. The full report contains the granular segment breakdowns, regional demand matrices, product-level margin analytics, and company scorecards necessary for M&A diligence, RFP design, and commercial negotiation. This brief showcases the framing and strategic lines of attack; the complete dataset and operational modules are provided in the report to convert insights into measurable outcomes.
Next steps
- For procurement leaders: request the raw-material sensitivity model and supplier heatmap to stress-test 2026 budgets.
- For business development leaders: review the competitive scorecards and recommended partner shortlist to prioritize outreach.
- For C‑suite: schedule a one‑hour briefing to walk through scenario outcomes and to align capital allocation with the priority plays above.
PW Consulting’s Interlinings & Linings Market report provides the empirical base, competitive intelligence, and execution checklists needed to make high‑confidence decisions in 2026. For the full sub‑segment reporting, interactive forecast model, and company scorecards cited above, please access the report portal where the complete analytical package is available.
For detailed analysis of this topic, please visit the official page: Interlinings & Linings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microcatheter Market to Reach USD 2,829M by 2032 at 7.1% CAGR | PW Consulting
By pmarketresearch, 2026-07-13
Microcatheter Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a concise, intelligence-led preview of our full Microcatheter Market study. This briefing distills the macro trends, competitive dynamics, and near-term inflection points that will matter most to corporate leaders planning budgets, M&A, product roadmaps, and go-to-market tactics in 2026. The full research package contains the granular models and proprietary segmentation that underpin these conclusions; this preview intentionally omits certain proprietary splits to preserve the value of the complete deliverable.
Microcatheter Market
Market snapshot: scale, trajectory, and concentration
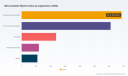
Using 2025 as the report base year, our market-sizing exercise places the global microcatheter market at approximately USD 1,763 million in 2025. Under the baseline scenario — which reflects conservative adoption curves for steerable and aspiration devices, continued replacement demand, and gradual expansion of interventional procedures — we forecast a compound annual growth rate (CAGR) of 7.1% across the 2026–2032 horizon. By 2032 the market is projected to reach roughly USD 2,829 million.
Microcatheter Market
Two structural features are noteworthy for strategy: first, the market demonstrates healthy growth that outpaces many legacy interventional device categories, driven by procedural innovation and expanded indications. Second, the competitive structure is moderately consolidated — our concentration metrics show that the three largest players account for around 45% of revenues, and the top five about 55% — creating distinct opportunities for mid-sized challengers and disruptive entrants that can carve niche technical advantages or channel positions.
Microcatheter Market
Why this research matters for 2026 corporate decisions
- Capital allocation and R&D prioritisation: With a mid-single-digit to high-single-digit growth trajectory, microcatheters present an attractive adjacency for companies seeking scalable medtech investments. Decisions on whether to accelerate development of steerable platforms, invest in cost-effective aspiration systems, or pursue OEM extrusion capabilities should be informed by the demand curves and margin sensitivity that our full model quantifies.
- M&A and partnership timing: The market’s concentration and recent regulatory clearances make 2026 a pivotal year for consolidation plays and bolt-on acquisitions. Buyers will need precise valuations that reflect not only current revenue runs but also pipelines, FDA clearances, and supply-chain resilience — items we model in scenario-based valuations in the full report.
- Commercial strategy and reimbursement navigation: Clinic-level adoption is shaped by bundled payment systems and cath-lab economics. Our analysis links procedural reimbursement dynamics to adoption thresholds for higher-cost steerable and aspiration devices, offering guidance on pricing strategies, hospital contracting, and value-based messaging that C-suite teams must adopt in 2026.
Market dynamics shaping 2026
Several cross-cutting dynamics will disproportionately influence winners and losers in the coming 18–36 months.
- Technology substitution and differentiation: Innovations in steerable microcatheters and low-profile delivery systems are changing case selection and procedural efficiency. Regulatory clearances for smaller steerable devices are already enabling complex procedures that previously required more invasive approaches; this catalyses demand but also raises the bar for product differentiation.
- Supply chain and materials risk: Shortages of high-performance polymers, particularly PTFE, in 2024 forced some manufacturers to in-source extrusion capabilities and re-engineer bill-of-materials. These disruptions compressed margins for exposed players and accelerated vertical integration among those with scale. Our cost-sensitivity models quantify the impacts of continued supply constraints on gross margins and suggest hedging strategies.
- Regulatory and reimbursement environment: Recent 510(k) clearances for steerable microcatheters and growing evidence supporting aspiration systems in acute settings are shaping clinical pathways. Simultaneously, microcatheters are frequently reimbursed within bundled DRG payments for cath lab procedures, which creates an imperative for demonstrating total-case efficiency and outcomes to secure preferred positioning in hospital formularies.
Competitive landscape — who’s shaping the market and how
The market is populated by a mix of large diversified medtech firms, specialized interventional device companies, and niche OEM suppliers. Across product classes — delivery, aspiration, steerable, and supplemental components — firms are pursuing differentiated plays rooted in engineering, regulatory momentum, and commercial reach.
- Large established players: Companies with broad cardiovascular and neurovascular portfolios are leveraging installed sales forces and account relationships to extend microcatheter penetration into existing clinical pathways. Their strengths include multi-indication product lines, global regulatory footprints, and purchasing leverage. These incumbents are increasingly focusing on end-to-end procedural systems rather than point products.
- Specialists and disrupters: Smaller, highly focused firms are unlocking value through step-change innovations — particularly steerability and low-profile access. By securing key regulatory milestones and demonstrating clinical utility in complex anatomies, these firms can rapidly scale specialty adoption despite limited breadth.
- OEM and material specialists: Suppliers providing tight-tolerance extrusions and advanced polymer processing have become strategic bottlenecks. Firms that control extrusion and catheter-body technologies can command price premiums or secure supply contracts that function as quasi-barriers to entry for competitors.
Company snapshots: strategic postures and tactical moves
Below are high-level strategic characterisations of selected market participants, highlighting the capabilities and recent moves that matter for 2026 positioning.
- Asahi Intecc: A Japan-headquartered specialist with a long heritage in braided microcatheter technologies. Its portfolio strengths are in durable braided constructions and multi-indication applications; product launches in the U.S. indicate continued geographic expansion and channel investment.
- Bendit Technologies: An Israeli innovator whose recent regulatory success for a very small steerable device positions it as a technology leader in precise navigation. The firm’s clearance opens pathways into complex neurovascular and peripheral cases that demand enhanced control.
- Boston Scientific: A diversified global medtech player that leverages scale to bundle microcatheters into broader neurovascular and peripheral therapy platforms. Its focus is on system-level synergies and clinical evidence generation.
- Cook Medical: A U.S. player known for braided stainless-steel constructions and PTFE-liner systems; its product breadth makes it a reliable partner for procedural variability across cath labs.
- Merit Medical: An agile competitor that has achieved regulatory clearances for steerable platforms across peripheral and coronary spaces — a move that materially upgrades its addressable market and commercial cadence.
- MicroVention and Penumbra: Both have deep neurovascular franchises; their aspiration and delivery systems are strategically positioned for acute stroke and aneurysm workflows, where time and access constraints define device choice.
- Teleflex and Terumo: Global players with complementary portfolios; emphasis is on reliability and incremental innovation to serve high-volume vascular procedures.
- Vantis Vascular, Q'Apel Medical, MicroCathCo: Innovators and OEM specialists focusing on advanced delivery systems, niche neurovascular devices, and custom extrusion capabilities respectively — each plays an outsized role in technology diffusion despite limited absolute scale.
Recent notable events — including multiple 510(k) clearances for steerable platforms and targeted commercial launches of integrated delivery systems — have moved the market from incremental to accelerated adoption in select segments. These regulatory and product milestones both create upside potential and intensify competitive pressure to secure early clinical wins.
What the full PW Consulting report delivers
The comprehensive study provides a practitioner-ready intelligence set tailored for revenue, R&D, and M&A decision-makers. Key components include:
- Detailed market-sizing and forecast models (2020–2032) with scenario analyses and sensitivity tests to test pricing, adoption, and supply shocks.
- Segment-level demand drivers and attrition curves across product types, designs, applications, and regions (note: proprietary split tables and unit models are included only in the full report).
- Commercial and clinical adoption frameworks that link reimbursement, hospital economics, and procedural throughput to device uptake thresholds.
- Vendor benchmarking with strategic heatmaps, capability matrices, and M&A probability scoring for the leading and challenger firms.
- Supply-chain risk assessment including polymer sourcing, in-house extrusion trade-offs, and contingency playbooks.
- Practical go-to-market playbooks: pricing levers, key account penetration plans, and evidence-generation roadmaps tied to ROI thresholds for hospital purchasers.
Recommended executive actions for 2026
- Prioritise product investments that demonstrably reduce procedure time or expand case eligibility — these features overcome bundled-payment headwinds.
- Ensure supply-chain resilience by securing alternative polymer sources or selectively insourcing extrusion for critical SKUs.
- Target M&A opportunities that deliver immediate clinical credibility (e.g., cleared steerable platforms) and shorten time-to-revenue rather than exclusively chasing scale.
- Invest in pragmatic clinical evidence generation tied to cath-lab economics: studies that demonstrate case throughput improvement will unlock contracting wins under bundled payments.
- Use competitive concentration metrics to identify regions and channels where mid-size players can punch above their weight with technical differentiation and targeted KOL engagement.
Closing — why PW Consulting’s intelligence matters
Microcatheters sit at the intersection of device engineering, procedural economics, and supply-chain complexity. For 2026 planning cycles, executives need more than headline growth rates — they need scenario-tested models, supplier risk scores, and evidence-driven commercial plays. Our full Microcatheter Market study provides those deliverables, combining quantitative forecasts with tactical playbooks. This preview highlights the strategic imperatives and market contours; the complete report contains the detailed subsegment analytics and financial models required to execute confidently. Contact PW Consulting to access the full dataset, vendor scorecards, and tailored advisory sessions that will convert market insight into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Microcatheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tablet Stylus Pens Market Set to Grow at 5.25% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Tablet Stylus Pens Market — Strategic Outlook for 2026 Decision‑Makers
Executive preview
By 2025 the global Tablet Stylus Pens market had matured into a stable, innovation‑led category with measurable scale. Our base‑year sizing places the market at approximately USD 1,025.8 Million in 2025, and under a central case we project the market to grow at a compound annual growth rate (CAGR) of 5.25% through the 2026–2032 forecast window. These dynamics create a landscape where product differentiation, supply‑chain resilience, and ecosystem partnerships will determine winners and losers over the next 18–36 months.
Tablet Stylus Pens Market
This executive piece is designed as a strategic trailer for PW Consulting’s full Tablet Stylus Pens Market study: it reveals the macro direction, commercial implications and high‑value strategic questions you must be asking in 2026 — while reserving detailed segment and competitor share tables for the full report.
Tablet Stylus Pens Market
Why 2026 is a pivotal year
Two forces converge in 2026. First, incremental but consistent demand growth is elevating the market from niche accessory to core input for tablets used in education, creative work and enterprise productivity. Second, supply‑side friction — driven by material controls, export restrictions, and regionalized manufacturing — is increasing the strategic value of vendor selection and supply‑chain design.
Tablet Stylus Pens Market
For corporate strategists, product managers and corporate development teams, the implications are immediate: investments in product differentiation (pressure levels, tilt, latency), industrial partnerships (EMR licensing, sensor MEMS suppliers), and contingency sourcing will affect margin and time‑to‑market more than in prior years.
What the macro numbers tell us
- The market has shown steady expansion from 2020 through 2025, reaching an estimated USD 1,025.8 Million in our base year.
- With a forecast CAGR of 5.25% across 2026–2032, the category exhibits predictable growth that supports medium‑term product and commercial investment, but not runaway scale that obviates the need for margin discipline and channel focus.
- Market concentration is moderate: the top three firms account for a meaningful but non‑dominant share (CR3 ~36.5%), while the top five push closer to half the market (CR5 ~48.2%). This profile rewards differentiated product strategy and tactical consolidation opportunities for mid‑sized players seeking scale.
Key industry dynamics shaping choices in 2026
- Materials & component risk: Conductive plastics, ITO touch films, precision stainless housings and lithium cells remain core upstream inputs. Firms that map supplier exposure and qualify alternate inputs will avoid single‑point failures.
- Regulatory & geopolitical headwinds: Recent export controls and measures affecting rare earths, battery components and related mining equipment have increased transaction complexity for suppliers with PRC exposure. Strategic sourcing and contractual protections against export restrictions will become part of procurement playbooks.
- Infrastructure & manufacturing specialization: EMR and high‑precision MEMS sensor fabrication remain concentrated in Asia‑Pacific hubs. Decisions to onshore, nearshore, or deepen relationships with specialized fabs will affect product roadmaps and unit economics.
- Shifting consumer preferences: The market continues to favor active, Bluetooth‑enabled models with palm rejection, tilt sensitivity and low latency. This behavioral move raises the technical bar for commoditized styluses and enlarges the opportunity for premium, software‑integrated offerings.
Report contents — what you will get from the full PW Consulting study
Our full report converts the macro narrative into implementable actions. Highlights include:
- Methodology & validated market sizing: transparent assumptions, data sources and bottom‑up reconciliation for 2020–2025 historicals and 2026–2032 forecasts.
- Scenario planning: three realistic demand and supply scenarios with trigger indicators and probabilistic outcomes for revenue, margin and inventory stress.
- Supply‑chain heat map: tiered supplier lists for key inputs (MEMS pressure sensors, ITO films, batteries), strategic vulnerability scoring, and alternative sourcing playbooks.
- Product economics model: bill‑of‑materials templates, margin sensitivity to component price swings, and break‑even calculations for premium feature introductions (e.g., increased pressure levels, haptic feedback, wireless charging).
- Go‑to‑market playbooks: channel prioritization by use case (education, creative prosumer, enterprise), pricing ladders, and partner co‑sell frameworks to accelerate adoption.
- Competitive intelligence annex: deep profiles on incumbent and challenger suppliers, patent landscape summaries and tactical M&A candidate screening criteria (including achievable synergies and integration risks).
- Regulatory & trade impact matrix: country‑level policy scenarios and recommended contractual clauses and compliance steps for 2026 procurement.
Competitive landscape — who to watch and why
The market features a mix of platform incumbents, hardware specialists and China‑based device innovators. Each archetype presents different opportunities and risks for partners and acquirers:
- Wacom Co., Ltd. (Tokyo, Japan — https://www.wacom.com): A heritage vendor in EMR styluses, Wacom continues to push ergonomics and artist‑grade controls; recent product activity (notably the Art Pen 2) signals ongoing investment in professional‑grade differentiation and partnerships with device OEMs.
- Apple Inc. (Cupertino, United States — https://www.apple.com): Apple’s ecosystem‑locked Pencil variants reinforce the power of closed ecosystems. For competitors and partners, Apple’s emphasis on integration and low‑latency UX is the standard to match or circumvent via companion apps and cross‑platform compatibility.
- Samsung Electronics (Suwon, South Korea — https://www.samsung.com): The S Pen’s OEM tie‑in strategy underlines the value of pre‑bundled accessory experiences. Samsung’s adoption of third‑party pen technologies (via selective licensing) is an indicator of potential co‑development opportunities.
- Microsoft Corporation (Redmond, United States — https://www.microsoft.com): Microsoft continues to leverage stylus technology as part of a productivity suite narrative; its Surface Pen is optimized for enterprise workflows, making Microsoft an important partner for B2B channel plays.
- Logitech International S.A. (Lausanne, Switzerland — https://www.logitech.com): Logitech’s focus on education and mass market note‑taking styluses demonstrates the scale attainable through channel partnerships and price‑performance balance.
- Adonit Inc., XP‑Pen, Huion, Parblo (multiple HQs): These specialist vendors compete on price, technical feature sets (pressure levels, tilt, magnetic storage), and rapid product refreshes. Recent launches and chip upgrades show that technical differentiation remains the primary lever for market share gains among prosumer and creative segments.
Recent industry signals
- Product innovation is accelerating: new generations of styluses emphasize ergonomics (360° barrel rotation), higher pressure resolution, and integrated shortcut controls — features aimed squarely at creative professionals and hybrid workers.
- OEM partnerships matter: strategic technology transfers and adoption events between stylus specialists and major device OEMs continue to reshape competitive advantage.
- Supply constraints and regulatory measures are non‑trivial: export controls and rare‑earth policies have raised the cost of doing business for certain suppliers, making supplier mapping and contractual hedging indispensable.
Strategic implications and recommended actions for 2026
To convert market growth into sustainable share and profit, executives should prioritize three initiatives:
- Supply‑chain resilience program: implement a three‑tier supplier map for critical components, negotiate dual‑source agreements for MEMS and batteries, and adopt inventory options that balance working capital against disruption risk.
- Product & software differentiation: invest in sensor R&D and UX integration (latency, tilt, haptics) while developing cross‑platform software features (cloud strokes, palm‑rejection profiles) that reduce ecosystem lock‑in for end users and increase switching costs.
- Partnership and M&A playbook: target bolt‑on acquisitions that close technical gaps (sensor fabs, EMR licensing) or extend channel reach (education distributors, enterprise resellers), and structure deals with earn‑outs tied to supply resilience and performance KPIs.
Short checklist for C‑suite and business unit leaders
- By Q3 2026, complete supplier vulnerability stress tests and sign at least one alternate supplier for each critical BOM item.
- Within 12 months, validate one cross‑platform software feature that materially improves user retention and can be monetized via subscriptions or bundled offerings.
- Assess three M&A targets or strategic alliances that can advance product differentiation or channel scale; prioritize those with minimal regulatory exposure and clear integration paths.
Closing — what PW Consulting can do for you
The Tablet Stylus Pens market in 2026 is neither a rushing tide nor a flatline — it is a disciplined growth market where product excellence, supply‑chain design and ecosystem partnerships create durable advantage. Our full study equips executive teams with the granular data, scenario tools and tactical playbooks needed to act confidently. For commercial due diligence, M&A screening, or a tailored supplier resilience workshop, PW Consulting provides end‑to‑end advisory support that translates this macro outlook into quarterly roadmaps and measurable outcomes.
Access the complete Tablet Stylus Pens Market report to unlock detailed regional and application breakdowns, company market shares, price‑by‑feature elasticity matrices, and hands‑on operational checklists. These components are intentionally withheld from this preview to preserve the practical value of the full analysis — and to give your team a definitive strategic blueprint for 2026.
For detailed analysis of this topic, please visit the official page: Tablet Stylus Pens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gears Market 2026: Strategic Primer for Decision-Makers
As senior strategy advisors at PW Consulting, we present a focused, practice-ready introduction to our new Gears Market research. This briefing frames the commercial realities that will shape executive choices in 2026 — from capex allocations and M&A screening to product roadmaps and supplier strategies. It highlights the market’s macro trajectory, competitive dynamics, supply-side shocks and the operational levers that matter most, while deliberately preserving the granular segmentation tables and model outputs for the full report.
Gears Market
Why this market matters in 2026
Gears remain a foundational industrial component across automotive, industrial machinery, construction, oilfield and robotics sectors. Our analysis — using 2025 as the base year and with historical coverage from 2020–2025 — shows a resilient market trajectory. After recovering steadily through the first half of the decade, the overall market expands further in our forecast window (2026–2032) at a compound annual growth rate (CAGR) of 5.77%.
Gears Market
To put this trajectory in operational terms: the market’s scale at the close of the historical period reflects multi-hundred‑million‑USD annual revenues, and the forecast path projects sustained mid-single-digit expansion into 2032. That profile creates two clear strategic imperatives for 2026: (1) optimize for steady, profitable growth rather than short-lived share grabs; and (2) embed resilience against commodity and labor shocks into product and supply strategies.
Gears Market
Market structure and concentration
The gears market is characterized by diverse specialization and moderate fragmentation. The top-three and top-five firm concentration metrics indicate that leadership pockets exist, but no single incumbent dominates the ecosystem — a fact that keeps options open for targeted consolidation, selective partnerships and niche premium plays. Specifically, concentration measures suggest modest aggregation among leading global players, signaling opportunities for bolt-on acquisitions and regional roll-ups by disciplined buyers.
Competitive landscape: who to watch and why
-
Philadelphia Gear (King of Prussia, PA) — Renowned for precision marine and industrial gears, and high-performance reduction systems. Their role supplying complex naval drives positions them as a preferred partner where engineering pedigree and certification matter.
-
IMS Gear GmbH (Germany) — Specializes in high‑precision metal and plastic gears with noise‑reduction technology, a growing premium attribute for EV drivetrains and robotics.
-
Brelie Gear (Waukesha, WI) — Strong in precision industrial power-transmission components; attractive to buyers seeking short lead times and aftermarket services.
-
Cone Drive (Traverse City, MI) — Known for high-torque right-angle worm and cycloidal drives. Their product and application focus makes them a natural ally for OEMs needing compact, high-torque solutions.
-
KHK Gears (Japan) — A large stock-gear supplier; their catalog strategy supports high-volume production and aftermarket replacement markets.
-
Nabtesco Precision Europe — A key player for robotics and automation, offering precision gearboxes and cycloidal gears aligned with industry 4.0 adoption.
-
Gear Motions , GKN PLC , Bharat Gears , Robert Bosch , American Axle & Manufacturing , Curtiss‑Wright — Each brings distinct strengths from custom precision manufacturing and automotive driveline systems to defense‑grade gear assemblies.
For corporate strategists, the practical takeaway is to map competitors not only by product but by route-to-market, certification footprint, and aftermarket services. These attributes determine whether a competitor is a direct threat, a potential JV partner, or an M&A target for capability infusion.
Recent industry signals and operational implications
-
Trade associations and consolidation: Industry institutions are realigning — exemplified by the unification of major associations into a consolidated trade body. That consolidation accelerates standards harmonization and amplifies advocacy on tariffs, procurement standards and workforce development.
-
Standards & certification: Recognition of contributions to high-speed helical gear specifications underscores the ongoing importance of technical standards. Companies with proactive standards engagement secure a competitive advantage in high-spec applications.
-
Product and trade activity: Recent trade show participation and product-line expansions by key suppliers signal continued demand for tailored motor‑gear integrations in robotics and automated equipment.
-
Raw material pressure: Steel pricing volatility — amplified by tariffs and policy shifts — remains the single largest near-term cost risk. The shock to blanks, cutting tools and related inputs requires procurement redesigns: multi-sourcing, hedging, re-specification to lower-cost alloys where feasible, and a reassessment of passing vs. absorbing cost in contracts.
-
Labor dynamics: A recent slowdown in hiring in the gear and bearing manufacturing workforce signals potential capacity constraints and wage pressure for 2026 — making automation, skills training and remote engineering support higher ROI than in prior planning cycles.
Technology, product and channel trends that will move the needle
-
Noiseless, high‑precision designs: Noise reduction and tolerancing will be growth multipliers, especially for EV drivetrains, robotics and aerospace niches. Firms investing early in NVH (noise, vibration, harshness) and high‑precision manufacturing capture premium margins.
-
Electrification and compact drivetrains: The shift to electrified powertrains alters gear design imperatives — higher RPMs, thermal considerations and mass reduction techniques — creating upstream opportunities for specialty materials and coatings.
-
Integrated systems and services: OEMs are increasingly procuring integrated gearbox + motor + control bundles. Suppliers that bundle mechanical expertise with electronics and software proficiency win longer, higher‑margin contracts.
-
Aftermarket and life-cycle services: Predictive maintenance, refurbishment programs and spare-parts subscriptions are effective margin enhancers and customer-retention mechanisms.
What the Gears Market report delivers (practical, deployable contents)
-
Market sizing and growth model (2020–2032) with scenario sensitivity to raw‑material and labor shocks. The public summary outlines the headline market scale and CAGR; the full report includes interactive model files and scenario toggles.
-
Competitive heatmaps that juxtapose product capability, certification, aftermarket reach, and geographic strength — enabling rapid go/no‑go decisions on regional expansion and acquisition targets.
-
Supplier risk matrix and procurement playbook: alternate sourcing strategies, contractual mechanisms for cost pass‑through, and recommended hedging tactics tailored to gear manufacturing supply chains.
-
Product roadmap templates aligned to electrification, NVH reduction, and integrated systems — including engineering, manufacturability and margin impact estimates.
-
M&A screening framework and a shortlist of potential bolt‑on profiles (anonymized), with EBITDA and integration sensitivity ranges — to support disciplined roll‑up strategies.
-
Operational playbooks: capex prioritization, automation investment cases, skilled-labor augmentation plans, and aftermarket monetization pathways.
-
Regulatory impact assessment and standards engagement roadmap, including practical steps to leverage industry-standard committees and to accelerate certification timelines for high‑speed helical and other critical product classes.
How executives should act in 2026
-
Re-prioritize procurement resilience: Implement dual-sourcing for critical inputs and adopt dynamic pricing clauses tied to steel indices. Short-term stockpiling should be evaluated only where working capital and lead-time considerations justify it.
-
Invest selectively in automation and precision capabilities: Use targeted automation to mitigate labor constraints and to improve tolerances that unlock premium segments.
-
Move up the value chain: Expand offerings toward integrated mechatronic assemblies and aftermarket lifecycle services to stabilize margin volatility.
-
Pursue bolt‑on consolidation: Given the market’s moderate concentration, there is strategic value in acquiring regional specialists to capture aftermarket pools and shorten lead times.
-
Engage in standards work: Active participation in standards development accelerates market access for high‑speed and precision gear solutions and reduces time-to-certification risk.
Next steps — where to get the full intelligence
This primer demonstrates the strategic contours and immediate actions that matter as executives set priorities for 2026. The complete Gears Market report from PW Consulting contains the full data tables, company profiles, interactive financial models and our confidential M&A target appendix. Those detailed segmentation tables, regional and application breakdowns, and modeled revenue projections are intentionally omitted here to preserve the report’s commercial value.
To secure the full report, model files and a tailored briefing with our industry leads, please visit the Gears Market page on the PW Consulting research portal or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Gears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Post-It & Sticky Notes Market to grow at 5.25% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Post-It & Sticky Notes Market — 2026 Strategic Primer
As PW Consulting’s lead industry analyst and senior strategy advisor, I present a focused, decision‑oriented overview of our latest Post‑It & Sticky Notes Market research. This primer is crafted to show the analytic depth and practical orientation of the full study while intentionally withholding the detailed segment tables and proprietary splits that corporate decision‑makers will find in the complete report. Consider this a high‑fidelity trailer: enough insight to inform immediate strategic questions and to clarify whether you need the full dataset and model for execution in 2026.
Post-It & Sticky Notes Market
Why this study matters for 2026 decision cycles
- Fast‑cycle portfolio planning — The stationery category is often seen as low‑complexity, but dynamic shifts in channels, sustainability requirements, and premiumization mean product portfolios must be re‑prioritized more frequently. Our study delivers the temporal precision needed for brand and SKU rationalization decisions in 2026.
- Sourcing and cost resilience — Raw material and packaging innovations (and disruptions) are altering landed costs and lead times. Procurement teams need forward‑looking cost curves and scenario planning to lock in supplier strategies and hedges.
- M&A and JV screening — With a fragmented supplier landscape, private equity and corporates will use our concentration, margin and growth diagnostics to identify roll‑up targets, bolt‑on candidates or joint venture partners.
- Go‑to‑market optimization — Retail assortment planning, e‑commerce tactics, and institutional sales (office, education) require differentiated demand profiles, which the full study translates into practical channel playbooks for 2026 activation.
Market at a glance (macro view)
Over the 2020–2025 historical window, the global Post‑It & sticky notes market expanded steadily, reflecting resilient end‑use demand and muted product replacement cycles. The market value rose from roughly USD 123.45 Million in 2020 to USD 166.34 Million in the base year (2025). Looking ahead, our forecast for 2026–2032 projects a compound annual growth rate (CAGR) of approximately 5.25%, with the market moving toward an estimated USD 238.85 Million by 2032 under the base scenario.
Post-It & Sticky Notes Market
These headline figures capture a market that is neither hyper‑growth nor stagnating — instead, it is attractive for players who can execute on distribution scale, product variation, and cost efficiency while responding to sustainability and customization trends.
Post-It & Sticky Notes Market
Key demand drivers and strategic implications
- Hybrid work and office dynamics: The partial retraction and subsequent stabilization of centralized office demand has created a bifurcated market — sustained institutional purchases co‑exist with growth in premium home office and creative consumer segments. Companies should test differentiated SKUs and premium bundles targeted at remote professionals and creative users.
- Educational and institutional consumption: Schools and training organizations remain structurally important buyers. Tender optimization and bulk channel partnerships yield higher utilization rates and are a low‑risk path to volume stability.
- Premiumization and design-led differentiation: A segment of buyers is willing to pay for design, sustainability credentials, and added functionality (e.g., repositionable adhesives with better tack lifecycle). Product design teams should prioritize perceptible utility gains that justify modest price premiums.
- Sustainability and circular packaging: Material and packaging innovations change the cost‑benefit calculus. For example, UPM has demonstrated that paper‑based packaging solutions can reduce weight significantly — UPM reports its paper‑based packaging is up to 80% lighter than conventional cardboard packaging and can shorten time‑to‑market — a concrete example of how upstream innovation can lower logistics costs and emissions intensity. Integrating lightweight, recyclable packaging is fast becoming table stakes for B2B procurement.
- Customization and promotional demand: Corporate gifting, event merchandising, and seasonal promotional programs drive demand for bespoke shapes, prints and co‑branding — a profitable niche for flexible manufacturers and converters.
Supply‑side dynamics and competitive landscape
The Post‑It & sticky notes market is characterized by low top‑tier concentration and a broad field of regional and specialized producers. Our concentration metrics confirm a fragmented competitive environment (CR3 and CR5 indicators point to modest aggregate shares for the largest players), creating room for price competition, private label expansion, and niche premium plays.
- 3M Company — As the global trademark owner of the iconic Post‑It brand, 3M remains the category reference. Its manufacturing scale is a strategic advantage; for example, its Cynthiana, Kentucky operations produce on the order of tens of billions of individual notes annually. 3M’s strengths are brand equity, broad distribution, and consistent product innovation.
- UPM Adhesive Materials — UPM competes by combining product performance with sustainability and packaging innovation. Its product lines and paper‑based packaging are examples of upstream differentiation that shorten time‑to‑market and reduce transport burdens.
- Chinese manufacturers (Deli Group, M&G Stationery, Guangbo Group, Huiying Enterprise) — These players offer scale, cost competitiveness and rapid customization. They are pivotal in global private‑label supply chains and are expanding their global distribution footprints.
- Specialist and premium brands (Poppin, Exacompta) — These companies pursue design‑led and premium office segments where aesthetic differentiation and lifecycle quality command higher margins.
Strategically, incumbent brand owners must defend shelf space and margin with a two‑pronged strategy: (1) protect core branded SKUs through NPD (new adhesives, eco‑friendly substrates, packaging) and (2) exploit premium and promotional niches where private label and low‑cost imports have limited traction. Cost‑focused manufacturers should continue to optimize unit economics while investing selectively in quality and speed‑to‑market capabilities to win customization projects.
What the full report delivers (practical, actionable contents)
The full PW Consulting report is built as a toolkit for immediate action. Highlights include:
- Robust market sizing and forecasting model (2020–2032) with scenario toggles for macroeconomic shocks, raw material price shocks, and accelerated sustainability adoption.
- Channel and customer segmentation maps that translate demand into SKU rationalization rules for retail, e‑commerce, office procurement, and education procurement — presented as playbooks for assortment and pricing.
- Competitive profiles and positioning matrices for the leading manufacturers and brands, including capability heat maps (manufacturing scale, customization lead time, sustainability credentials, geographic reach).
- Supply chain and cost build‑ups with supplier scorecards — from pulp and paper inputs to adhesive chemistry and packaging — plus procurement levers and negotiation scenarios.
- Go‑to‑market modules: retail merchandising guidelines, e‑commerce conversion levers, institutional tender playbooks, and a private label launch checklist.
- Regulatory and sustainability compliance guide: actionable steps to align product materials and packaging with common procurement standards and retailer sustainability policies.
- M&A and investment playbook: valuation benchmarks, margin profiles, integration pitfalls, and a pipeline prioritization framework for strategic buyers and sponsors.
- Raw data delivery: downloadable tables and the forecast model (editable), plus a management slide deck that client teams can use in board and investor briefings.
Note: the report contains detailed regional, product‑type and application splits and time‑series tables that are intentionally not reproduced here; those detailed segment outputs are included in the full dataset for subscribers and clients.
Using this research to shape 2026 actions — recommended moves
- Short term (0–6 months): Lock in primary supplier contracts with clauses that account for packaging innovations and freight weight reductions; pilot a recyclable packaging SKU with one or two strategic retail partners.
- Medium term (6–18 months): Rebalance the SKU portfolio to grow premium and customization offerings while pruning low‑velocity SKUs. Use our assortment playbooks to test margin accretive bundles in e‑commerce and corporate gifting channels.
- Longer term (18+ months): Pursue bolt‑on acquisitions in complementary stationery categories or regions where scale is low but fragmentation is high. Use the M&A playbook and valuation benchmarks from the report to accelerate screening and diligence.
Final thoughts and how to access the complete analysis
The Post‑It & Sticky Notes market is deceptively strategic: unit values are small, but cumulative volumes, channel complexity, and sustainability pressures create meaningful upside for firms that execute on product differentiation, supply chain optimization, and channel segmentation. The headline growth trajectory — a mid‑single‑digit CAGR through 2032 — underwrites investment in product and packaging innovation, but success will hinge on rapid implementation and disciplined SKU management.
If your 2026 strategy includes portfolio rationalization, supplier restructuring, entry into premium or private label segments, or selective M&A, the full PW Consulting report provides the detailed, operational intelligence you need: granular segment tables, scenario‑driven forecasts, and executable playbooks. For access to the complete dataset, forecast model, and slide pack, please visit the report landing page or contact PW Consulting’s advisory desk. The detailed splits and proprietary worksheets are available only through the full report subscription or client engagement.
For detailed analysis of this topic, please visit the official page: Post-It & Sticky Notes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ceramic Substrate Market to Reach USD 13.7B by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-13
Ceramic Substrate Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
The ceramic substrate market is at an inflection point. After expanding from roughly USD 6.5 billion in 2020 to about USD 8.8 billion in 2025, the market is projected to surpass USD 13.7 billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.5% through the forecast window. This trajectory is underpinned by accelerating demand for high‑reliability thermal-management and high-frequency materials across automotive electrification, power electronics, and next‑generation telecom. At the same time, the market’s structure remains concentrated — the top three players account for roughly 60% of industry shipments, and the top five for about 75% — creating both entry barriers and strategic partnership opportunities for new entrants and adjacent incumbents.
Ceramic Substrate Market
Why this briefing matters for 2026
2026 is the first full planning year after significant capacity, regulatory and technology shocks registered in 2024–2025. Supply chain re‑shoring decisions, capital expenditure cycles for new ceramic fabs, and strategic product roadmaps (especially for aluminum nitride and multilayer ceramic technologies) are being finalized. This briefing is designed to help corporate leadership translate market momentum into executable choices — from raw‑material hedging to plant siting, from joint development agreements to M&A prioritization — without relying on historical intuition alone.
Ceramic Substrate Market
Market dynamics shaping near‑term strategy
- Demand concurrencies and product mix pressure — Power conversion needs in EVs, traction in telecom front‑ends as 5G densifies (and 6G R&D advances), and continued industrial electrification are simultaneously lifting demand for multiple ceramic substrate technologies. The result is overlapping capacity needs that change the timing and ROI profile of new production lines.
- Raw‑material exposure and input volatility — Sourcing high‑purity alumina and advanced nitride powders has become a strategic vulnerability. Price and availability swings materially influence cost structures, and procurement strategies that were sufficient in 2023–24 no longer provide acceptable risk buffers.
- Regulatory and carbon‑pricing pressure — Emerging carbon border mechanisms and tightening environmental standards are reshaping sourcing economics and supplier selection, particularly for European OEMs and suppliers who rely on imported feedstocks with embedded carbon.
- Consolidation and capacity plays — Recent announcements by several leading manufacturers to expand production — and selected joint ventures to accelerate material innovation — indicate that the coming 18–36 months will be decisive in establishing cost leadership and time‑to‑market advantages.
- Technology bifurcation — High‑thermal‑conductivity materials (e.g., AlN), high‑power/high‑reliability ceramics (e.g., SiN), and multilayer/HTCC/LTCC approaches each serve distinct technical needs. R&D direction and manufacturing choices now require closer alignment with end‑customer architecture decisions than in prior cycles.
Competitive landscape — who to watch and why
- Kyocera Corporation (Kyoto, Japan) — A leader in AlN and silicon nitride substrates with strong OEM relationships in automotive and power electronics. Recent capacity investments indicate a deliberate push to secure high‑value volumes tied to automotive Tier‑1 programs.
- CoorsTek Inc. (Golden, Colorado) — Known for engineered ceramics for power modules and high‑reliability sectors; positions well for customers seeking vertically integrated supply and customized materials engineering.
- CeramTec GmbH (Germany) — Specialist in precision substrates with strengthened automotive ties; its strategic partnerships for next‑generation SiN work demonstrate a co‑development approach attractive to OEMs.
- Murata Manufacturing (Nagoya, Japan) — Multilayer ceramic expertise combined with recent capacity expansion makes Murata a key supplier for radio‑frequency and automotive applications where component integration matters.
- Rogers Corporation (Norwalk, USA) — Focused on high‑reliability substrates for power electronics and aerospace; a go‑to when electromagnetic performance and thermal management converge.
- Regional and specialized players — Firms such as Maruwa, KOA, NEOTech, Heraeus, Remtec and CUMI round out the competitive map with product niches spanning LTCC/HTCC, thick‑film processes and regional supply advantages.
Collectively these vendors control much of the value chain from powder supply to finished substrate and are actively reshaping capacity footprints via expansions, partnerships and product launches. Notable 2024–2025 moves — new LTCC lines targeted at next‑generation RF, joint ventures to accelerate multilayer innovation, and multiple capacity expansions in Asia, Europe and North America — underscore a shift from opportunistic production to strategic capacity alignment with OEM roadmaps.
Ceramic Substrate Market
What PW Consulting’s full report delivers (practical, operational outputs)
- Multi‑layered forecasting model with transparent assumptions (base year 2025; historical series 2020–2025; forecast horizon to 2032). Model delivered in spreadsheet form so clients can run sensitivities against material prices, adoption curves and regional demand scenarios.
- Scenario and stress‑test suite: three supply‑shock scenarios, two regulatory pathways, and an accelerated‑technology adoption case to quantify timing and magnitude of revenue and margin outcomes.
- Supplier scorecards and a strategic heat map — covering technology capability, capacity flexibility, ESG exposure, geopolitical risk and commercial terms — to prioritize vendor consolidation or diversification strategies.
- CapEx playbook and site‑selection framework: build vs buy analyses, payback schedules, and a phased investment roadmap aligned to OEM product timelines.
- Procurement and sourcing templates: cost‑build models, hedging approaches for critical powders, and negotiation playbooks for long‑lead items and capacity reservations.
- M&A and partnership shortlist with valuation frameworks calibrated to ceramic substrate economics and synergies (technology, customer access, geographic coverage).
- Regulatory impact pathways and mitigation levers: compliance roadmaps for carbon border adjustments and anticipated environmental rules, plus recommended data‑collection templates to validate embedded carbon claims.
- Commercial go‑to‑market playbooks addressing customer segmentation (OEMs, Tier‑1s, contract manufacturers), pricing architecture and pilot‑to‑scale conversion strategies for novel substrate formulations.
How senior leaders should apply these insights in 2026
- CEOs and corporate strategy teams: Use the scenario suite to align capital allocation with high‑probability demand pathways. Prioritize investments that secure time‑to‑market advantages for applications with multi‑year design cycles (e.g., automotive power modules).
- Supply chain and procurement leaders: Rebuild sourcing strategies around supply resilience and carbon compliance. Consider multi‑sourcing critical powders and negotiating forward‑capacity contracts with tiered pricing tied to validated carbon intensity metrics.
- R&D and product leaders: Reassess material roadmaps in light of customer architecture shifts; accelerate co‑development where suppliers are investing in dedicated lines to avoid late‑cycle redesigns.
- Investors and corporate development teams: Focus M&A diligence on target firms that close capability gaps (materials, process control, regional footprint) and that materially improve time‑to‑volume for prioritized end markets.
- Plant and operations managers: Leverage the CapEx playbook to phase capacity expansions, ensuring ramp profiles and yield improvements are economically synchronized with forecasted demand waves.
Methodology, scope and what’s intentionally withheld
This briefing is drawn from a comprehensive PW Consulting study with a 2025 base year, a historical window covering 2020–2025 and a forecast period extending through 2032. Figures are presented in USD (report unit: Million). Market sizing and growth rates reflect blended demand across regions, types and applications; concentration metrics cited above (CR3 ~60%, CR5 ~75%) summarize competitive dynamics. The full report contains detailed regional and application level breakouts, product‑type splits, contractual terms, and supplier‑level shipment volumes. In keeping with this document’s role as a strategic teaser, those granular sub‑segment disclosures and proprietary supplier scorecards are intentionally withheld here to allow readers to verify assumptions against the complete dataset and interactive models provided in the full deliverable.
Final note — the strategic imperative for 2026
For companies operating in or adjacent to the ceramic substrate value chain, 2026 is not a year to wait and react. It is a year to translate the market’s steady growth (mid‑single digits CAGR) and pronounced concentration into proactive decisions: secure upstream inputs under new risk paradigms, fast‑track partnerships that reduce time‑to‑design‑win, and align capacity investments with the customers that will determine the next cycle of scale economics. PW Consulting’s full Ceramic Substrate Market report supplies the quantitative backbone and operational playbooks to make those decisions defensible and timely. Accessing the full study will provide the region‑ and application‑level intelligence, supplier metrics and scenario tools necessary to execute with confidence.
For detailed analysis of this topic, please visit the official page: Ceramic Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com