

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aliphatic Isocyanates Market to Grow at 8.6% CAGR to USD 138.9M by 2032

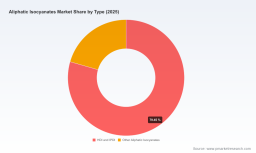
Aliphatic Isocyanates Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive primer on our Aliphatic Isocyanates Market study (base year 2025, historical window 2020–2025, forecast 2026–2032). This briefing is designed for executives who need immediate, actionable perspective heading into 2026: what the market trajectory implies for portfolio choices, supply-chain posture, regulatory readiness, and near-term M&A or partnering priorities. The piece demonstrates the analytical depth of our full study while intentionally withholding granular segment-level tables and proprietary splits — the precise, transaction-grade intelligence is available in the full report.
Aliphatic Isocyanates Market
Market trajectory at a glance
The global aliphatic isocyanates market has moved from a modest base in 2020 toward accelerating commercial relevance by 2025. Our firm-level reconciled series shows an increase from roughly USD 51.6 million in 2020 to USD 78.3 million in 2025. Under the scenarios embedded in this study, the market is expected to continue expanding through the forecast window, reaching an estimated USD 85.3 million in 2026 and projecting to approximately USD 138.9 million by 2032 — a compound annual growth rate of 8.6% for the forecast period.
Aliphatic Isocyanates Market
Those topline numbers mask meaningful structural shifts: demand is being reshaped by sustainability-driven formulation changes (low-VOC waterborne systems), by industrial coatings uptake in transport and infrastructure, and by higher-value specialty hardeners for two-component (2K) polyurethane coatings. For 2026 planning, this combination of steady baseline growth and product-value migration is the critical context for capital allocation and commercial strategy.
Aliphatic Isocyanates Market
Why this study matters for 2026 decisions
- Risk-weighted growth outlook: The 8.6% CAGR and year-on-year projections provide an actionable revenue map for product investment and capacity decisions. They enable realistic ramp plans for specialty grades versus commodity streams.
- Supply-chain sensitivity: Our modeling integrates feedstock volatility and regulatory cost drivers so procurement teams can stress-test contracts and hedging approaches before capital commitments.
- Regulatory and market-access playbook: The study translates recent regulatory events into compliance timelines and market access thresholds for coatings and transport sectors.
- Competitive positioning matrix: We provide a pragmatic view of where to compete — specialty performance, formulation systems, or price-led commodity plays — and the capability investments required for each path.
Dynamics reshaping the market (what to watch in 2026)
Four interlocking forces will determine winners and losers through 2026 and beyond:
- Raw-material and cost pressure: Feedstock swings materially affect margins in both specialty and commodity segments. Spot moves in late 2025 underscored how feedstock cost shocks can erode margin for unsecured supply positions and favor vertically integrated manufacturers.
- Regulatory tightening: Global regulatory regimes continue to converge on worker protection and emissions standards. European REACH updates and tightened training requirements for diisocyanates are operational realities; transatlantic compliance and California-level VOC/transport coatings standards are already shaping product roadmaps.
- Consolidation and concentration: The market remains concentrated: incumbents control a large majority of global capacity, which compresses competitive dynamics in core commodity grades while opening niches for differentiated specialty chemistries and service models.
- Asia-based capacity and pricing pressure: Competitive pressure from cost-advantaged producers in Asia is changing the dynamics of margin pools, particularly in commodity HDI/IPDI grades. At the same time, several Asian players are moving up the value chain with low-VOC, solvent-free offerings for transport and industrial coatings.
What the full report delivers (operational content)
- Robust market-sizing methodology and reconciled historical series (2020–2025) plus scenario-driven forecasts (2026–2032).
- Demand-driver analytics by end-use (coatings, adhesives, sealants and industrial applications) tied to real-world adoption curves and substitution elasticities.
- Supply-side mapping with plant-level capacity overlays, utilization scenarios, and a supplier concentration assessment that underpins competitive strategy.
- Cost-to-serve and feedstock sensitivity models that allow procurement and finance teams to stress-test margins under alternate price and carbon-cost trajectories.
- Regulatory impact matrix with compliance timelines, required product adjustments, and an operational checklist to de-risk market access.
- Commercial playbooks: go-to-market segmentation, distributor network design, and price-pack architecture for specialty versus commodity portfolios.
- Transaction intelligence: a screened list of M&A and JV targets, integration risk diagnostics, and expected payback ranges under conservative and aggressive scenarios.
- Action-oriented appendices, including supplier scorecards, negotiation playbooks for long-term offtake, and a prioritized 18-month implementation roadmap for market entry or defense.
Note: this primer omits the granular regional and application split tables and price-by-grade matrices that are part of the full deliverable; those core segmentation data are intentionally withheld here to protect the commercial value of the study and to drive direct engagement.
Competitive landscape — strategic readouts
The competitive field blends large integrated chemical groups, specialty isocyanate producers, and regional players scaling fast. Key strategic postures observed across the competitive set include:
- Global integrators (e.g., BASF, Covestro, Evonik): Broad product portfolios, strong R&D pipelines, and global distribution networks. Their advantage lies in formulation systems, combination offerings, and the ability to internalize some feedstock volatility through integration or long-term feedstock contracts. Expect continued emphasis on low-VOC and performance-grade lines targeted at premium coatings customers.
- Cost-advantaged regional champions (e.g., Wanhua): Rapid scale-up of competitive portfolios and expanded distribution agreements in Europe and neighboring markets. These players are increasingly pushing solvent-free, low-viscosity formulations suitable for modern transport coatings standards; their strategy mixes cost leadership with selective product innovation.
- Specialty-focused producers (e.g., Vencorex, niche Japanese producers): Focused on high-value hardeners and application-specific grades (2K waterborne polyurethanes, adhesives) where formulation expertise and certification speed are barriers to entry.
- Large chemical majors (e.g., Dow, Huntsman, Mitsui): Use broader chemical ecosystems to offer bundled solutions and to target industrial customers with lifecycle service propositions — a differentiator in large OEM accounts.
- Emerging & regional manufacturers: Some Chinese and Eastern European firms are closing quality gaps rapidly and pursue growth through local partnerships and aggressive pricing in commodity segments.
The market’s concentration dynamics — where the top few suppliers command a decisive share of capacity and sales — mean that challengers must pick distinct, defensible positions (innovation, service, or cost) rather than attempting broad-based competition across every segment.
Recent market signals and what they imply
- Product launches of next-generation aliphatic hardeners and low-VOC grades underscore a product race in performance waterborne systems — indicating R&D and certification as short-term gating factors for premium segments.
- Distribution partnerships and catalog upgrades reflect two complementary routes to market expansion: (a) broadened channel reach to convert regional demand, and (b) higher-grade product introductions to capture value in stricter regulatory regimes.
- Feedstock and input-cost volatility in late 2025 highlighted the commercial risk of short-term purchasing strategies. Companies with secured feedstock or integrated value chains demonstrated resilience in margin retention.
- Policy instruments like REACH updates and carbon border mechanisms are already influencing sourcing and contractual design; carbon and compliance costs should be embedded into 2026 price models rather than treated as contingency.
Immediate, prioritized actions for 2026 executives
- Lock selective long-term feedstock arrangements: Prioritize hedges or supply agreements for the grades that underpin your growth plan, with indexation and force majeure clauses aligned to operational tolerance.
- Defend or build a specialty spine: Invest 12–24 months of targeted R&D and certifications for low-VOC, solvent-free grades if you aim to capture premium transport- and industrial-coatings demand.
- Reassess distributor networks: Use targeted partnerships to accelerate entry into geographies where regulatory complexity favors local support or where logistics increase time-to-customer.
- Embed regulatory and carbon scenarios into pricing: Reprice offerings with transparent compliance surcharges and develop client-facing narratives that justify modest upcharges amid rising compliance costs.
- Prioritize M&A targets by capability, not simply scale: Look for bolt-ons that add formulation know-how, certificate-to-market speed, or access to strategic end-use channels.
Conclusion — the strategic payoff of the study
For 2026, the Aliphatic Isocyanates Market is not a pure volume story but a value-shift story: growth will come from both higher baseline demand and migration into performance, regulatory-compliant chemistries. Our study gives you the market sizing, competitor intelligence, regulatory timelines, and tactical playbooks to convert that macro trajectory into executable decisions — whether you are defending share, scaling a specialty portfolio, or screening acquisition targets.
To access the full segmentation tables, supplier scorecards, price-by-grade sensitivity models, and the 18-month implementation roadmap, please consult the complete PW Consulting Aliphatic Isocyanates Market report. The granular data and transaction-ready appendices in that deliverable are designed to support board-level capital allocation and commercial negotiations in 2026.
For detailed analysis of this topic, please visit the official page: Aliphatic Isocyanates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com