

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Interlinings & Linings Market to hit USD 4,491M by 2032 at 4.5% CAGR — PW Consulting

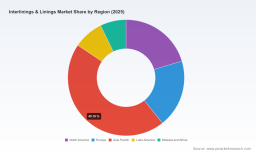
Interlinings & Linings Market — Strategic Outlook for 2026 Decisions
Executive snapshot
As companies plan their 2026 strategies, the interlinings & linings sector presents a textbook case of steady structural demand coupled with elevated input-price volatility and increasing sustainability pressure. PW Consulting’s latest Interlinings & Linings Market study uses 2025 as the base year (historical window 2020–2025, forecast horizon 2026–2032) and models a compound annual growth rate (CAGR) of 4.5% across the forecast period. Under our central scenario the overall market grows from a 2025 size of roughly USD 3.3 billion to approximately USD 4.49 billion by 2032, reflecting durability in apparel production, selective growth in technical and performance applications, and a gradual premium for sustainably manufactured content.
Interlinings & Linings Market
This report is intentionally framed as a decision tool for senior leaders: it goes beyond descriptive statistics to produce a set of operational playbooks, competitive scorecards, and actionable scenario models that translate market trajectories into boardroom priorities for 2026. To respect the "trailer" premise of this brief, detailed sub‑segment volume and revenue breakdowns are withheld here; the full dataset and proprietary segment matrices are available through the report portal.
Interlinings & Linings Market
Why 2026 is a pivot year
- Input volatility is no longer episodic. Polyester DTY costs and PTA-linked feedstocks have resumed upward momentum in early 2026, compressing gross margins for commodity-focused producers and increasing the relative attractiveness of recycled-polyester and bio‑based formulations.
- Sustainability is migrating from marketing to procurement. Certifications such as OEKO‑TEX remain the baseline; recycled-polyester content and biodegradable adhesive technologies are rapidly moving from niche to procurement conditionalities for tier-1 apparel buyers.
- Geopolitical supply-chain rebalancing favors regional capacity. Nearshoring and localized apparel production are prompting strategic investments into local interlining capacity—an early-mover advantage for players who can match localized quality with cost discipline.
- Moderate market concentration widens strategic options. The top three to five players capture a majority share of global revenues, creating both consolidation opportunities for roll-up strategies and white-space for specialist innovators focusing on premium or sustainability‑led niches.
What this study delivers (practical, transaction-ready content)
- Methodology and base-case model: transparent forecasts (2026–2032), sensitivity levers and scenario-built outputs you can re-run with bespoke assumptions.
- Demand driver diagnostics: apparel segment elasticities, technical textile use-cases, and a prioritized matrix of end-markets by strategic attractiveness (margin potential, growth, procurement stickiness).
- Supply chain maps: global capacity footprints, logistics choke-point analysis, and a supplier risk heatmap down to tier‑2 polymer inputs.
- Pricing & margin playbook: historical price pass-through benchmarks, raw‑material hedging recommendations, and price-improvement tactics by product family.
- Competitive benchmarking: scored profiles for incumbent and challenger firms, capacity change logs, capability gap analyses, and go/no-go M&A targets.
- Commercial playbooks: channel segmentation, OEM vs. branded-apparel strategies, specification negotiation templates and value-communication frameworks for sustainability premiums.
- Regulatory & standards matrix: certification pathways (OEKO‑TEX plus adjacent standards), customs/HS-code implications, and voluntary reporting best practices.
Competitive landscape — what to watch in 2026
The sector’s competitive set is a mix of global integrators, regionally focused specialists, and technical innovators. Our report profiles the leading players and recent moves that will shape competitive dynamics through 2026:
Interlinings & Linings Market
- Freudenberg Performance Materials (Germany) — a global reference point for scale and sustainability. The group’s push into high recycled‑content interlinings and advances in biodegradable adhesive systems position it to defend premium segments. Notably, Freudenberg expanded manufacturing capacity in Chennai in late 2025, signaling continued investment in localized Asian production capacity.
- Freudenberg & Vilene International Ltd (Hong Kong) — spans woven, knitted and non‑woven interlinings and continues to emphasize garment structure and quality. A 2025 ramp-up at its India site expanded local production capability and underscores the company’s regionalization strategy.
- Chargeurs Interlining (HK) and Chargeurs PCC (France) — these related entities combine global brand assets and technical product lines. Chargeurs PCC’s mid‑2025 executive appointments indicate a governance refresh to accelerate global scale and operational coordination across EMEA and Asia.
- Wendler Interlining H.K. Limited — a specialist with strength in shirt interlinings (woven/knit/non‑woven options), demonstrating how focused product differentiation can sustain margins in crowded markets.
Market concentration metrics in our model show that the top-three players capture a material share of the market, with the top-five expanding that lead. This structure creates both defensive headwinds for mid-sized players and acquisition windows for private equity and strategic buyers seeking scale or complementary capabilities.
Market dynamics and near-term risks
- Raw-material inflation: Polyester‑chain costs and PTA feedstock volatility have re-emerged as near-term margin pressures. Manufacturers without active hedging or alternative-fiber strategies will face compressed gross margins in 2026.
- Certification and procurement risk: OEKO‑TEX remains the default compliance threshold for polyester interlinings; buyers are increasingly requiring documented recycled content and validated life‑cycle claims.
- Trade and tariff stability: Interlinings are indexed under HS Code 590390 and, in the current window, have not experienced material tariff shocks. That said, regional trade policy shifts could alter the cost calculus for cross-border sourcing.
- Technology & product risk: Adhesive chemistry (fusible vs. sewn-in) and the scalability of biodegradable adhesives are differentiators. Firms that secure IP or scale production of high‑performance, low‑environmental-impact solutions will capture a premium.
Actionable playbook for 2026 (prioritized by time horizon)
- 0–6 months — Defensive liquidity & procurement:
- Implement a raw‑material sensitivity dashboard tied to polyester and PTA indices; establish hedging triggers and dual-sourcing clauses for critical inputs.
- Audit supplier OEKO‑TEX compliance across strategic SKUs and close any gaps in documentation to prevent procurement delisting.
- 6–18 months — Build commercial differentiation:
- Launch a sustainable‑content tier with validated third‑party claims (recycled content, lower-carbon adhesives) targeted at lead apparel accounts willing to pay a premium.
- Evaluate small-scale regional production hubs or toll manufacturing agreements to reduce landed costs and lead times for key customers.
- 18–36 months — Scale & consolidation:
- Pursue bolt‑on acquisitions focused on specialty adhesive chemistries or recycling feedstock capabilities to secure technology differentiation.
- Invest in digital specification tools that make it easier for OEMs to swap to your interlinings and capture stickiness via BOM integration.
Decision triggers we monitor
- Sustained polyester/PTA price step‑ups beyond seasonality — accelerates vertical integration and hedging strategies.
- Large apparel customers writing recycled‑content requirements into RFQs — triggers reallocation of R&D and capital to recycled-product lines.
- Regional capacity announcements by peers (new lines, expansions) — prompts re-evaluation of nearshoring vs. centralized sourcing in your supply model.
How to use this intelligence
Executives and strategic planning teams should use our study as a playbook to convert macro forecasts into executable actions. The full report contains the granular segment breakdowns, regional demand matrices, product-level margin analytics, and company scorecards necessary for M&A diligence, RFP design, and commercial negotiation. This brief showcases the framing and strategic lines of attack; the complete dataset and operational modules are provided in the report to convert insights into measurable outcomes.
Next steps
- For procurement leaders: request the raw-material sensitivity model and supplier heatmap to stress-test 2026 budgets.
- For business development leaders: review the competitive scorecards and recommended partner shortlist to prioritize outreach.
- For C‑suite: schedule a one‑hour briefing to walk through scenario outcomes and to align capital allocation with the priority plays above.
PW Consulting’s Interlinings & Linings Market report provides the empirical base, competitive intelligence, and execution checklists needed to make high‑confidence decisions in 2026. For the full sub‑segment reporting, interactive forecast model, and company scorecards cited above, please access the report portal where the complete analytical package is available.
For detailed analysis of this topic, please visit the official page: Interlinings & Linings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com