

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Atomizing Copper Powder Market to Hit $494M by 2032 at 5.8% CAGR

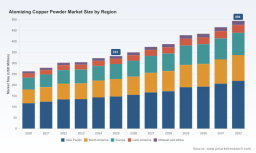
Atomizing Copper Powder Market: Strategic Imperatives for 2026 Decision‑Making
Executive Teaser
The atomizing copper powder market stands at a strategic inflection point as 2026 begins. PW Consulting’s new market study—anchored on a 2025 base year—projects the market to expand at a compound annual growth rate (CAGR) of 5.8% through 2032, with the addressable global market rising from a 2025 baseline to a materially larger value by 2032. Historical momentum from 2020–2025 underpins this trajectory, while today’s supply, regulatory and technology dynamics are re‑shaping near‑term choices for manufacturers, OEMs and investors. Market concentration remains low-to-moderate (CR3 ≈ 26.5%, CR5 ≈ 33.2%), signalling a fragmented supply landscape with differentiated technical and commercial niches—conditions that favour both targeted consolidation and nimble niche plays.
Atomizing Copper Powder Market
Why This Research Matters for 2026 Strategic Decisions
Executives and investment committees will confront high‑stakes choices in 2026: whether to greenfield or brownfield expand capacity, how to secure long‑term feedstock in a volatile raw‑material environment, which product grades to prioritize for additive manufacturing versus traditional powder metallurgy, and how to balance regulatory compliance with unit economics. This study is designed as a decision‑grade resource for these priorities. It translates market-level growth into scenario‑specific demand curves, risk matrices and executable playbooks so that procurement, R&D, operations and corporate development teams can move from hypothesis to investment-ready options within weeks—not months.
Atomizing Copper Powder Market
- Capital allocation: rapid screening of CAPEX alternatives with payback windows and sensitivity to metal price scenarios.
- Supply resilience: supplier scorecards and alternative sourcing pathways to mitigate feedstock volatility.
- Product strategy: priors for alloy and particle‑morphology development tied to high‑value end uses.
- Regulatory readiness: compliance roadmaps to limit the 2026‑era drag from environmental standards on powder handling and facility upgrades.
Primary Market Dynamics to Watch
Three converging dynamics will dominate boardroom conversations in 2026.
Atomizing Copper Powder Market
- Raw‑material volatility and pricing pressure. Industry production metrics show a substantial global throughput of atomized copper powder in the mid‑tens of thousands of metric tonnes annually and a market price environment that has oscillated materially through 2024–2025. The report models multiple pricing paths and the implications of each for margins across manufacturing routes (atomization vs electrolytic).
- Regulatory and compliance headwinds. Environmental regulation and stricter standards for metal powder handling are a real operational constraint: compliance-related constraints are already a primary contributor to capital project slowdowns and are explicitly modelled as a driver of retrofit timing and cost increases in the study.
- Technology and end‑market transition. Adoption of additive manufacturing (AM), higher‑performance powder metallurgy grades and advanced electrical/thermal applications is re‑shaping the demand mix. The research quantifies adoption pace and the premium attached to manufacturing‑ready powder specifications (particle size distribution, oxygen content, morphology) without disclosing proprietary segment-level values in this summary.
What the Report Contains — Practical, Executable Modules
The study is built as an operational toolkit for 2026 execution. Highlights include:
- Market sizing and forecast model (2020–2032) with scenario toggles—base, downside, and accelerated adoption scenarios—allowing users to test bespoke assumptions.
- Supply‑side mapping: detailed mill and route‑type coverage, manufacturing footprints, capacity estimates, and regional logistics overlays.
- Price and margin simulations: forward curves tied to metal cost drivers, energy inputs and regulatory compliance costs.
- Segment demand models by end application and grade (proprietary split tables included in the full report).
- Supplier scorecards and procurement playbooks: technical capability, quality certifications, commercial terms and suggested RFP templates.
- Facility upgrade and compliance playbook: CAPEX/OPEX models for emissions control, dust handling, and personnel safety tailored to common plant typologies.
- M&A and partnership roadmap: target archetypes, valuation heuristics and integration checklists designed for buyers and JV partners.
- Three strategic scenario playbooks and a 24‑month readiness checklist aligned to prioritized decisions (capacity, supplier contracts, regulatory upgrades).
Competitive Landscape — How Incumbents and Challengers Are Positioning
The sector is populated by specialists spanning legacy metal‑powder makers, advanced materials firms and regional aggregators. Our competitive analysis synthesizes public disclosures, site visits, and primary interviews to identify capabilities, strategic positioning and likely next moves for key players:
- Kymera International (Research Triangle Park, NC, USA; https://kymerainternational.com) — A technology‑led producer of both gas and water atomized copper powders. Strengths include AM and critical‑sector supply chains (medical, energy). Expect continued emphasis on qualification for high‑value applications and US‑based supply continuity.
- Pometon S.p.A. (Italy; https://www.pometon.com) — European specialist in water atomized powders and custom alloyed grades, with go‑to‑market focus on solar and EV supply chains. Their advantage is alloy customization and integration with downstream sintered part makers.
- Fukuda Metal Foil & Powder (Yamashina, Kyoto, Japan; https://www.fukuda-kyoto.co.jp/en) — Precision non‑ferrous powders, differentiated by tight quality control and certifications that appeal to electronics and medical segments.
- GRIPM Powder Materials (Beijing, China; https://en.gripm.com) — Integrated producer using atomization and electrolytic routes. Notably, a new facility in Thailand became operational in late 2024, expanding regional capacity and logistics options—an important strategic move for regional buyers seeking Nearshore alternatives.
- American Chemet Corporation (USA; https://www.americanchemet.com) — Concentrated on powder metallurgy grades for industrial customers; an attractive partner for sintered part suppliers.
- GGP Metal Powder AG (Germany; https://www.ggp-metalpowder.com) and Carl Schlenk AG (Germany; https://www.schlenk.de) — European players with a focus on AM and traditional powder metallurgy, respectively, where manufacturing quality and European regulatory compliance are differentiators.
- Mitsui Mining & Smelting (Tokyo, Japan; https://www.mitsui-kinzoku.com) and Makin Metal Powders (UK) (Rochdale; https://www.makin-metals.com) — Established suppliers with deep technical know‑how and selective exposure to specialty alloys and sintered component markets.
Collectively, the competitive field exhibits capability clustering—technical leadership in AM and custom alloys, regional cost advantage in Asia, and precision/quality strengths in Japan/Europe. These patterns create concrete pathways for buyers: qualifying a technical leader for high‑spec grades, contracting regional low‑cost suppliers for commodity grades, and layering inventory or offtake agreements to manage supply risk.
Strategic Implications and Recommended 2026 Actions
For executives planning 2026 moves, the report supports a short list of high‑impact actions:
- Implement a two‑track sourcing strategy: secure a core volume under medium‑term contracts with quality‑assured partners, and maintain a flexible secondary supplier pool to arbitrate spot volatility.
- Prioritise grade development linked to high‑value end users (e.g., AM‑ready powders), supported by co‑development agreements to shorten qualification timelines.
- Fast‑track compliance investments where regulatory risk threatens production continuity; use our retrofit cost templates to compare staged upgrades vs full replacements.
- Evaluate targeted M&A or capacity share deals to lift CR and access proprietary metallurgy capabilities—build the financial model on the range of scenarios the report provides.
- Convert market forecasts into procurement hedge triggers: deploy hedges or index‑linked contracts when modelled price thresholds are breached.
How PW Consulting’s Study Enables Execution — The Teaser
Our research is engineered to move organisations from insight to implementation. The full study includes download‑ready spreadsheets, supplier scorecards, RFP templates, CAPEX/OPEX calculators and a shortlist of actionable targets for strategic partnerships or acquisition. Importantly, while this article outlines the high‑value insights and the strategic frames, detailed segment tables (regional splits, type‑by‑application breakdowns, and contract‑level pricing scenarios) are intentionally withheld here to preserve the integrity of our proprietary models and to direct decision‑makers to the full intelligence package.
If you are evaluating capacity decisions, negotiating multiyear supply agreements, planning regulatory upgrades, or sizing an M&A play in 2026, PW Consulting’s Atomizing Copper Powder Market study provides the calibrated, decision‑grade inputs and playbooks to act with conviction. Access the full report to obtain the granular tables, scenario workbooks, and supplier contact mappings that underpin the strategies summarized above.
For detailed analysis of this topic, please visit the official page: Atomizing Copper Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com