

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ceramic Substrate Market to Reach USD 13.7B by 2032 at 6.5% CAGR

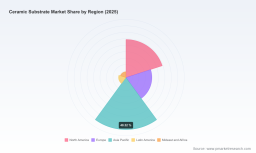
Ceramic Substrate Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
The ceramic substrate market is at an inflection point. After expanding from roughly USD 6.5 billion in 2020 to about USD 8.8 billion in 2025, the market is projected to surpass USD 13.7 billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.5% through the forecast window. This trajectory is underpinned by accelerating demand for high‑reliability thermal-management and high-frequency materials across automotive electrification, power electronics, and next‑generation telecom. At the same time, the market’s structure remains concentrated — the top three players account for roughly 60% of industry shipments, and the top five for about 75% — creating both entry barriers and strategic partnership opportunities for new entrants and adjacent incumbents.
Ceramic Substrate Market
Why this briefing matters for 2026
2026 is the first full planning year after significant capacity, regulatory and technology shocks registered in 2024–2025. Supply chain re‑shoring decisions, capital expenditure cycles for new ceramic fabs, and strategic product roadmaps (especially for aluminum nitride and multilayer ceramic technologies) are being finalized. This briefing is designed to help corporate leadership translate market momentum into executable choices — from raw‑material hedging to plant siting, from joint development agreements to M&A prioritization — without relying on historical intuition alone.
Ceramic Substrate Market
Market dynamics shaping near‑term strategy
- Demand concurrencies and product mix pressure — Power conversion needs in EVs, traction in telecom front‑ends as 5G densifies (and 6G R&D advances), and continued industrial electrification are simultaneously lifting demand for multiple ceramic substrate technologies. The result is overlapping capacity needs that change the timing and ROI profile of new production lines.
- Raw‑material exposure and input volatility — Sourcing high‑purity alumina and advanced nitride powders has become a strategic vulnerability. Price and availability swings materially influence cost structures, and procurement strategies that were sufficient in 2023–24 no longer provide acceptable risk buffers.
- Regulatory and carbon‑pricing pressure — Emerging carbon border mechanisms and tightening environmental standards are reshaping sourcing economics and supplier selection, particularly for European OEMs and suppliers who rely on imported feedstocks with embedded carbon.
- Consolidation and capacity plays — Recent announcements by several leading manufacturers to expand production — and selected joint ventures to accelerate material innovation — indicate that the coming 18–36 months will be decisive in establishing cost leadership and time‑to‑market advantages.
- Technology bifurcation — High‑thermal‑conductivity materials (e.g., AlN), high‑power/high‑reliability ceramics (e.g., SiN), and multilayer/HTCC/LTCC approaches each serve distinct technical needs. R&D direction and manufacturing choices now require closer alignment with end‑customer architecture decisions than in prior cycles.
Competitive landscape — who to watch and why
- Kyocera Corporation (Kyoto, Japan) — A leader in AlN and silicon nitride substrates with strong OEM relationships in automotive and power electronics. Recent capacity investments indicate a deliberate push to secure high‑value volumes tied to automotive Tier‑1 programs.
- CoorsTek Inc. (Golden, Colorado) — Known for engineered ceramics for power modules and high‑reliability sectors; positions well for customers seeking vertically integrated supply and customized materials engineering.
- CeramTec GmbH (Germany) — Specialist in precision substrates with strengthened automotive ties; its strategic partnerships for next‑generation SiN work demonstrate a co‑development approach attractive to OEMs.
- Murata Manufacturing (Nagoya, Japan) — Multilayer ceramic expertise combined with recent capacity expansion makes Murata a key supplier for radio‑frequency and automotive applications where component integration matters.
- Rogers Corporation (Norwalk, USA) — Focused on high‑reliability substrates for power electronics and aerospace; a go‑to when electromagnetic performance and thermal management converge.
- Regional and specialized players — Firms such as Maruwa, KOA, NEOTech, Heraeus, Remtec and CUMI round out the competitive map with product niches spanning LTCC/HTCC, thick‑film processes and regional supply advantages.
Collectively these vendors control much of the value chain from powder supply to finished substrate and are actively reshaping capacity footprints via expansions, partnerships and product launches. Notable 2024–2025 moves — new LTCC lines targeted at next‑generation RF, joint ventures to accelerate multilayer innovation, and multiple capacity expansions in Asia, Europe and North America — underscore a shift from opportunistic production to strategic capacity alignment with OEM roadmaps.
Ceramic Substrate Market
What PW Consulting’s full report delivers (practical, operational outputs)
- Multi‑layered forecasting model with transparent assumptions (base year 2025; historical series 2020–2025; forecast horizon to 2032). Model delivered in spreadsheet form so clients can run sensitivities against material prices, adoption curves and regional demand scenarios.
- Scenario and stress‑test suite: three supply‑shock scenarios, two regulatory pathways, and an accelerated‑technology adoption case to quantify timing and magnitude of revenue and margin outcomes.
- Supplier scorecards and a strategic heat map — covering technology capability, capacity flexibility, ESG exposure, geopolitical risk and commercial terms — to prioritize vendor consolidation or diversification strategies.
- CapEx playbook and site‑selection framework: build vs buy analyses, payback schedules, and a phased investment roadmap aligned to OEM product timelines.
- Procurement and sourcing templates: cost‑build models, hedging approaches for critical powders, and negotiation playbooks for long‑lead items and capacity reservations.
- M&A and partnership shortlist with valuation frameworks calibrated to ceramic substrate economics and synergies (technology, customer access, geographic coverage).
- Regulatory impact pathways and mitigation levers: compliance roadmaps for carbon border adjustments and anticipated environmental rules, plus recommended data‑collection templates to validate embedded carbon claims.
- Commercial go‑to‑market playbooks addressing customer segmentation (OEMs, Tier‑1s, contract manufacturers), pricing architecture and pilot‑to‑scale conversion strategies for novel substrate formulations.
How senior leaders should apply these insights in 2026
- CEOs and corporate strategy teams: Use the scenario suite to align capital allocation with high‑probability demand pathways. Prioritize investments that secure time‑to‑market advantages for applications with multi‑year design cycles (e.g., automotive power modules).
- Supply chain and procurement leaders: Rebuild sourcing strategies around supply resilience and carbon compliance. Consider multi‑sourcing critical powders and negotiating forward‑capacity contracts with tiered pricing tied to validated carbon intensity metrics.
- R&D and product leaders: Reassess material roadmaps in light of customer architecture shifts; accelerate co‑development where suppliers are investing in dedicated lines to avoid late‑cycle redesigns.
- Investors and corporate development teams: Focus M&A diligence on target firms that close capability gaps (materials, process control, regional footprint) and that materially improve time‑to‑volume for prioritized end markets.
- Plant and operations managers: Leverage the CapEx playbook to phase capacity expansions, ensuring ramp profiles and yield improvements are economically synchronized with forecasted demand waves.
Methodology, scope and what’s intentionally withheld
This briefing is drawn from a comprehensive PW Consulting study with a 2025 base year, a historical window covering 2020–2025 and a forecast period extending through 2032. Figures are presented in USD (report unit: Million). Market sizing and growth rates reflect blended demand across regions, types and applications; concentration metrics cited above (CR3 ~60%, CR5 ~75%) summarize competitive dynamics. The full report contains detailed regional and application level breakouts, product‑type splits, contractual terms, and supplier‑level shipment volumes. In keeping with this document’s role as a strategic teaser, those granular sub‑segment disclosures and proprietary supplier scorecards are intentionally withheld here to allow readers to verify assumptions against the complete dataset and interactive models provided in the full deliverable.
Final note — the strategic imperative for 2026
For companies operating in or adjacent to the ceramic substrate value chain, 2026 is not a year to wait and react. It is a year to translate the market’s steady growth (mid‑single digits CAGR) and pronounced concentration into proactive decisions: secure upstream inputs under new risk paradigms, fast‑track partnerships that reduce time‑to‑design‑win, and align capacity investments with the customers that will determine the next cycle of scale economics. PW Consulting’s full Ceramic Substrate Market report supplies the quantitative backbone and operational playbooks to make those decisions defensible and timely. Accessing the full study will provide the region‑ and application‑level intelligence, supplier metrics and scenario tools necessary to execute with confidence.
For detailed analysis of this topic, please visit the official page: Ceramic Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com