

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Microcatheter Market to Reach USD 2,829M by 2032 at 7.1% CAGR | PW Consulting

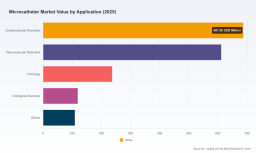
Microcatheter Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a concise, intelligence-led preview of our full Microcatheter Market study. This briefing distills the macro trends, competitive dynamics, and near-term inflection points that will matter most to corporate leaders planning budgets, M&A, product roadmaps, and go-to-market tactics in 2026. The full research package contains the granular models and proprietary segmentation that underpin these conclusions; this preview intentionally omits certain proprietary splits to preserve the value of the complete deliverable.
Microcatheter Market
Market snapshot: scale, trajectory, and concentration
Using 2025 as the report base year, our market-sizing exercise places the global microcatheter market at approximately USD 1,763 million in 2025. Under the baseline scenario — which reflects conservative adoption curves for steerable and aspiration devices, continued replacement demand, and gradual expansion of interventional procedures — we forecast a compound annual growth rate (CAGR) of 7.1% across the 2026–2032 horizon. By 2032 the market is projected to reach roughly USD 2,829 million.
Microcatheter Market
Two structural features are noteworthy for strategy: first, the market demonstrates healthy growth that outpaces many legacy interventional device categories, driven by procedural innovation and expanded indications. Second, the competitive structure is moderately consolidated — our concentration metrics show that the three largest players account for around 45% of revenues, and the top five about 55% — creating distinct opportunities for mid-sized challengers and disruptive entrants that can carve niche technical advantages or channel positions.
Microcatheter Market
Why this research matters for 2026 corporate decisions
- Capital allocation and R&D prioritisation: With a mid-single-digit to high-single-digit growth trajectory, microcatheters present an attractive adjacency for companies seeking scalable medtech investments. Decisions on whether to accelerate development of steerable platforms, invest in cost-effective aspiration systems, or pursue OEM extrusion capabilities should be informed by the demand curves and margin sensitivity that our full model quantifies.
- M&A and partnership timing: The market’s concentration and recent regulatory clearances make 2026 a pivotal year for consolidation plays and bolt-on acquisitions. Buyers will need precise valuations that reflect not only current revenue runs but also pipelines, FDA clearances, and supply-chain resilience — items we model in scenario-based valuations in the full report.
- Commercial strategy and reimbursement navigation: Clinic-level adoption is shaped by bundled payment systems and cath-lab economics. Our analysis links procedural reimbursement dynamics to adoption thresholds for higher-cost steerable and aspiration devices, offering guidance on pricing strategies, hospital contracting, and value-based messaging that C-suite teams must adopt in 2026.
Market dynamics shaping 2026
Several cross-cutting dynamics will disproportionately influence winners and losers in the coming 18–36 months.
- Technology substitution and differentiation: Innovations in steerable microcatheters and low-profile delivery systems are changing case selection and procedural efficiency. Regulatory clearances for smaller steerable devices are already enabling complex procedures that previously required more invasive approaches; this catalyses demand but also raises the bar for product differentiation.
- Supply chain and materials risk: Shortages of high-performance polymers, particularly PTFE, in 2024 forced some manufacturers to in-source extrusion capabilities and re-engineer bill-of-materials. These disruptions compressed margins for exposed players and accelerated vertical integration among those with scale. Our cost-sensitivity models quantify the impacts of continued supply constraints on gross margins and suggest hedging strategies.
- Regulatory and reimbursement environment: Recent 510(k) clearances for steerable microcatheters and growing evidence supporting aspiration systems in acute settings are shaping clinical pathways. Simultaneously, microcatheters are frequently reimbursed within bundled DRG payments for cath lab procedures, which creates an imperative for demonstrating total-case efficiency and outcomes to secure preferred positioning in hospital formularies.
Competitive landscape — who’s shaping the market and how
The market is populated by a mix of large diversified medtech firms, specialized interventional device companies, and niche OEM suppliers. Across product classes — delivery, aspiration, steerable, and supplemental components — firms are pursuing differentiated plays rooted in engineering, regulatory momentum, and commercial reach.
- Large established players: Companies with broad cardiovascular and neurovascular portfolios are leveraging installed sales forces and account relationships to extend microcatheter penetration into existing clinical pathways. Their strengths include multi-indication product lines, global regulatory footprints, and purchasing leverage. These incumbents are increasingly focusing on end-to-end procedural systems rather than point products.
- Specialists and disrupters: Smaller, highly focused firms are unlocking value through step-change innovations — particularly steerability and low-profile access. By securing key regulatory milestones and demonstrating clinical utility in complex anatomies, these firms can rapidly scale specialty adoption despite limited breadth.
- OEM and material specialists: Suppliers providing tight-tolerance extrusions and advanced polymer processing have become strategic bottlenecks. Firms that control extrusion and catheter-body technologies can command price premiums or secure supply contracts that function as quasi-barriers to entry for competitors.
Company snapshots: strategic postures and tactical moves
Below are high-level strategic characterisations of selected market participants, highlighting the capabilities and recent moves that matter for 2026 positioning.
- Asahi Intecc: A Japan-headquartered specialist with a long heritage in braided microcatheter technologies. Its portfolio strengths are in durable braided constructions and multi-indication applications; product launches in the U.S. indicate continued geographic expansion and channel investment.
- Bendit Technologies: An Israeli innovator whose recent regulatory success for a very small steerable device positions it as a technology leader in precise navigation. The firm’s clearance opens pathways into complex neurovascular and peripheral cases that demand enhanced control.
- Boston Scientific: A diversified global medtech player that leverages scale to bundle microcatheters into broader neurovascular and peripheral therapy platforms. Its focus is on system-level synergies and clinical evidence generation.
- Cook Medical: A U.S. player known for braided stainless-steel constructions and PTFE-liner systems; its product breadth makes it a reliable partner for procedural variability across cath labs.
- Merit Medical: An agile competitor that has achieved regulatory clearances for steerable platforms across peripheral and coronary spaces — a move that materially upgrades its addressable market and commercial cadence.
- MicroVention and Penumbra: Both have deep neurovascular franchises; their aspiration and delivery systems are strategically positioned for acute stroke and aneurysm workflows, where time and access constraints define device choice.
- Teleflex and Terumo: Global players with complementary portfolios; emphasis is on reliability and incremental innovation to serve high-volume vascular procedures.
- Vantis Vascular, Q'Apel Medical, MicroCathCo: Innovators and OEM specialists focusing on advanced delivery systems, niche neurovascular devices, and custom extrusion capabilities respectively — each plays an outsized role in technology diffusion despite limited absolute scale.
Recent notable events — including multiple 510(k) clearances for steerable platforms and targeted commercial launches of integrated delivery systems — have moved the market from incremental to accelerated adoption in select segments. These regulatory and product milestones both create upside potential and intensify competitive pressure to secure early clinical wins.
What the full PW Consulting report delivers
The comprehensive study provides a practitioner-ready intelligence set tailored for revenue, R&D, and M&A decision-makers. Key components include:
- Detailed market-sizing and forecast models (2020–2032) with scenario analyses and sensitivity tests to test pricing, adoption, and supply shocks.
- Segment-level demand drivers and attrition curves across product types, designs, applications, and regions (note: proprietary split tables and unit models are included only in the full report).
- Commercial and clinical adoption frameworks that link reimbursement, hospital economics, and procedural throughput to device uptake thresholds.
- Vendor benchmarking with strategic heatmaps, capability matrices, and M&A probability scoring for the leading and challenger firms.
- Supply-chain risk assessment including polymer sourcing, in-house extrusion trade-offs, and contingency playbooks.
- Practical go-to-market playbooks: pricing levers, key account penetration plans, and evidence-generation roadmaps tied to ROI thresholds for hospital purchasers.
Recommended executive actions for 2026
- Prioritise product investments that demonstrably reduce procedure time or expand case eligibility — these features overcome bundled-payment headwinds.
- Ensure supply-chain resilience by securing alternative polymer sources or selectively insourcing extrusion for critical SKUs.
- Target M&A opportunities that deliver immediate clinical credibility (e.g., cleared steerable platforms) and shorten time-to-revenue rather than exclusively chasing scale.
- Invest in pragmatic clinical evidence generation tied to cath-lab economics: studies that demonstrate case throughput improvement will unlock contracting wins under bundled payments.
- Use competitive concentration metrics to identify regions and channels where mid-size players can punch above their weight with technical differentiation and targeted KOL engagement.
Closing — why PW Consulting’s intelligence matters
Microcatheters sit at the intersection of device engineering, procedural economics, and supply-chain complexity. For 2026 planning cycles, executives need more than headline growth rates — they need scenario-tested models, supplier risk scores, and evidence-driven commercial plays. Our full Microcatheter Market study provides those deliverables, combining quantitative forecasts with tactical playbooks. This preview highlights the strategic imperatives and market contours; the complete report contains the detailed subsegment analytics and financial models required to execute confidently. Contact PW Consulting to access the full dataset, vendor scorecards, and tailored advisory sessions that will convert market insight into competitive advantage in 2026.
For detailed analysis of this topic, please visit the official page: Microcatheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com