

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gears Market Set to Grow at a 5.77% CAGR (2026–2032)

Gears Market 2026: Strategic Primer for Decision-Makers
As senior strategy advisors at PW Consulting, we present a focused, practice-ready introduction to our new Gears Market research. This briefing frames the commercial realities that will shape executive choices in 2026 — from capex allocations and M&A screening to product roadmaps and supplier strategies. It highlights the market’s macro trajectory, competitive dynamics, supply-side shocks and the operational levers that matter most, while deliberately preserving the granular segmentation tables and model outputs for the full report.
Gears Market
Why this market matters in 2026
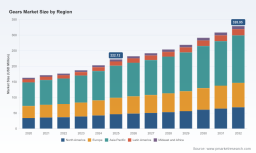
Gears remain a foundational industrial component across automotive, industrial machinery, construction, oilfield and robotics sectors. Our analysis — using 2025 as the base year and with historical coverage from 2020–2025 — shows a resilient market trajectory. After recovering steadily through the first half of the decade, the overall market expands further in our forecast window (2026–2032) at a compound annual growth rate (CAGR) of 5.77%.
Gears Market
To put this trajectory in operational terms: the market’s scale at the close of the historical period reflects multi-hundred‑million‑USD annual revenues, and the forecast path projects sustained mid-single-digit expansion into 2032. That profile creates two clear strategic imperatives for 2026: (1) optimize for steady, profitable growth rather than short-lived share grabs; and (2) embed resilience against commodity and labor shocks into product and supply strategies.
Gears Market
Market structure and concentration
The gears market is characterized by diverse specialization and moderate fragmentation. The top-three and top-five firm concentration metrics indicate that leadership pockets exist, but no single incumbent dominates the ecosystem — a fact that keeps options open for targeted consolidation, selective partnerships and niche premium plays. Specifically, concentration measures suggest modest aggregation among leading global players, signaling opportunities for bolt-on acquisitions and regional roll-ups by disciplined buyers.
Competitive landscape: who to watch and why
-
Philadelphia Gear (King of Prussia, PA) — Renowned for precision marine and industrial gears, and high-performance reduction systems. Their role supplying complex naval drives positions them as a preferred partner where engineering pedigree and certification matter.
-
IMS Gear GmbH (Germany) — Specializes in high‑precision metal and plastic gears with noise‑reduction technology, a growing premium attribute for EV drivetrains and robotics.
-
Brelie Gear (Waukesha, WI) — Strong in precision industrial power-transmission components; attractive to buyers seeking short lead times and aftermarket services.
-
Cone Drive (Traverse City, MI) — Known for high-torque right-angle worm and cycloidal drives. Their product and application focus makes them a natural ally for OEMs needing compact, high-torque solutions.
-
KHK Gears (Japan) — A large stock-gear supplier; their catalog strategy supports high-volume production and aftermarket replacement markets.
-
Nabtesco Precision Europe — A key player for robotics and automation, offering precision gearboxes and cycloidal gears aligned with industry 4.0 adoption.
-
Gear Motions , GKN PLC , Bharat Gears , Robert Bosch , American Axle & Manufacturing , Curtiss‑Wright — Each brings distinct strengths from custom precision manufacturing and automotive driveline systems to defense‑grade gear assemblies.
For corporate strategists, the practical takeaway is to map competitors not only by product but by route-to-market, certification footprint, and aftermarket services. These attributes determine whether a competitor is a direct threat, a potential JV partner, or an M&A target for capability infusion.
Recent industry signals and operational implications
-
Trade associations and consolidation: Industry institutions are realigning — exemplified by the unification of major associations into a consolidated trade body. That consolidation accelerates standards harmonization and amplifies advocacy on tariffs, procurement standards and workforce development.
-
Standards & certification: Recognition of contributions to high-speed helical gear specifications underscores the ongoing importance of technical standards. Companies with proactive standards engagement secure a competitive advantage in high-spec applications.
-
Product and trade activity: Recent trade show participation and product-line expansions by key suppliers signal continued demand for tailored motor‑gear integrations in robotics and automated equipment.
-
Raw material pressure: Steel pricing volatility — amplified by tariffs and policy shifts — remains the single largest near-term cost risk. The shock to blanks, cutting tools and related inputs requires procurement redesigns: multi-sourcing, hedging, re-specification to lower-cost alloys where feasible, and a reassessment of passing vs. absorbing cost in contracts.
-
Labor dynamics: A recent slowdown in hiring in the gear and bearing manufacturing workforce signals potential capacity constraints and wage pressure for 2026 — making automation, skills training and remote engineering support higher ROI than in prior planning cycles.
Technology, product and channel trends that will move the needle
-
Noiseless, high‑precision designs: Noise reduction and tolerancing will be growth multipliers, especially for EV drivetrains, robotics and aerospace niches. Firms investing early in NVH (noise, vibration, harshness) and high‑precision manufacturing capture premium margins.
-
Electrification and compact drivetrains: The shift to electrified powertrains alters gear design imperatives — higher RPMs, thermal considerations and mass reduction techniques — creating upstream opportunities for specialty materials and coatings.
-
Integrated systems and services: OEMs are increasingly procuring integrated gearbox + motor + control bundles. Suppliers that bundle mechanical expertise with electronics and software proficiency win longer, higher‑margin contracts.
-
Aftermarket and life-cycle services: Predictive maintenance, refurbishment programs and spare-parts subscriptions are effective margin enhancers and customer-retention mechanisms.
What the Gears Market report delivers (practical, deployable contents)
-
Market sizing and growth model (2020–2032) with scenario sensitivity to raw‑material and labor shocks. The public summary outlines the headline market scale and CAGR; the full report includes interactive model files and scenario toggles.
-
Competitive heatmaps that juxtapose product capability, certification, aftermarket reach, and geographic strength — enabling rapid go/no‑go decisions on regional expansion and acquisition targets.
-
Supplier risk matrix and procurement playbook: alternate sourcing strategies, contractual mechanisms for cost pass‑through, and recommended hedging tactics tailored to gear manufacturing supply chains.
-
Product roadmap templates aligned to electrification, NVH reduction, and integrated systems — including engineering, manufacturability and margin impact estimates.
-
M&A screening framework and a shortlist of potential bolt‑on profiles (anonymized), with EBITDA and integration sensitivity ranges — to support disciplined roll‑up strategies.
-
Operational playbooks: capex prioritization, automation investment cases, skilled-labor augmentation plans, and aftermarket monetization pathways.
-
Regulatory impact assessment and standards engagement roadmap, including practical steps to leverage industry-standard committees and to accelerate certification timelines for high‑speed helical and other critical product classes.
How executives should act in 2026
-
Re-prioritize procurement resilience: Implement dual-sourcing for critical inputs and adopt dynamic pricing clauses tied to steel indices. Short-term stockpiling should be evaluated only where working capital and lead-time considerations justify it.
-
Invest selectively in automation and precision capabilities: Use targeted automation to mitigate labor constraints and to improve tolerances that unlock premium segments.
-
Move up the value chain: Expand offerings toward integrated mechatronic assemblies and aftermarket lifecycle services to stabilize margin volatility.
-
Pursue bolt‑on consolidation: Given the market’s moderate concentration, there is strategic value in acquiring regional specialists to capture aftermarket pools and shorten lead times.
-
Engage in standards work: Active participation in standards development accelerates market access for high‑speed and precision gear solutions and reduces time-to-certification risk.
Next steps — where to get the full intelligence
This primer demonstrates the strategic contours and immediate actions that matter as executives set priorities for 2026. The complete Gears Market report from PW Consulting contains the full data tables, company profiles, interactive financial models and our confidential M&A target appendix. Those detailed segmentation tables, regional and application breakdowns, and modeled revenue projections are intentionally omitted here to preserve the report’s commercial value.
To secure the full report, model files and a tailored briefing with our industry leads, please visit the Gears Market page on the PW Consulting research portal or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Gears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com