

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Gas Humidity Sensors Market to Reach USD 2,431.33 Million by 2032, Growing at a 7.51% CAGR
By pmarketresearch, 2026-07-13
Gas Humidity Sensors Market 2026: Strategic Priorities and Tactical Playbook — PW Consulting Insight Brief
As leading firms prepare budgets and product roadmaps for 2026, PW Consulting’s latest Gas Humidity Sensors Market report delivers the high-resolution strategic intelligence required to translate market momentum into competitive advantage. Anchored on a 2025 base year and a six-year forecast horizon (2026–2032), the study quantifies an industry that we project to expand from approximately USD 1,465.5 Million in 2025 to roughly USD 2,431.3 Million by 2032, growing at a compound annual growth rate (CAGR) of 7.51%. This brief outlines the report’s strategic value for corporate decision-makers while preserving the segmentation-level granularity that can be unlocked through the full PW Consulting release.
Gas Humidity Sensors Market
Why 2026 is an Inflection Moment
Three converging forces make 2026 a pivotal planning year for sensor vendors, OEMs, system integrators, and investors. First, accelerating adoption of environmental sensing across automotive (notably LiDAR and cabin systems), industrial automation, HVAC modernization, and critical healthcare monitoring is expanding addressable demand. Second, a tighter supply-side environment — driven by semiconductor and specialty materials pressures — is raising lead times and elevating supplier risk as a core procurement consideration. Third, emerging functional-safety requirements and product certifications (for example, ASIL-class expectations in automotive subsystems) are redefining product roadmaps and qualification timelines. Collectively these dynamics turn 2026 from another annual update into a year for decisive portfolio and supply-chain moves.
Gas Humidity Sensors Market
What Our Report Delivers — Practical, Transaction-Ready Outputs
- Integrated market sizing and forecasting model (2020–2025 historical base, 2026–2032 projections) with scenario analytics that stress-test demand under alternate macro, regulatory and supply-chain regimes.
- Supplier and product benchmark suite that scores participants across accuracy, power consumption, miniaturization, automotive qualification, and cost-to-serve — designed for rapid vendor short-listing and design-win prioritization.
- Go-to-market playbooks tailored to OEMs, distribution partners, and regional integrators, including channel strategies, value-prop segmentation, and pricing tactics that reflect 2026 procurement realities.
- Supply-chain resilience toolkit: multi-sourcing maps, raw-material exposure heatmaps, lead-time sensitivity analyses, and contingency scenarios for tariff and geopolitical shocks.
- M&A and partnership screening framework that highlights acquisition targets, bolt-on technologies, and strategic partnerships aligned to scale in higher-growth subspaces within the broader market.
- Regulatory and standards matrix that correlates certification timelines (including functional-safety requirements) to time-to-revenue models for automotive and safety-critical applications.
Each deliverable is built to be operational: decision-ready models and slide decks can be repurposed directly into board briefs, investment memos, or product strategy sessions.
Gas Humidity Sensors Market
Competitive Landscape: Who Matters and Why
The gas humidity sensor market exhibits moderate concentration: the top three firms account for a meaningful share of the market and the top five approach near-majority control, underscoring room for consolidation and meaningful opportunities for differentiated entrants.
- Sensirion AG (Stäfa, Switzerland): A leader in high-precision digital humidity and flow sensing, Sensirion combines strong automotive and industrial design-wins with a technology roadmap that now includes ASIL-rated solutions. Its recent investor disclosures and product launches signal a deliberate push into safety-critical segments — a material strategic shift for incumbents and challengers alike.
- Honeywell International Inc. (Charlotte, NC): With a broad portfolio targeted at building and industrial automation, Honeywell’s Building Technologies segment remains a go-to supplier for HVAC and facility-level sensing. Its strength lies in channel relationships and systems integration rather than component-cost leadership.
- Texas Instruments (Dallas, TX): TI brings semiconductor-scale manufacturing, low-power digital sensor solutions, and strong embedded-systems partnerships to the market. Its product family is strategically positioned for industrial and consumer embedded applications where integration with analog/mixed-signal platforms matters.
- Bosch Sensortec (Reutlingen, Germany): The company leverages MEMS miniaturization and multi-parameter combo sensors to serve IoT, wearable and consumer markets — segments where size, power, and integration with environmental sensing suites are decisive.
- Amphenol Advanced Sensors , TE Connectivity , Vaisala , and E+E Elektronik : These players complement the competitive set with offerings that span harsh-environment robustness, aerospace/defense channels, meteorological-grade accuracy, and thin-film product differentiation. Their strengths are in vertical specialization, certification depth, and legacy customer relationships.
Recent industry developments further shape supplier calculus. Sensirion’s announcement of ASIL-rated humidity sensing and design wins with multiple leading LiDAR OEMs underscores automotive safety as a high-margin, high-barrier segment. Platform moves — like Infineon integrating humidity elements for indoor air quality analytics — and distribution agreements supporting aerospace and defense applications reflect both product convergence and channel evolution. For strategists, these signals indicate where premium pricing and long-term contracts are most attainable.
Supply Chain, Regulation and Materials: The New Risk Layer
The report highlights three factors that cannot be treated as peripheral risk items in 2026 planning:
- Raw-material and component constraints: empirical evidence shows lead-time inflation in related electronic sensing markets, materially increasing sourcing risk and working-capital requirements. Our models quantify the sensitivity of supplier lead times to rare-earth and specialty-material tightness and simulate inventory strategies to mitigate revenue disruption.
- Trade policies and tariffs: policy moves in 2025 introduced tariff volatility that reverberates across electronics and electrical supply chains. These events compress margin windows for import-dependent manufacturers and favor local manufacturing or near-shore strategies for critical subsystems.
- Product safety and certification: the uptake of ASIL-rated expectations in automotive and other safety-critical domains requires extended R&D and qualification cycles. Time-to-market delays are not only technical but contractual — affecting revenue recognition and partnership negotiations.
Strategic Playbook — Priorities for 2026 Decision Makers
We recommend four immediate strategic moves for companies with exposure to the gas humidity sensing value chain:
- Prioritize qualification pathways for safety-critical certifications where feasible. The margin uplift and stickiness of ASIL-compliant design wins justify front-loaded R&D and validation spend for firms targeting automotive and industrial safety markets.
- Diversify raw-material sources and operational footprints. Establishing near-shore capacity or dual-sourcing agreements for key components reduces tariff and lead-time exposure and preserves launching cadence for new modules.
- Re-evaluate channel economics and partnership models. Distribution agreements and franchise channels (notably where aerospace/defense demand exists) shift the economics of customer acquisition; re-balance direct vs. indirect routes aligned to lifetime value and support requirements.
- Use M&A and technology tie-ups to accelerate access to integrated sensing capabilities (e.g., MEMS-humidity integration) rather than attempting slow, high-risk organic development in areas outside core competencies.
How PW Consulting Builds Confidence — Methodology & Credibility
The full report synthesizes primary interviews with supplier and OEM executives, transaction and design-win tracking, and rigorous bottom-up demand modeling across the 2020–2025 historical period and 2026–2032 forecast window. Scenario analysis is embedded into the financial model to stress-test revenue and margin outcomes under alternative tariff, supply-chain, and adoption pathways. We combine proprietary shipment and design-win datasets with public disclosures and material-specific supply intelligence to deliver forecasts with both transparency and traceability.
Concluding Perspective
For executives updating 2026 plans, PW Consulting’s Gas Humidity Sensors Market report reframes the opportunity: growth is healthy and sustained, but monetization increasingly depends on managing certification timelines, supply-chain resilience, and targeted go-to-market execution. The market’s trajectory — from an estimated USD 1,465.5 Million in 2025 to USD 2,431.3 Million by 2032 at a 7.51% CAGR — validates continued investment, but how that investment is allocated will determine winners and laggards.
To access the full dataset, detailed segmentation, regional and application splits, supplier scorecards, and the downloadable forecasting model, please visit PW Consulting’s report page. The complete package contains the granular intelligence necessary to convert the market’s macro tailwinds into sustained commercial advantage.
For detailed analysis of this topic, please visit the official page: Gas Humidity Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Enzymes for Fuel Ethanol Market to Grow at a 6.3% CAGR Through 2032
By pmarketresearch, 2026-07-13
Enzymes For Fuel Ethanol Market — Strategic Outlook for 2026 Decision Makers
Executive summary
As regulatory signals, feedstock economics, and enzyme innovation converge, the enzymes-for-fuel-ethanol market is entering a period of predictable expansion and intensified supplier consolidation. PW Consulting’s latest market model projects continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.3%, with the market already valued in the low‑billion USD range by the 2025 base year and anticipated to exceed USD 2.1 billion by the end of the forecast horizon. For executives making capital allocation, procurement, and technology-partnership choices in 2026, the practical implications are clear: enzyme strategy is now a core competitive lever for both existing fuel ethanol producers and new entrants targeting lower-carbon pathways.
Enzymes For Fuel Ethanol Market
Why 2026 is an inflection year
- Regulatory alignment: U.S. policy changes that enable co-production of cellulosic ethanol (D3 RINs) alongside corn starch ethanol materially improve the revenue math for enzyme-enabled kernel-fiber pathways. In practice, producers captured additional D3-derived revenue in 2025—an operational lever that is directly tied to access and performance of specialized enzyme systems.
- Economic tailwinds: Record U.S. production in 2024 and steady global demand underpin volume growth for starch-hydrolyzing enzymes. At the same time, tax incentives and low-carbon credits from recent clean-fuel policy measures increase the value of technologies that reduce carbon intensity—another vector where enzyme selection and process design play a measurable role.
- Technology momentum: Incremental gains in hydrolysis and fermentation efficiency—exemplified by improved gallons-per-bushel conversion factors—translate directly into margin expansion when combined with optimized enzyme dosing and process integration strategies.
Market trajectory and strategic implications
PW Consulting’s modeling shows a robust growth trajectory over the forecast period anchored in three drivers: volume growth from blending mandates and demand for renewable fuels, broader adoption of advanced enzymes for cellulosic and corn-kernel fiber pathways, and premium pricing captured via low-carbon credits and RIN arbitrage. The market’s steady CAGR obscures important asymmetries: upstream feedstock shifts and downstream policy changes create windows of outsized opportunity for producers that can rapidly validate and scale enzyme-enabled process modifications.
Enzymes For Fuel Ethanol Market
For corporate strategists and plant managers, this means enzyme strategy must be treated as both a technical and commercial priority. Decisions on supplier selection, in-plant trials, and CAPEX for retrofits should be evaluated through integrated techno-economic and carbon-intensity lenses rather than as isolated reagent purchases.
Enzymes For Fuel Ethanol Market
Competitive landscape — consolidation and capability mapping
The industry is increasingly concentrated; the top three suppliers control a dominant share of the market, and the five largest suppliers command a substantially higher combined share. This concentration reflects a combination of proprietary enzyme platforms, long-standing commercial relationships with large ethanol producers, and growing M&A activity.
Key strategic profiles we assess in the report include:
- Novonesis (formerly Novozymes): Global leader with a deep portfolio of alpha‑amylase, glucoamylase and cellulase solutions optimized across starch liquefaction, saccharification, and cellulosic conversion. Recent strategic acquisitions have broadened their feed-enzyme footprint and strengthened ties with downstream ethanol integrators.
- DuPont (Industrial Biosciences, now part of IFF): Offers market-recognized brands targeting yield improvement and viscosity control in traditional starch-to-ethanol plants, with R&D emphasis on cellulosic enzyme blends.
- dsm-firmenich: Supplies enzymes that improve hydrolysis and fermentation robustness; its partial divestiture and alliance activity have shifted competitive dynamics in 2024–2025.
- Regional and specialist players (AB Enzymes, Codexis, Iogen, Advanced Enzyme Technologies, Amano, BASF, Lallemand, and others): These companies play valuable roles as technology challengers, regional suppliers, and innovators in engineered enzyme platforms and integrated enzyme-yeast solutions. Their strategic importance rises where local feedstock profiles, regulatory incentives, or procurement practices favor responsiveness and bespoke solutions.
Two recent developments crystallize the competitive trajectory: (1) Novonesis’s strategic acquisition activity, which accelerates consolidation of formulation IP and sales channels; and (2) technology launches in plant efficiency (e.g., capacity and energy optimization programs) that indirectly raise the value of enzyme performance by enabling higher-throughput, lower-energy operations without major capital expenditure. Both moves underline an industry shifting from commodity enzyme supply toward packaged technology-service offerings.
What the full PW Consulting report provides (practical, executable content)
Our report is designed as an actionable toolkit for executives, not an academic survey. Highlights include:
- Operational playbooks: Step-by-step dosing optimization procedures, sampling and assay protocols, and pilot trial templates that reduce time-to-validated performance.
- Techno-economic models: Configurable Excel models that quantify the interplay of enzyme cost, yield uplift, energy use, and value from RINs/low-carbon credits under user-defined scenarios.
- Supplier negotiation frameworks: Benchmarks for contract term structures, price-indexing mechanisms, and performance guarantees tied to key process KPIs.
- Risk and procurement matrices: Tools to map single-source exposure, regulatory dependency, and logistics risk for multi-plant operators.
- Carbon intensity (CI) impact assessments: Methodologies to evaluate how enzyme choices and process pathways affect lifecycle CI scores, eligibility for tax credits, and RIN classifications.
- Investment and M&A screens: Criteria for evaluating bolt-on enzyme technology acquisitions, licensing deals, and joint-development partnerships including payback thresholds and integration risk factors.
Critically, the report layers these practical deliverables with proprietary scenario analyses that incorporate forecasted price and policy dynamics, enabling decision-makers to translate enzyme performance into P&L and carbon-accounting outcomes.
Operational priorities for 2026
- Reframe enzyme procurement as a strategic sourcing category: Move from annual spot buys to multiyear performance-based contracts with clear KPIs and shared pilot budgets.
- Accelerate pilots for kernel-fiber and lignocellulosic enzyme blends: Given regulatory pathways for co-produced cellulosic RINs, producers should prioritize rapid validation pilots that quantify incremental D3 value capture.
- Integrate enzyme selection with plant optimization programs: Combine enzyme trials with process-control upgrades and energy-efficiency measures to compound ROI and reduce implementation risk.
- Secure intellectual flexibility: Negotiate rights for on-site trials, data-sharing, and sublicensing to avoid lock-in where technology acceleration is rapid.
- Model RIN and tax credit sensitivity: Use integrated scenarios to stress-test enzyme investments against volatility in D3/D6 pricing and evolving clean-fuel credit regimes.
How consolidation and supplier strategy reshape competitive positioning
Market concentration creates both threats and opportunities. Large suppliers can offer bundled services—technical support, scale-up expertise, and co-investment in pilot validation—which reduces integration risk for large ethanol producers. However, this also raises switching costs and compresses margin extraction for smaller plants unless they leverage cooperative procurement or regional specialists.
From a strategic M&A perspective, mid-sized producers and technology incumbents should evaluate two parallel tracks in 2026: pursue partnerships with leading enzyme platform providers to accelerate low-carbon pathway adoption, or target specialist enzyme companies and IP platforms that provide asymmetric performance improvements in specific feedstock regimes. The full report offers a prioritized target list and screening rubric calibrated to size, geography, and feedstock exposure.
What we deliberately withhold in this preview
This article is a strategic preview designed to communicate insights and action imperatives. To preserve the value of the full market intelligence package, we have intentionally omitted granular regional and application-specific splits, detailed supplier share tables, and the full set of vendor price benchmarks. The comprehensive report includes those tables, downloadable models, and plant-level case studies that underpin the recommendations summarized here.
Closing recommendations — a 90-day plan for executive teams
- Immediate (30 days): Commission an internal audit of enzyme consumption, current supplier terms, and recent plant performance metrics; run a baseline CI calculation linked to current enzyme use.
- Near-term (60 days): Initiate one or more short-duration pilots with selected enzyme platforms focused on kernel-fiber or cellulosic pathways; establish data-sharing and commercial trial agreements.
- Medium-term (90 days): Finalize procurement and partnership decisions for 2026 operational cycles based on pilot outcomes and integrated techno-economic analysis. Define contract KPIs tied to yield, energy, and CI outcomes.
Call to action
For executives preparing 2026 budgets, negotiation calendars, and technology roadmaps, enzyme strategy is no longer a back-office variable—it is a determinant of margin, regulatory compliance, and low-carbon positioning. PW Consulting’s full Enzymes For Fuel Ethanol Market report provides the market-level forecasts, supplier benchmarking, and operational playbooks necessary to convert enzyme capabilities into measurable commercial advantage. Access the complete report and the downloadable models to move from strategic intent to implementable plans before your next procurement cycle.
For detailed analysis of this topic, please visit the official page: Enzymes For Fuel Ethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Automotive Ethernet Market to Reach USD 15.7B by 2032, Growing at a 19.52% CAGR
By pmarketresearch, 2026-07-13
Automotive Ethernet Market: Strategic Imperatives for 2026 — PW Consulting Releases New Industry Report
Executive Summary
As vehicles evolve into software-defined platforms, the shift to high-bandwidth, deterministic in-vehicle networking has accelerated. Our new Automotive Ethernet Market report positions industry leaders, OEMs, Tier‑1 suppliers and investors to make decisive, risk-calibrated choices in 2026. The report documents a clear inflection: market value expanded from roughly USD 1.5 billion in 2020 to USD 4.5 billion in 2025 and is forecast to continue growing at a compound annual growth rate (CAGR) of 19.52% over the 2026–2032 window. By 2026 the market is projected to exceed USD 5.4 billion, with multi‑gigabit and zonal architectures driving the next wave of demand through 2032.
Automotive Ethernet Market
Why this report matters for 2026 decision-makers
-
Timing matters. The convergence of advanced driver assistance systems (ADAS), centralized compute, and zonal architectures turns 2026 into a pivotal procurement and architecture year for automotive programs launching in the 2028–2030 model cycles.
Automotive Ethernet Market -
Risk vs. reward. High bandwidth Ethernet variants (from 100BASE‑T1 up to emerging 10GBASE‑T1 implementations) offer dramatic system simplifications and performance gains but introduce new design, EMC and cybersecurity trade‑offs. Our modeling quantifies these trade‑offs in ways that support contract negotiations and supplier selection.
Automotive Ethernet Market -
Regulatory compliance is non‑negotiable. With UN ECE R155 and international cybersecurity requirements in force, Ethernet architecture decisions are inseparable from compliance roadmaps — affecting certification timelines and supplier obligations. The report embeds a regulatory impact matrix linked to adoption scenarios.
What’s inside — actionable elements of the report
-
Proprietary market model and scenario layers: A base forecast (2026–2032) plus three alternate scenarios that stress-test adoption pathways for zonal ECUs, centralized compute, and high‑bandwidth ADAS domains. The model is delivered with a modifiable spreadsheet and sensitivity knobs for component pricing, design-in lead times, and node‑level bandwidth assumptions.
-
Supplier scorecards: Comparative assessments of PHY, switch and software providers across technological maturity, product roadmap clarity, supply chain resilience, and compliance posture. Scorecards are designed to inform shortlist creation for RfPs and strategic partnerships.
-
Technology readiness and integration playbooks: Practical guidance on PHY selection, multi‑drop vs. point‑to‑point tradeoffs, EMC mitigation for unshielded twisted pair deployments, and deterministic networking strategies for real‑time domains. Each playbook includes recommended test protocols and acceptance criteria aligned with ISO and OPEN Alliance standards.
-
TCO and lifecycle models: Total cost of ownership frameworks that capture up‑front hardware delta, wiring harness simplification gains, software migration costs, and long‑term support exposures for security and functional updates.
-
Compliance & certification checklists: Step-by-step preparation plans for UN ECE R155 and ISO 10681 interplay, including cybersecurity evidence packages and integration milestones that influence type‑approval timelines.
-
Market entry and M&A playbook for investors: Identification of capability gaps, supplier consolidation signals, and valuation levers for targets in PHY IP, switch silicon, and validation toolchains.
Competitive landscape — who matters and why
The market exhibits meaningful concentration: the top three firms account for roughly 45.2% of relevant market turnover, and the top five capture about 60.8%. This structure produces a bifurcated competitive dynamic — a high barrier-to-entry silicon and IP tier, and a vibrant ecosystem of tool, test and integration vendors supporting rapid adoption.
-
Broadcom Inc. — Positioned as a silicon leader with BroadR‑Reach and multi‑Gb PHY/switch portfolios. Certification progress on high‑speed Ethernet standards strengthens Broadcom’s relevance for vehicle programs that prioritize margin and integration density.
-
Marvell Technology, Inc. — Marvell’s push into 10GBASE‑T1 and demonstrable vehicle integrations highlight its strategy to capture bandwidth‑intensive ADAS and centralized compute use cases. Integration wins with OEM platforms serve as a template for market penetration.
-
NXP Semiconductors — NXP is notable for marrying PHY and MAC capabilities with its broader MCU/SoC portfolio. Recent switch launches targeted at zonal architectures underscore NXP’s play to lock down domain controller and gateway positions.
-
Texas Instruments — A consistent value player with cost‑optimized PHYs, attractive for high‑volume mid‑tier programs where price and proven supply chains matter most.
-
Microchip Technology — Focused on gateway and domain controller components, Microchip’s offerings are frequently selected in designs where integration and extended temperature support are priorities.
-
Analog Devices — ADI’s portfolio targets niche long‑reach and sensor network applications, leveraging differentiated analog and mixed‑signal expertise for 10BASE‑T1L deployments.
-
Renesas Electronics — With SoC integrations aimed at high‑bandwidth automotive compute, Renesas’ partnerships with Tier‑1s and automotive suppliers seek to accelerate centralized architectures.
-
TTTech Auto — A specialist in deterministic Ethernet and motion‑control networks; TTTech’s real‑time software and switch products appeal to safety‑critical domains and software‑defined vehicle architectures.
-
Vector Informatik — A dominant test, validation and ECU development provider; Vector’s tools remain essential for development process integration and compliance testing.
-
Intrepid Control Systems — Offers diagnostics and connectivity tools optimized for evolving PHY standards; valuable to OEMs and labs managing multi‑protocol testbeds.
Recent strategic moves to watch (selected highlights)
-
Marvell reported production integration of 10GBASE‑T1 PHYs into a major OEM platform in mid‑2025, a milestone that materially de‑risks multi‑gigabit deployments for ADAS.
-
Broadcom achieved key OPEN Alliance compliance for higher‑speed PHY families in late 2025, accelerating qualification cycles for vendors seeking 10Gb solutions.
-
NXP launched a dedicated automotive Ethernet switch in late 2025 aimed at zonal architectures, signaling a defensive move to maintain SoC‑adjacency in vehicle platforms.
-
Renesas’ collaboration with Tier‑1s on 10GBASE‑T1 for next‑generation ECUs underlines the industry’s push to consolidate compute and I/O stacks around standardized Ethernet backbones.
-
TTTech Auto’s public demonstrations of deterministic 10Gb switching underscore the growing need for real‑time guarantees in safety‑relevant, software‑defined vehicle domains.
Standards, bottlenecks and regulatory headwinds
-
Standards momentum: ISO 10681 defines requirements for PHYs up to 10 Gbps while OPEN Alliance workstreams (including TC8 and TC10) continue to shape multi‑drop and multi‑gigabit interoperability. These standards are catalysts — they lower integration friction but raise qualification costs.
-
Technology bottlenecks: High‑speed PHYs (e.g., 1000BASE‑T1 and beyond) impose demanding signal‑processing requirements to mitigate EMI over unshielded cabling. Design teams should budget additional validation cycles and testbed complexity into development plans.
-
Regulatory requirements: UN ECE R155 and related cybersecurity mandates have turned functional architecture decisions into compliance decisions; non‑compliant design paths can trigger protracted rework and delayed type approvals.
-
Safety constraints and power over data: In certain PHY classes, PoDL is effectively excluded due to isolation and ISO 26262 safety constraints — a nuance that affects sensor node power strategies and harness planning.
Strategic recommendations for stakeholders in 2026
-
OEMs: Adopt a phased Ethernet migration roadmap that aligns program milestones with supplier qualification timelines. Prioritize vendor diversity for critical silicon while negotiating long‑term supply agreements to mitigate lead‑time risks.
-
Tier‑1 suppliers: Invest in integration teams with deep PHY, EMC and cybersecurity expertise. Build repeatable zoning architectures and modular domain controllers to accelerate design reuse across programs.
-
Semiconductor vendors: Differentiate on software stacks and deterministic networking features, not only on PHY performance. Prove compliance through third‑party certifications and publish integration guides tailored to automotive toolchains.
-
Investors and M&A teams: Target companies that close capability gaps in test & validation, deterministic switch software, and long‑reach PHYs — assets that unlock acceleration of high‑bandwidth adoption.
-
Compliance teams: Treat cybersecurity and regulatory evidence as program long‑lead items. Embed UN ECE R155 milestones in program reviews and acceptance criteria for new suppliers.
How PW Consulting’s report supports execution
This report is built to be immediately operational: modifiable financial models, supplier scorecards, test regimes and compliance checklists are all included to shorten decision cycles. For procurement teams, the report provides negotiation levers grounded in supplier concentration metrics and TCO scenarios; for system architects, it supplies validated playbooks to manage EMC, deterministic networking and security trade‑offs.
Next steps — where to get the full intelligence
The analysis above is a strategic preview. For program‑level granularity — including the full set of scenario spreadsheets, supplier scorecards, detailed technology adoption timelines and the regional‑application matrices — visit the PW Consulting Automotive Ethernet Market report page. Our subscribers gain access to downloadable models, extended data appendices and a dedicated analyst Q&A session designed to accelerate program decision‑making for 2026 launches.
PW Consulting remains committed to translating complex technical, regulatory and commercial dynamics into executable strategy. For boards, product leaders and investors planning for the mid‑cycle inflection, the choices made in 2026 will materially shape competitive position across the 2028–2032 vehicle generations.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Balanced Salt Buffer Solution Market to Reach USD 1.39 Billion by 2032 at 7.4% CAGR, North America Leads with USD 327.6 Million
By pmarketresearch, 2026-07-13
Balanced Salt Buffer Solution Market — Strategic Imperatives for 2026
As the life sciences supply chain enters a new phase of growth and operational complexity, PW Consulting’s latest market study on Balanced Salt Buffer Solutions (BSBS) provides an essential strategic compass for executives planning investments, partnerships, and capacity decisions in 2026. Our analysis synthesizes market sizing, channel economics, regulatory pressures, and supplier positioning to deliver decision-ready insight — while preserving the proprietary segment-level intelligence that underpins actionable choices. This release outlines the macro trajectory, competitive context, and recommended moves that will matter most to leaders across suppliers, bioprocessors, and institutional buyers.
Balanced Salt Buffer Solution Market
Market Outlook: Size, Pace and What It Means for Strategy
The Balanced Salt Buffer Solution market has expanded steadily through the first half of the decade and is positioned for continued growth. PW Consulting’s topline model — using 2025 as the base year — values the global market at approximately USD 842.5 million in 2025, with an anticipated rise to roughly USD 923.2 million in 2026. We forecast a compound annual growth rate (CAGR) of 7.4% over the projected horizon, driving the market toward well over USD 1.3 billion by the end of our 2026–2032 forecast window.
Balanced Salt Buffer Solution Market
For corporate strategists, the implication is clear: this is a mid-single-digit-to-high-single-digit growth market large enough to justify targeted capacity investments, but nuanced enough that success will hinge on differentiated product offerings, quality certifications, and supply chain resilience rather than pure scale alone.
Balanced Salt Buffer Solution Market
Key Market Dynamics Shaping 2026 Decisions
-
Quality and Regulatory Compliance as Table Stakes — BSBS products intended for cell culture, bioprocessing, and translational work are manufactured and marketed under stringent quality regimes. Our review of manufacturer documentation highlights universal dependence on cGMP frameworks (e.g., 21 CFR 820) and ISO certifications (9001 / 13485) to meet sterility, endotoxin, and consistency expectations. For commercial leaders, certifications are non-negotiable credentials that drive buyer trust and justify premium positioning.
-
Upstream Input Volatility — Sodium chloride represents a primary upstream feedstock. Industry data show the broader sodium chloride market was valued in the tens of billions of USD in 2025 and is experiencing modest growth; regional pricing dynamics and energy inputs remain key cost drivers. For BSBS manufacturers, small fluctuations in salt and energy costs can meaningfully affect margin when selling lower-priced, commoditized formulations — underscoring the need for hedging strategies and operational flexibility.
-
Concentration with Opportunity — Market concentration is material but incomplete. PW Consulting’s competitive mapping indicates the top three manufacturers capture roughly 42.5% of the market, while the top five control around 58.2%. This structure creates dual opportunities: established players can leverage scale and validated quality systems to defend share, while nimble specialists can seize higher-margin niches through customization, bilateral supply agreements with cell therapy developers, and targeted regulatory positioning.
-
Demand Growth Driven by Advanced Biomanufacturing — End-market demand is being propelled by expanded cell culture, stem cell research, and bioprocessing activities globally. As cell and gene therapy pipelines mature toward later-stage trials and commercial production, demand shifts from research-grade formulations to clinical and GMP-grade buffers, raising both revenue potential and qualification friction for suppliers.
Competitive Landscape: Profiles and Strategic Postures
PW Consulting examined the strategic positions and capabilities of leading BSBS suppliers to identify winning archetypes for 2026.
-
Platform & Scale Leaders — Thermo Fisher Scientific : With its Gibco product family and cGMP/ISO manufacturing footprint, Thermo Fisher exemplifies a full-spectrum supplier able to meet the needs of academic labs through to high-volume biomanufacturers. Their competitive advantage rests on brand trust, global distribution, and integrated quality systems that simplify customer qualification.
-
Industrial OEMs with Life-Science Focus — Cytiva (HyClone) & Corning : Cytiva leverages lab-to-bioprocess expertise and Danaher-scale commercialization muscle, emphasizing reproducibility and regulatory alignment. Corning’s HBSS offerings are positioned within its broader cell culture portfolio, with formulation variants addressing transport and short-term incubation use cases. Both rely on technical legacy and channel breadth to protect share.
-
Specialists & Custom Manufacturers — Boston BioProducts, Nucleus Biologics, Captivate Bio : These firms compete on customization, small-batch cGMP capabilities, and close collaboration with cell and gene therapy developers. Their value proposition is speed-to-spec and flexible formats — an attractive proposition for customers advancing clinical programs who require bespoke buffers and rapid documentation for regulatory filings.
-
Regional & Cost-Focused Players — Procell, Biowest, Sigma-Aldrich (Merck) : These suppliers combine localized manufacturing advantages and a portfolio of sterile-filtered products to serve regional scientists and biomanufacturers. Cost-competitive manufacturing, combined with acceptable quality certifications, helps them retain price-sensitive segments while advancing toward higher-spec opportunities.
-
Device/Consumable Integrators — Sartorius : Firms with adjacent technologies in bioprocessing and cell handling can cross-sell buffer solutions as part of integrated workflows (e.g., washing, transport, and closed-system processing), providing convenience advantages to customers and higher lifetime value for suppliers.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Intelligence
Our full report goes beyond high-level commentary to provide operational tools for commercial and manufacturing decision-makers. Key deliverables include:
-
Proprietary market-sizing models with scenario-based forecasts calibrated to macroeconomic, raw-material and regulatory variables;
-
Supply-chain diagnostic templates identifying single points of failure and opportunity for near-term de-risking;
-
Pricing benchmarks and margin maps that inform contract negotiation and go-to-market tactics;
-
Qualification roadmaps and checklist playbooks for moving research-grade products into GMP channels; and
-
Competitive intelligence dossiers on leading suppliers — including manufacturing footprints, certification status, product differentiation levers, and partnership case studies — designed to support M&A, JV, and distributor selection.
We intentionally withhold some proprietary segment-level splits and granular revenue-by-application tables from this executive summary in order to preserve the integrity of our modeling and to direct commercial users to the authenticated report for transaction-support materials.
Strategic Recommendations for 2026
-
Differentiate through Quality & Documentation: Secure or upgrade cGMP and relevant ISO certifications if you serve clinical or late-stage bioprocess customers. Investment in validated testing (endotoxin, osmolality, sterility) and detailed batch documentation materially reduces buyer friction and shortens qualification timelines.
-
Move Up the Value Stack: Pursue niche formulations and custom services tailored to cell and gene therapy developers. Premiumized, documented buffers command higher margins and strengthen long-term supply agreements.
-
Hedge Input Risk & Rationalize SKUs: Use procurement strategies for key feedstocks (e.g., salt contracts, energy pass-through clauses) and streamline SKU portfolios to optimize plant throughput and reduce changeover costs.
-
Forge Channel Partnerships: For suppliers without global reach, strategic distributor agreements and co-branded programs can accelerate penetration into regulated markets while preserving capital.
-
Prepare for Consolidation Opportunities: With the top-tier firms controlling a meaningful share of the market, selective M&A or technology partnerships offer an accelerated route to scale and certification access — particularly attractive for specialty players seeking to supply clinical-grade channels.
Operational Playbook for Buyers and Procurement Teams
-
Validate supplier certifications and batch release testing as part of any procurement RFQ for clinical or manufacturing use; include qualification timelines and audit provisions in contracts.
-
Build multi-supplier strategies for critical formulations and consider regional dual-sourcing to mitigate transport-related disruptions.
-
Negotiate longer lead-times for custom formulations but include performance-based SLAs and change-control frameworks to protect timelines for downstream production.
Conclusion — Why 2026 Is a Pivotal Year
The BSBS market in 2026 is neither a pure commodity race nor a narrow bespoke niche; it is a hybrid arena where rigorous quality compliance, supply-chain resilience, and targeted product differentiation determine winners. PW Consulting’s forecasted growth path and concentrated supplier landscape both create opportunities and pressing strategic choices for incumbents and new entrants alike. Companies that align investments in certification, formulation innovation, and procurement sophistication will convert growth into durable value.
For commercial teams planning market entry, M&A desks evaluating targets, or procurement leaders renegotiating supply contracts in 2026, our full report contains the granular datasets, supplier scorecards, and transaction playbooks you will need to execute with confidence. Visit the PW Consulting report page to access the comprehensive model, proprietary segmentation tables, and step-by-step implementation tools that support board-level decision-making.
For detailed analysis of this topic, please visit the official page: Balanced Salt Buffer Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rechargeable Handheld Metal Detector Market Set to Grow at a 6.25% CAGR, Driving Industry Momentum
By pmarketresearch, 2026-07-13
Rechargeable Handheld Metal Detector Market: Strategic Preview for 2026 Decision-Makers
Executive Snapshot
PW Consulting’s new market study on Rechargeable Handheld Metal Detectors (base year 2025, forecast 2026–2032) quantifies a market transitioning from steady, procurement-driven demand into a phase of technology-led replacement and higher-value specification. Our analysis pegs the global market at approximately USD 240.5 Million in 2025, with a near-term uptick to about USD 261.0 Million in 2026 and a compound annual growth rate (CAGR) of 6.25% across the 2026–2032 forecast window, reaching the mid-hundreds by 2032. These headline metrics set the stage for executive decisions on product roadmaps, vendor selection, and operational investments in FY-2026 and beyond.
Rechargeable Handheld Metal Detector Market
Why this report matters for 2026 strategy
-
Procurement clarity: As public security budgets reallocate toward value-per-touch technologies, procurement teams must balance unit cost vs. lifetime operational value (battery life, calibration needs, serviceability). Our report translates market growth into realistic procurement volumes and replacement cycles that will inform 2026 CAPEX planning.
Rechargeable Handheld Metal Detector Market -
Technology differentiation: The marketplace is shifting from commodity wands to differentiated rechargeable models that emphasize battery chemistry, ergonomics, waterproofing, and regulatory compliance. The report identifies which features materially affect adoption and total cost of ownership.
Rechargeable Handheld Metal Detector Market -
Competitive posture: Suppliers and buyers alike need a compact view of market concentration and the innovation vectors of tier‑one and fast‑growing OEMs to prioritize partnerships, certification efforts, and distribution strategies.
What the full report delivers (practical, actionable content)
-
Validated market sizing and forecasting: A transparent methodology covering historicals (2020–2025), 2026 base recalibration, and scenario-based projections to 2032 in USD Million—designed to be plug‑and‑play for procurement forecasts and financial models.
-
Buyer decision matrix: Comparative frameworks that map product features (battery life, charging interfaces, sensitivity modes, IP ratings, NIJ compliance) to buyer personas (aviation security, events, law enforcement, industrial loss prevention).
-
Technology and product benchmarks: Side‑by‑side technical scoring (operational hours, charging standards, multi-frequency capability, environmental ruggedness) to support spec sheet decisions without having to reverse engineer vendor claims.
-
Regulatory and standards matrix: A concise treatment of relevant certifications and evolving standards—critical for vendors and purchasers to secure government and airport contracts.
-
Go‑to‑market and service playbooks: Regional channel archetypes, aftersales service models, warranty and battery-replacement economics, and a recommended pricing architecture for 2026 product launches.
-
Supply‑chain risk assessment: Raw‑material exposure (notably lithium‑ion battery supply and USB charging componentry), contract manufacturing patterns, and mitigation strategies for near‑term disruption.
-
Investment and M&A signals: Identifies capability gaps where bolt‑on acquisitions or strategic partnerships yield rapid market access or technological leapfrogging.
Competitive Landscape — who shapes purchasing choices
The market remains a mix of longstanding security-equipment incumbents and specialized OEMs. Leading manufacturers continue to compete on reliability, certification, battery performance, and service networks. Our study profiles the major players and articulates what each brings to procurement tables:
-
Garrett Metal Detectors (Garland, TX): A legacy brand with strong recognition across airports and events. Recent product introductions emphasize USB‑C rechargeable options, enhanced sensitivity tiers, waterproofing, and application‑specific models for law enforcement—moves that protect their installed base while targeting selective upgrades.
-
CEIA (Arezzo, Italy): Known for high‑performance units with compliance to NIJ standards. Their product positioning favors institutional buyers prioritizing certified performance and traceable calibration practices.
-
Securina Detection (Shenzhen): Aggressive on price‑performance, integrating contemporary conveniences (USB‑C charging, vibration alerts) that align with fast replacement cycles in schools and events markets.
-
NUCTECH and Smiths Detection: These larger security-systems firms leverage integrated sales channels (e.g., aviation security suites) and established service contracts to lock in long‑term deployments of rechargeable handhelds alongside other screening technologies.
-
Smaller specialized OEMs (e.g., GXC, Autoclear, Westminster Group partners, Shenzhen Pinpoint, Dongguan Viking): These vendors focus on specific niches—extended battery life, NIJ compliance without calibration, or compact designs for constrained checkpoints—making them attractive for targeted procurement strategies.
Notably, product announcements through 2025–early‑2026 reflect two converging dynamics: (1) manufacturers are standardizing around lithium‑ion chemistries and USB‑C charging for usability and logistical simplicity; and (2) vendors pursue NIJ-aligned certification paths and ruggedized designs to win institutional contracts. These themes are documented and benchmarked in the report.
Market dynamics and risk factors shaping 2026 choices
-
Demand drivers: Rising public security concerns and evolving threat models continue to prop demand from transportation hubs, venues, and public institutions. Buyers are moving away from disposable battery models toward rechargeable devices with predictable lifecycle costs.
-
Standards and certification: Compliance to NIJ test standards and their updates is increasingly a procurement precondition. Buyers should prioritize certified units or those with clear certification roadmaps to avoid retrofit costs or lost tenders.
-
Battery supply and end‑of‑life management: Lithium‑ion battery sourcing and lifecycle handling (including safe disposal and swap programs) are operational issues that will affect TCO and regulatory compliance, especially in jurisdictions strengthening e‑waste rules.
-
Channel and service economics: Warranty terms, replacement battery availability, and local servicing partners materially affect long‑term cost and uptime. The report models service scenarios to guide vendor selection.
Actionable recommendations for 2026
-
Procurement strategy — adopt a total cost of ownership lens: For 2026 purchases, specify battery‑life minima, certified sensitivity thresholds, and charger standardization (USB‑C) to reduce logistics complexity and operating costs.
-
Certification hedge — require roadmaps: Where immediate NIJ certification is not mandatory, require vendors to commit to certification milestones within contract timelines to protect compliance risk.
-
Modular product requirements — favor upgradeability: Define contracts that allow firmware updates, replaceable batteries, and accessory options to extend device lifecycles and reduce waste.
-
Service and spares — price and contract: Negotiate multi‑year service agreements that include battery replacement bundles and local spares to avoid downtime during peak events.
-
Strategic sourcing — diversify supplier mix: Combine established incumbents for mission‑critical deployments with regional OEMs for volume or price‑sensitive use cases; use short pilot programs to validate performance before scale procurement.
-
M&A and partnerships — pursue capability fills: For vendors seeking growth in 2026, consider acquiring battery‑management expertise, local service networks, or software analytics providers to productize value‑added services (e.g., device health telemetry).
How to use this research in your 2026 planning
Operational leaders should use the report as the basis for three linked workstreams: capital planning (buy vs. lease decisions tied to projected device lifecycles), standards compliance (alignment to NIJ and local regulatory regimes), and supplier performance contracting (service level agreements tied to device uptime and battery replacement cadence). Procurement teams can directly extract forecasted demand profiles and scenario outputs to populate annual budgets, while product teams can prioritize feature investments with direct evidence of buyer willingness to pay.
Next steps and access to the full intelligence
This article highlights core findings and strategic implications; detailed sub‑segment data, regional demand matrices, vendor scorecards, and full pricing and service models are intentionally reserved for the full PW Consulting report to preserve the tactical value of the primary research. For procurement leaders, technology strategists, and investors preparing for 2026, the complete study provides the requisite granularity—down to buyer personas, channel economics, and a tactical procurement checklist.
To obtain the comprehensive dataset, vendor scorecards, and the 2026 tactical playbook, please refer to the full Rechargeable Handheld Metal Detector Market report available from PW Consulting.
For detailed analysis of this topic, please visit the official page: Rechargeable Handheld Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: IoT in Energy Market to Expand at a 13.08% CAGR, Transforming Smart Grids and Asset Management
By pmarketresearch, 2026-07-13
IoT in Energy 2026: Strategic Imperatives from PW Consulting’s Market Outlook
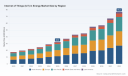
As energy systems around the world accelerate digital transformation, the Internet of Things (IoT) is shifting from pilot projects to mission-critical infrastructure. PW Consulting’s latest research — the Internet of Things (IoT) in Energy Market report — synthesizes seven years of market history and a forward-looking forecast to 2032, delivering a practical playbook for executives who must make high-stakes decisions in 2026. The market is no longer niche: after rising from the teens in 2020, the global IoT in energy market reached an estimated USD 32.4 billion in 2025 and is projected to expand to roughly USD 76.8 billion by 2032, at a compound annual growth rate (CAGR) of 13.08%. This trajectory forces a different set of choices about vendor selection, architecture, and investment timing — choices the report is designed to clarify.
Internet Of Things Iot In Energy Market
Why 2026 Is a Pivotal Year for Enterprise Decision-Makers
-
From experimental to operational: 2024–25 marked the transition from laboratory-scale use cases to grid-level deployments. Organizations moving in 2026 must choose between commoditized components and vertically integrated platforms that promise faster time-to-scale.
Internet Of Things Iot In Energy Market -
Policy and capital tailwinds: Massive energy investment flows into renewables, grids, storage and enabling infrastructure are creating favorable economics for digitalization. Simultaneously, regulatory attention on grid reliability and security is raising the bar for vendor assurances and operational continuity.
Internet Of Things Iot In Energy Market -
Edge and connectivity are decisive: Network architectures that place compute and analytics at the edge are emerging as the default for latency-sensitive and resilience-critical energy applications. Connectivity technologies — from purpose-built LPWANs to private cellular and secure mesh networks — determine operational cost and scalability.
What the Report Delivers: Practical, Executable Intelligence
The PW Consulting report is structured to move leaders from strategy to execution. Without exposing confidential granular slices, the publication provides:
-
Executive playbooks tailored by organizational archetype — utilities, IPPs, energy service companies and industrial energy consumers — describing prioritized use cases, sample P&L impacts, and pilot-to-scale roadmaps.
-
Technology & architecture decision frameworks that map required capabilities (edge compute, secure provisioning, software lifecycle, integration APIs) to vendor archetypes and procurement vehicles.
-
Vendor evaluation scorecards and negotiation levers that translate technical capabilities into measurable criteria for RFPs and SLAs — including testable cybersecurity commitments and interoperability checkpoints.
-
Operational playbooks for rollout sequencing: small-scale validation, controlled scaling, operations maturity, and legacy migration patterns that reduce stranded asset risk.
-
Regulatory impact matrix and compliance checklists: how prominent regional policy shifts (including updated reliability orders and incentivized grid investments) alter deployment timelines and funding eligibility.
-
Financial modeling templates — total cost of ownership (TCO), capex vs opex scenarios, and sensitivity analyses for energy price and device failure rates — enabling rapid alignment with corporate finance.
-
Risk & resilience playbooks for cyber-physical systems and supply chains, with incident response templates and requirements for vendor transparency in firmware and component provenance.
Competitive Landscape: How Market Leaders Are Positioning
The IoT in energy ecosystem is characterized by a mix of industrial incumbents, networking specialists, and software platforms. Market concentration remains modest — a reflection of deep vertical specialization plus an active field of systems integrators and niche innovators (CR3 ~18.4%; CR5 ~25.15%) — which creates both choice and complexity for buyers.
-
Siemens AG deploys digital twins and industrial IoT platforms that tie device telemetry to asset lifecycle workflows. Its strengths are deep domain engineering and integration across generation, transmission and distribution assets; procurement teams should expect premium integration and lifecycle services.
-
Schneider Electric emphasizes an IoT-first architecture for energy management and building-level optimization. Its platform approach accelerates energy-efficiency projects and renewable integration but requires deliberate API and data-model alignment when integrating third-party analytics.
-
ABB Ltd. focuses on asset performance and grid stability, blending industrial control expertise with digital services. ABB’s offerings suit operators who prioritize deterministic control and uptime guarantees across substations and distribution networks.
-
GE Vernova (GE Digital) brings industrial-scale analytics and distribution management systems that target utilities seeking enterprise analytics and asset orchestration at scale. Their Industrial IoT stack is optimized for predictability and heavy-asset environments.
-
Honeywell and Cisco drive complementary strengths — Honeywell in building and industrial energy systems, and Cisco in secure, resilient networking and edge compute. Together, they represent options for secure, converged operational technology and IT architectures.
-
Hitachi Energy , Itron , and Landis+Gyr are prominent in grid automation and metering domains, offering tried-and-true AMI solutions and grid-edge intelligence that are central to utilities’ modernization agendas.
-
Semtech (and cellular IoT vendors) provide the connectivity building blocks for large-scale device deployments; connectivity vendors will increasingly define marginal deployment economics for metering and distribution use cases.
For 2026, the vendor strategy is not binary. Buyers must assemble ecosystems: core platform owners, specialized analytics partners, systems integrators and connectivity vendors. The report includes a recommended sourcing matrix that maps organizational priorities (speed, cost, control, innovation) to optimal partner mixes.
Market Dynamics & Near-Term Risks
-
Connectivity growth and scale effects: LPWAN deployments reached a new scale, with some protocols surpassing a hundred million devices globally and sustaining aggressive CAGRs in the mid-twenties. This matters because connectivity economics cascade into device replacement cycles and lifecycle costs.
-
Capital flow into clean energy: Global energy investment is at historic levels, enabling accelerated grid upgrades and storage deployments that in turn create demand for IoT-enabled operational platforms.
-
Policy & reliability pressure: Recent policy moves emphasizing grid resilience and the increasing penetration of intermittent resources mean that utilities will be judged on both reliability metrics and integration speed — a dual mandate that favors IoT solutions capable of real-time situational awareness.
-
Fragmentation & interoperability risk: A fragmented supplier environment increases vendor lock-in and integration risk. Buyers who postpone standards-based design and interoperability testing face higher costs when scaling beyond pilots.
-
Cyber-physical exposure: As operational systems connect to broader networks, the attack surface increases. The report’s cyber resilience playbook should be a procurement checklist for 2026 contracts.
Actionable Strategic Playbook for 2026
-
Prioritize high-value, low-integration pilots: Start with use cases that deliver measurable operational savings and require the least architecture upheaval. Use the report’s ROI templates to formalize go/no-go criteria.
-
Design for modularity: Insist on open APIs, modular edge nodes, and vendor-neutral data schemas to preserve optionality and reduce switching costs.
-
Insist on evidence-based SLAs: Shift from feature checklists to outcome-based commitments (uptime, latency, reconciliation error rates) and third-party verification clauses.
-
Embed security and governance early: Integrate cyber-physical threat modeling into procurement; require firmware provenance and secure update mechanisms.
-
Build financing into rollout plans: Align opex-friendly connectivity and managed services with capital budgets for hardware upgrades; our financial templates help embed subscription economics into board-level approval packages.
-
Measure vendor concentration risk: Use market-concentration diagnostics to evaluate whether a multi-vendor strategy or platform consolidation better matches your resilience targets and cost constraints.
Why PW Consulting’s Report Is Strategic for 2026 Decisions
Decision-makers in 2026 face compressed timelines: regulatory deadlines, grid modernization funding windows, and vendor roadmaps that lock in technology choices. PW Consulting’s market outlook combines macro trajectory (historical benchmarks and a 13.08% forecast CAGR), vendor benchmarking, and tactical playbooks that translate market signals into executable steps. The report intentionally provides the diagnostic and prescriptive layers needed to de-risk vendor selection and accelerate value capture — while keeping granular commercial data consolidated in the full dataset to protect commercial sensitivity and support interactive modeling on our platform.
Next Steps
For executives preparing capital plans, procurement teams defining RFPs, and technology officers assessing architecture choices, the full PW Consulting IoT in Energy report offers the detailed segmentation tables, regional forecasts, vendor scorecards, and interactive financial models that underpin the strategic guidance summarized here. Access to the full dataset and downloadable templates is available on our report page — where you can also request a bespoke briefing tailored to your organization’s priorities.
PW Consulting remains ready to support scenario modeling, vendor diligence, and pilot-to-scale implementation planning as organizations move from experimentation to operations in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Internet Of Things Iot In Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: High‑Purity L‑Glutamine Market to Surge to USD 418.28 Million by 2032 on a 7.91% CAGR
By pmarketresearch, 2026-07-13
High Purity L-Glutamine Market: Strategic Outlook for 2026 — PW Consulting
PW Consulting’s new market research brief on High Purity L‑Glutamine delivers a focused, decision‑grade intelligence package designed for procurement leaders, C‑suite strategists, and investors preparing for 2026. Built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon, the study documents an established market that reached USD 245.5 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.91% through 2032. This press release outlines the strategic value of the report for near‑term choices while intentionally withholding granular segment allocations — a prompt to consult the full report for transaction‑critical detail.
High Purity L Glutamine Market
Why this report matters for 2026 decision cycles
- Timing of supply decisions: The market’s steady mid‑single‑digit CAGR masks important supply‑side inflection points in 2026 — raw material swings, inventory rebalancing in Asia, and trade policy noise that can change landed costs and lead times within quarters.
- Regulatory and trade risk: Active trade measures and investigations into pharmaceutical imports in the U.S. make sourcing strategies and tariff exposure modelling essential inputs for 2026 sourcing and manufacturing decisions.
- Quality and compliance premium: Demand for injectable‑grade, low‑endotoxin, and certified pharmaceutical supplies is rising. Buyers must quantify the premium for validated supply vs. spot market savings when evaluating supplier contracts.
- M&A and capacity plays: Select producers are expanding overseas capacity; private equity and strategic acquirers will rely on robust demand scenarios, EBITDA sensitivity, and integration risk matrices — all provided in the report’s playbooks.
What the report delivers — practical, transaction‑ready content
- Concise market sizing and CAGR pathways (base year 2025; forecast 2026–2032) with upside/downside scenario modelling for supply shocks and policy interventions.
- Proprietary cost and margin model for high‑purity L‑glutamine that decomposes fermentation OPEX, downstream purification, QC/QA, and logistics into actionable levers for procurement and commercial teams.
- Supplier scorecards and shortlists keyed to certifications (USDMF, CEP, JP/EP/USP compliance), capacity, validated manufacturing practices (GMP/cGMP), and geographic trade exposure.
- Operational playbooks: dual‑sourcing templates, inventory buffers calibrated to lead‑time volatility, QA acceptance criteria, and supplier audit checklists for parenteral‑grade ingredients.
- Regulatory impact assessment: tariff scenarios, import control timelines, and recommended mitigation steps for 2026 procurement cycles.
- M&A and capex advisories: valuation sensitivities, integration checklists, and prioritized target profiles for strategic buyers and financial sponsors.
- Downloadable Excel models and a library of templates (RFP language, contract clauses, technical specifications) to accelerate execution.
Market dynamics and supply‑side diagnostics
The market remains fundamentally fermentation-driven: roughly nine out of ten production tonnes globally originate from fermentation routes that rely on agricultural feedstocks such as glucose and starch derivatives. That concentration in upstream inputs creates a sensitivity to feedstock availability and pricing. In early 2026, for example, glutamic acid — an important upstream intermediate — experienced a modest price decline amid high inventories and dampened downstream demand in China. That movement has immediate implications for producers’ cost curves and spot market behaviour.
High Purity L Glutamine Market
At the same time, buyers increasingly differentiate on quality: pharmaceutical and injectable applications require low‑endotoxin, low‑metals specifications and traceable GMP documentation. This drives a bifurcation between commoditised volumes and premium, validated supplies used in cell culture media, clinical nutrition, and parenteral formulations.
High Purity L Glutamine Market
Competitive landscape — concentration and strategic implications
The study quantifies a moderately concentrated supplier base: the top three producers account for approximately 42.15% of the market, while the top five capture roughly 58.6%. That concentration creates both negotiating leverage for larger purchasers and opportunity for challengers that can invest in validation and differentiated service.
Key players profiled in the report include an international mix of legacy amino‑acid houses, specialty chemicals groups, and regional fermentation champions. Strategic takeaways by cluster:
- Japanese specialty leaders (e.g., Ajinomoto; Kyowa Hakko): Strengths are deep microbial fermentation IP, multiple pharmacopeial filings, and integrated quality systems. These firms command premium positioning for pharma and high‑assurance nutraceutical channels; partnerships or long‑dated agreements with them buy quality certainty but at a price premium.
- European specialty chemicals and GMP‑focused manufacturers (e.g., Evonik; Amino GmbH): Offer strong pharmaceutical certifications (USDMF/CEP), and proximity advantages for European biopharma. Their value proposition centres on regulatory alignment and supply predictability for sensitive applications.
- U.S. niche cGMP suppliers (e.g., Pfanstiehl): Differentiate through ultra‑low endotoxin and excipient‑grade formulations tailored to parenteral demands — an increasingly strategic input for biologics CDMOs and hospital formulary managers.
- Large Chinese and Indian fermentation capacity (e.g., Meihua, Fufeng, Wuhan Amino, and several regulated Indian suppliers): Bring scale and cost advantage, and some are actively expanding overseas capacity. Their offerings are central to volume supply chains but require careful qualification to manage trade‑policy and documentation risk.
Recent market moves validate these dynamics. Notably, a major Chinese producer accelerated overseas capacity expansion in late 2025, and other manufacturers released USP/EP‑compliant high‑purity powders to broaden global market access. Coupled with trade measures and investigations in the U.S., these developments increase the value of supplier diversification and validated supply partnerships in 2026.
Strategic implications and recommended actions for 2026
- Procurement strategy: Move from spot buying to triaged sourcing: (1) secure validated suppliers for critical pharma and parenteral needs with multi‑year contracts; (2) designate a secondary supply pool for lower‑risk applications to capture price flexibility. Use the report’s supplier scorecards to prioritize candidates.
- Risk management: Stress‑test contracts for tariff pass‑through, force majeure, and change‑in‑law clauses. Build inventory triggers and safety stock models from the report’s lead‑time distributions to avoid production interruptions.
- CapEx and vertical options: For mid‑sized manufacturers and larger end‑users considering backward integration, the report provides ROI thresholds, payback timelines, and minimum efficient scale estimates required to justify greenfield or brownfield investments.
- Regulatory readiness: For firms exposed to U.S. import measures, pursue documentation clean‑ups and local validation programs now; the lead time to add USDMF/CEP filings or to secure onshore manufacturing commitments can exceed 12 months.
- M&A and partnerships: Use the report’s valuation sensitivity matrix to identify targets that offer capacity, certification upside, or access to underserved geographies. Earnest due diligence should include on‑site audits and QC data review — templates are included in the report.
How PW Consulting supports 2026 execution
PW Consulting combines deep sector expertise with transaction execution capability. For 2026, we are offering tailored engagements that include supplier due diligence and audits, commercial and technical vendor selection, tariff exposure modelling, and integration support for M&A. Our deliverables are execution‑oriented: annotated supplier shortlists, RFP packages, negotiation playbooks, and capital allocation models aligned with the forecast scenarios in the study.
The published brief functions as a strategic “trailer”: it surfaces the most consequential insights and operational checklists that will shape 2026 decisions while preserving the granular, segment‑level datasets and supplier performance matrices for full‑report subscribers. Those datasets include the disaggregated regional and application demand profiles, contract price histories, and the full supplier scoring model that many executives will use directly in 2026 negotiations.
Next steps
For procurement heads, quality leads, corporate development teams, and investors preparing for actions in 2026, PW Consulting’s High Purity L‑Glutamine Market report is a practical, execution‑ready resource. To access the full dataset, supplier shortlists, and downloadable modelling tools, visit our report page or contact our industry practice to schedule a briefing. The full report provides the missing granular inputs you will need to convert strategic intent into executable supply or transaction plans.
For detailed analysis of this topic, please visit the official page: High Purity L Glutamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Baby Monitoring System Market to Climb from USD 1,850.0 Million in 2025 to USD 3,317.24 Million by 2032 at an 8.7% CAGR
By pmarketresearch, 2026-07-13
Baby Monitoring System Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As companies plan capital allocation, product roadmaps, and go-to-market strategies for 2026, the Baby Monitoring System market presents a clear, data-backed growth narrative — and a set of hazards that demand disciplined strategic responses. PW Consulting’s latest market brief synthesizes historical performance (2020–2025) and a forward forecast (2026–2032) to deliver actionable guidance for executives, investors, and product leaders. The market is expanding at a multi-year compound annual growth rate (CAGR) of 8.7%, rising from a mid-single-billion USD base in 2025 toward a materially larger market by 2032. That momentum, combined with concentrated competitive dynamics and tightening regulation around connected devices and children's data, makes 2026 an inflection year for differentiation.
Baby Monitoring System Market
Why 2026 Is an Inflection Point
- Structural growth meets regulatory friction. The market’s robust CAGR fuels healthy top-line opportunity, but governments and privacy watchdogs are elevating requirements for security, transparency, and data minimization — especially for AI-enabled and internet-connected monitors. New Jersey’s encryption and authentication mandate, the EU AI Act/GDPR overlay, and emerging U.S. state privacy rules are already reshaping product design and go-to-market risk.
- Technology convergence accelerates product differentiation. The intersection of AI-driven analytics, edge computing, and wearable biosensing opens new clinical-grade and wellness-adjacent propositions. At the same time, consumer expectations for seamless mobile experiences and smart-home integration are raising the bar on UX and interoperability.
- Channel shifts are underway. Online channels continue to outpace traditional retail in consumer adoption, but premium buyers and safety-conscious purchasers still rely on trusted offline specialty channels for reassurance and installation support. Winning requires an integrated channel strategy, not a binary online-or-offline bet.
What PW Consulting’s Brief Delivers (Practical, Executable)
- Five-year strategic playbooks tailored to incumbent device providers, emerging wearables players, and security-focused entrants. Each playbook maps product roadmaps to regulatory milestones and channel economics.
- Risk-adjusted investment models that quantify scenarios across different regulatory outcomes and technology adoption paths. These models translate the market CAGR and revenue trajectory into IRR-sensitive decision triggers for R&D and M&A investments.
- Go-to-market frameworks that align pricing architecture, feature tiers, and subscription services with customer lifetime value (CLV) and churn dynamics observed across the historical period.
- Security & privacy checklist for product and firmware design, covering encryption, certificate-based authentication, edge-first processing, and secure update mechanisms — calibrated to comply with both state-level mandates and the EU AI/GDPR regime.
- M&A and partnership screening tools including a scoring rubric for wearable biosensors, edge-AI startups, and global distribution partners to accelerate time-to-market while managing integration risk.
- Implementation templates — from test plans for penetration testing to consumer-facing privacy disclosures that satisfy heightened regulators and skeptical parents alike.
Competitive Landscape: Who Matters and Why
The market is oligopolistic but far from monopolized: the top three players collectively control roughly one-third of the market, and the top five approach half. That structure creates both opportunity for challengers and bargaining power for established brands. Our brief profiles leading incumbents and high-impact challengers across product archetypes, technology stacks, and channel commitments, including:
Baby Monitoring System Market
- Global consumer electronics & healthcare brands with existing scale in parenting categories and broad distribution footprints. These firms leverage brand trust and retail partnerships to defend premium segments.
- Specialist wearable startups delivering differentiated biosensing and clinical-grade signal processing. Their value lies in proprietary algorithms and hardware form factors that can be folded into broader monitoring ecosystems via licensing or acquisition.
- Smart-home and security camera providers offering expandable ecosystems and high-fidelity video capabilities. Their challenge is meeting children’s data privacy constraints while preserving cloud-service monetization levers.
Notable companies driving product and market moves include long-standing consumer brands that combine video, audio, and smart connectivity; specialist firms focused on wearables and AI-powered analytics; and security-camera vendors adapting their products for infant monitoring use-cases. Recent market developments — such as the retention of top brand status by a major toy-and-electronics player in key English-speaking markets and the launch of integrated wearable-plus-camera systems by a prominent smart sock vendor — underscore the continuing blend of brand equity and technology innovation that will shape 2026 competitive dynamics.
Baby Monitoring System Market
Regulation, Privacy, and Secure-by-Design as Strategic Assets
Policy is no longer a compliance footnote — it is a product differentiator. Legislated requirements for end-to-end encryption, certificate-based authentication, and explicit handling of children's data are heightening the baseline cost of entry for internet-connected monitors. The EU AI Act and GDPR demand transparency and data minimization for AI models applied to children’s data, favoring architectures that push more processing to the edge and limit cloud-retained identifiers.
Executives should treat regulatory adherence as a go-to-market capability with measurable returns: faster approvals, reduced liability, and trust premiums that support higher price points and subscription retention. The brief includes a compliance roadmap that sequences technical investments to yield the most defensible market positioning in 18–24 months.
Technology Trends That Will Drive Winners in 2026
- Edge-first AI & federated learning. To reconcile regulatory pressure with the demand for intelligent sleep and breathing analytics, winning products will combine on-device inference with privacy-preserving model updates.
- Hybrid sensor ecosystems. Products that fuse camera, audio, and non-invasive biosensors (wearables or mattress sensors) will unlock richer clinical and wellness signals, but integration and validation standards will be decisive.
- Security-as-a-feature. Vendors that make robust security and transparent data practices a customer-facing benefit will capture trust premiums and reduce churn among privacy-conscious buyers.
- Service monetization beyond hardware. Subscription services for advanced analytics, pediatric telehealth integrations, and sleep-coaching content will increase lifetime value if properly bundled and justified by clinical or behavioral outcomes.
Five Strategic Moves for 2026
- Prioritize privacy-centric product architectures. Short-term conversion wins from cloud-based features are tempting, but long-term value accrues to architectures that minimize cloud retention and enable edge-first analytics to meet EU and U.S. state standards.
- Invest in certification & third-party validation. Independent security audits, pediatric sleep-study validations, and adherence to IoT trustmark programs convert regulatory risk into market advantage.
- Design channels as integrated journeys. Combine online convenience with offline reassurance (installation assistance, hands-on demos, service centers) to address customers across the trust spectrum.
- Accelerate platform partnerships. For established brands, selective acquisitions or licensing deals with wearable and AI startups can secure innovation while limiting integration complexity.
- Build subscription-first propositions with clear ROI. Position advanced analytics and telehealth integrations as outcome-based services, with clear metrics for parental well-being and infant sleep improvement to justify recurring fees.
What Executives Should Do Next
If your 2026 planning cycle includes new product investments, channel realignments, or M&A, treat this market as an orchestrated set of technology, regulatory, and consumer-behavior shifts — not as a single-product opportunity. PW Consulting’s brief is structured to convert market growth assumptions into prioritized action plans: operating-model changes you can execute in 3, 9, and 18 months, capital allocation envelopes tied to scenario outcomes, and specific product features to deprioritize or accelerate based on regulatory risk and consumer willingness-to-pay.
We intentionally present deep strategic guidance and operational tools while preserving the granular segment-level forecasts and region/application breakdowns for subscribers. Those detailed segment tables — including product-type, channel, and regional projections that underpin the headline market trajectory — are available in the full report and the interactive dashboard on our website. This “preview” approach demonstrates analytical depth while directing stakeholders to the secure report environment for the full dataset and downloadable templates.
Closing: What This Means for 2026 Decision Cycles
The baby monitoring market’s near-term expansion offers an attractive runway for differentiated players. But the combination of concentrated competition, heightened regulatory scrutiny, and rapid technology change produces a bifurcated outcome set: firms that treat security, privacy, and validated health signals as strategic assets will capture premium segments and recurring revenue; those that chase short-term cloud feature parity without hardening their privacy posture face regulatory and reputational downside.
For boards and executive teams, the decision calculus for 2026 is straightforward: commit to a privacy-and-security-led product platform, target partnerships that plug capability gaps, and structure channels to capture both convenience-seeking and trust-seeking customers. PW Consulting’s full brief provides the executable plans, quantitative scenario models, and validation templates to operationalize those decisions — enabling leaders to convert the market’s positive growth trajectory into sustained, defensible market share.
How to Access the Full Report
PW Consulting’s Baby Monitoring System Market Brief contains the complete dataset, segmented forecasts, company dossiers, and downloadable implementation templates. For access to the full report and the interactive forecast dashboard, please visit our official report page. The detailed segment-level tables and model workpapers are accessible to subscribers and clients who require the granular inputs necessary for transaction diligence or enterprise planning.
For detailed analysis of this topic, please visit the official page: Baby Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com