

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: High‑Purity L‑Glutamine Market to Surge to USD 418.28 Million by 2032 on a 7.91% CAGR

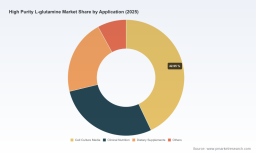
High Purity L-Glutamine Market: Strategic Outlook for 2026 — PW Consulting
PW Consulting’s new market research brief on High Purity L‑Glutamine delivers a focused, decision‑grade intelligence package designed for procurement leaders, C‑suite strategists, and investors preparing for 2026. Built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon, the study documents an established market that reached USD 245.5 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.91% through 2032. This press release outlines the strategic value of the report for near‑term choices while intentionally withholding granular segment allocations — a prompt to consult the full report for transaction‑critical detail.
High Purity L Glutamine Market
Why this report matters for 2026 decision cycles
- Timing of supply decisions: The market’s steady mid‑single‑digit CAGR masks important supply‑side inflection points in 2026 — raw material swings, inventory rebalancing in Asia, and trade policy noise that can change landed costs and lead times within quarters.
- Regulatory and trade risk: Active trade measures and investigations into pharmaceutical imports in the U.S. make sourcing strategies and tariff exposure modelling essential inputs for 2026 sourcing and manufacturing decisions.
- Quality and compliance premium: Demand for injectable‑grade, low‑endotoxin, and certified pharmaceutical supplies is rising. Buyers must quantify the premium for validated supply vs. spot market savings when evaluating supplier contracts.
- M&A and capacity plays: Select producers are expanding overseas capacity; private equity and strategic acquirers will rely on robust demand scenarios, EBITDA sensitivity, and integration risk matrices — all provided in the report’s playbooks.
What the report delivers — practical, transaction‑ready content
- Concise market sizing and CAGR pathways (base year 2025; forecast 2026–2032) with upside/downside scenario modelling for supply shocks and policy interventions.
- Proprietary cost and margin model for high‑purity L‑glutamine that decomposes fermentation OPEX, downstream purification, QC/QA, and logistics into actionable levers for procurement and commercial teams.
- Supplier scorecards and shortlists keyed to certifications (USDMF, CEP, JP/EP/USP compliance), capacity, validated manufacturing practices (GMP/cGMP), and geographic trade exposure.
- Operational playbooks: dual‑sourcing templates, inventory buffers calibrated to lead‑time volatility, QA acceptance criteria, and supplier audit checklists for parenteral‑grade ingredients.
- Regulatory impact assessment: tariff scenarios, import control timelines, and recommended mitigation steps for 2026 procurement cycles.
- M&A and capex advisories: valuation sensitivities, integration checklists, and prioritized target profiles for strategic buyers and financial sponsors.
- Downloadable Excel models and a library of templates (RFP language, contract clauses, technical specifications) to accelerate execution.
Market dynamics and supply‑side diagnostics
The market remains fundamentally fermentation-driven: roughly nine out of ten production tonnes globally originate from fermentation routes that rely on agricultural feedstocks such as glucose and starch derivatives. That concentration in upstream inputs creates a sensitivity to feedstock availability and pricing. In early 2026, for example, glutamic acid — an important upstream intermediate — experienced a modest price decline amid high inventories and dampened downstream demand in China. That movement has immediate implications for producers’ cost curves and spot market behaviour.
High Purity L Glutamine Market
At the same time, buyers increasingly differentiate on quality: pharmaceutical and injectable applications require low‑endotoxin, low‑metals specifications and traceable GMP documentation. This drives a bifurcation between commoditised volumes and premium, validated supplies used in cell culture media, clinical nutrition, and parenteral formulations.
High Purity L Glutamine Market
Competitive landscape — concentration and strategic implications
The study quantifies a moderately concentrated supplier base: the top three producers account for approximately 42.15% of the market, while the top five capture roughly 58.6%. That concentration creates both negotiating leverage for larger purchasers and opportunity for challengers that can invest in validation and differentiated service.
Key players profiled in the report include an international mix of legacy amino‑acid houses, specialty chemicals groups, and regional fermentation champions. Strategic takeaways by cluster:
- Japanese specialty leaders (e.g., Ajinomoto; Kyowa Hakko): Strengths are deep microbial fermentation IP, multiple pharmacopeial filings, and integrated quality systems. These firms command premium positioning for pharma and high‑assurance nutraceutical channels; partnerships or long‑dated agreements with them buy quality certainty but at a price premium.
- European specialty chemicals and GMP‑focused manufacturers (e.g., Evonik; Amino GmbH): Offer strong pharmaceutical certifications (USDMF/CEP), and proximity advantages for European biopharma. Their value proposition centres on regulatory alignment and supply predictability for sensitive applications.
- U.S. niche cGMP suppliers (e.g., Pfanstiehl): Differentiate through ultra‑low endotoxin and excipient‑grade formulations tailored to parenteral demands — an increasingly strategic input for biologics CDMOs and hospital formulary managers.
- Large Chinese and Indian fermentation capacity (e.g., Meihua, Fufeng, Wuhan Amino, and several regulated Indian suppliers): Bring scale and cost advantage, and some are actively expanding overseas capacity. Their offerings are central to volume supply chains but require careful qualification to manage trade‑policy and documentation risk.
Recent market moves validate these dynamics. Notably, a major Chinese producer accelerated overseas capacity expansion in late 2025, and other manufacturers released USP/EP‑compliant high‑purity powders to broaden global market access. Coupled with trade measures and investigations in the U.S., these developments increase the value of supplier diversification and validated supply partnerships in 2026.
Strategic implications and recommended actions for 2026
- Procurement strategy: Move from spot buying to triaged sourcing: (1) secure validated suppliers for critical pharma and parenteral needs with multi‑year contracts; (2) designate a secondary supply pool for lower‑risk applications to capture price flexibility. Use the report’s supplier scorecards to prioritize candidates.
- Risk management: Stress‑test contracts for tariff pass‑through, force majeure, and change‑in‑law clauses. Build inventory triggers and safety stock models from the report’s lead‑time distributions to avoid production interruptions.
- CapEx and vertical options: For mid‑sized manufacturers and larger end‑users considering backward integration, the report provides ROI thresholds, payback timelines, and minimum efficient scale estimates required to justify greenfield or brownfield investments.
- Regulatory readiness: For firms exposed to U.S. import measures, pursue documentation clean‑ups and local validation programs now; the lead time to add USDMF/CEP filings or to secure onshore manufacturing commitments can exceed 12 months.
- M&A and partnerships: Use the report’s valuation sensitivity matrix to identify targets that offer capacity, certification upside, or access to underserved geographies. Earnest due diligence should include on‑site audits and QC data review — templates are included in the report.
How PW Consulting supports 2026 execution
PW Consulting combines deep sector expertise with transaction execution capability. For 2026, we are offering tailored engagements that include supplier due diligence and audits, commercial and technical vendor selection, tariff exposure modelling, and integration support for M&A. Our deliverables are execution‑oriented: annotated supplier shortlists, RFP packages, negotiation playbooks, and capital allocation models aligned with the forecast scenarios in the study.
The published brief functions as a strategic “trailer”: it surfaces the most consequential insights and operational checklists that will shape 2026 decisions while preserving the granular, segment‑level datasets and supplier performance matrices for full‑report subscribers. Those datasets include the disaggregated regional and application demand profiles, contract price histories, and the full supplier scoring model that many executives will use directly in 2026 negotiations.
Next steps
For procurement heads, quality leads, corporate development teams, and investors preparing for actions in 2026, PW Consulting’s High Purity L‑Glutamine Market report is a practical, execution‑ready resource. To access the full dataset, supplier shortlists, and downloadable modelling tools, visit our report page or contact our industry practice to schedule a briefing. The full report provides the missing granular inputs you will need to convert strategic intent into executable supply or transaction plans.
For detailed analysis of this topic, please visit the official page: High Purity L Glutamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com