

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Enzymes for Fuel Ethanol Market to Grow at a 6.3% CAGR Through 2032

Enzymes For Fuel Ethanol Market — Strategic Outlook for 2026 Decision Makers
Executive summary
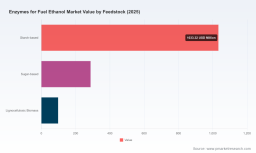
As regulatory signals, feedstock economics, and enzyme innovation converge, the enzymes-for-fuel-ethanol market is entering a period of predictable expansion and intensified supplier consolidation. PW Consulting’s latest market model projects continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.3%, with the market already valued in the low‑billion USD range by the 2025 base year and anticipated to exceed USD 2.1 billion by the end of the forecast horizon. For executives making capital allocation, procurement, and technology-partnership choices in 2026, the practical implications are clear: enzyme strategy is now a core competitive lever for both existing fuel ethanol producers and new entrants targeting lower-carbon pathways.
Enzymes For Fuel Ethanol Market
Why 2026 is an inflection year
- Regulatory alignment: U.S. policy changes that enable co-production of cellulosic ethanol (D3 RINs) alongside corn starch ethanol materially improve the revenue math for enzyme-enabled kernel-fiber pathways. In practice, producers captured additional D3-derived revenue in 2025—an operational lever that is directly tied to access and performance of specialized enzyme systems.
- Economic tailwinds: Record U.S. production in 2024 and steady global demand underpin volume growth for starch-hydrolyzing enzymes. At the same time, tax incentives and low-carbon credits from recent clean-fuel policy measures increase the value of technologies that reduce carbon intensity—another vector where enzyme selection and process design play a measurable role.
- Technology momentum: Incremental gains in hydrolysis and fermentation efficiency—exemplified by improved gallons-per-bushel conversion factors—translate directly into margin expansion when combined with optimized enzyme dosing and process integration strategies.
Market trajectory and strategic implications
PW Consulting’s modeling shows a robust growth trajectory over the forecast period anchored in three drivers: volume growth from blending mandates and demand for renewable fuels, broader adoption of advanced enzymes for cellulosic and corn-kernel fiber pathways, and premium pricing captured via low-carbon credits and RIN arbitrage. The market’s steady CAGR obscures important asymmetries: upstream feedstock shifts and downstream policy changes create windows of outsized opportunity for producers that can rapidly validate and scale enzyme-enabled process modifications.
Enzymes For Fuel Ethanol Market
For corporate strategists and plant managers, this means enzyme strategy must be treated as both a technical and commercial priority. Decisions on supplier selection, in-plant trials, and CAPEX for retrofits should be evaluated through integrated techno-economic and carbon-intensity lenses rather than as isolated reagent purchases.
Enzymes For Fuel Ethanol Market
Competitive landscape — consolidation and capability mapping
The industry is increasingly concentrated; the top three suppliers control a dominant share of the market, and the five largest suppliers command a substantially higher combined share. This concentration reflects a combination of proprietary enzyme platforms, long-standing commercial relationships with large ethanol producers, and growing M&A activity.
Key strategic profiles we assess in the report include:
- Novonesis (formerly Novozymes): Global leader with a deep portfolio of alpha‑amylase, glucoamylase and cellulase solutions optimized across starch liquefaction, saccharification, and cellulosic conversion. Recent strategic acquisitions have broadened their feed-enzyme footprint and strengthened ties with downstream ethanol integrators.
- DuPont (Industrial Biosciences, now part of IFF): Offers market-recognized brands targeting yield improvement and viscosity control in traditional starch-to-ethanol plants, with R&D emphasis on cellulosic enzyme blends.
- dsm-firmenich: Supplies enzymes that improve hydrolysis and fermentation robustness; its partial divestiture and alliance activity have shifted competitive dynamics in 2024–2025.
- Regional and specialist players (AB Enzymes, Codexis, Iogen, Advanced Enzyme Technologies, Amano, BASF, Lallemand, and others): These companies play valuable roles as technology challengers, regional suppliers, and innovators in engineered enzyme platforms and integrated enzyme-yeast solutions. Their strategic importance rises where local feedstock profiles, regulatory incentives, or procurement practices favor responsiveness and bespoke solutions.
Two recent developments crystallize the competitive trajectory: (1) Novonesis’s strategic acquisition activity, which accelerates consolidation of formulation IP and sales channels; and (2) technology launches in plant efficiency (e.g., capacity and energy optimization programs) that indirectly raise the value of enzyme performance by enabling higher-throughput, lower-energy operations without major capital expenditure. Both moves underline an industry shifting from commodity enzyme supply toward packaged technology-service offerings.
What the full PW Consulting report provides (practical, executable content)
Our report is designed as an actionable toolkit for executives, not an academic survey. Highlights include:
- Operational playbooks: Step-by-step dosing optimization procedures, sampling and assay protocols, and pilot trial templates that reduce time-to-validated performance.
- Techno-economic models: Configurable Excel models that quantify the interplay of enzyme cost, yield uplift, energy use, and value from RINs/low-carbon credits under user-defined scenarios.
- Supplier negotiation frameworks: Benchmarks for contract term structures, price-indexing mechanisms, and performance guarantees tied to key process KPIs.
- Risk and procurement matrices: Tools to map single-source exposure, regulatory dependency, and logistics risk for multi-plant operators.
- Carbon intensity (CI) impact assessments: Methodologies to evaluate how enzyme choices and process pathways affect lifecycle CI scores, eligibility for tax credits, and RIN classifications.
- Investment and M&A screens: Criteria for evaluating bolt-on enzyme technology acquisitions, licensing deals, and joint-development partnerships including payback thresholds and integration risk factors.
Critically, the report layers these practical deliverables with proprietary scenario analyses that incorporate forecasted price and policy dynamics, enabling decision-makers to translate enzyme performance into P&L and carbon-accounting outcomes.
Operational priorities for 2026
- Reframe enzyme procurement as a strategic sourcing category: Move from annual spot buys to multiyear performance-based contracts with clear KPIs and shared pilot budgets.
- Accelerate pilots for kernel-fiber and lignocellulosic enzyme blends: Given regulatory pathways for co-produced cellulosic RINs, producers should prioritize rapid validation pilots that quantify incremental D3 value capture.
- Integrate enzyme selection with plant optimization programs: Combine enzyme trials with process-control upgrades and energy-efficiency measures to compound ROI and reduce implementation risk.
- Secure intellectual flexibility: Negotiate rights for on-site trials, data-sharing, and sublicensing to avoid lock-in where technology acceleration is rapid.
- Model RIN and tax credit sensitivity: Use integrated scenarios to stress-test enzyme investments against volatility in D3/D6 pricing and evolving clean-fuel credit regimes.
How consolidation and supplier strategy reshape competitive positioning
Market concentration creates both threats and opportunities. Large suppliers can offer bundled services—technical support, scale-up expertise, and co-investment in pilot validation—which reduces integration risk for large ethanol producers. However, this also raises switching costs and compresses margin extraction for smaller plants unless they leverage cooperative procurement or regional specialists.
From a strategic M&A perspective, mid-sized producers and technology incumbents should evaluate two parallel tracks in 2026: pursue partnerships with leading enzyme platform providers to accelerate low-carbon pathway adoption, or target specialist enzyme companies and IP platforms that provide asymmetric performance improvements in specific feedstock regimes. The full report offers a prioritized target list and screening rubric calibrated to size, geography, and feedstock exposure.
What we deliberately withhold in this preview
This article is a strategic preview designed to communicate insights and action imperatives. To preserve the value of the full market intelligence package, we have intentionally omitted granular regional and application-specific splits, detailed supplier share tables, and the full set of vendor price benchmarks. The comprehensive report includes those tables, downloadable models, and plant-level case studies that underpin the recommendations summarized here.
Closing recommendations — a 90-day plan for executive teams
- Immediate (30 days): Commission an internal audit of enzyme consumption, current supplier terms, and recent plant performance metrics; run a baseline CI calculation linked to current enzyme use.
- Near-term (60 days): Initiate one or more short-duration pilots with selected enzyme platforms focused on kernel-fiber or cellulosic pathways; establish data-sharing and commercial trial agreements.
- Medium-term (90 days): Finalize procurement and partnership decisions for 2026 operational cycles based on pilot outcomes and integrated techno-economic analysis. Define contract KPIs tied to yield, energy, and CI outcomes.
Call to action
For executives preparing 2026 budgets, negotiation calendars, and technology roadmaps, enzyme strategy is no longer a back-office variable—it is a determinant of margin, regulatory compliance, and low-carbon positioning. PW Consulting’s full Enzymes For Fuel Ethanol Market report provides the market-level forecasts, supplier benchmarking, and operational playbooks necessary to convert enzyme capabilities into measurable commercial advantage. Access the complete report and the downloadable models to move from strategic intent to implementable plans before your next procurement cycle.
For detailed analysis of this topic, please visit the official page: Enzymes For Fuel Ethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com