

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: IoT in Energy Market to Expand at a 13.08% CAGR, Transforming Smart Grids and Asset Management

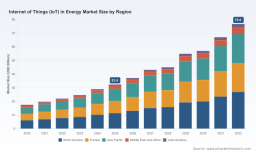
IoT in Energy 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As energy systems around the world accelerate digital transformation, the Internet of Things (IoT) is shifting from pilot projects to mission-critical infrastructure. PW Consulting’s latest research — the Internet of Things (IoT) in Energy Market report — synthesizes seven years of market history and a forward-looking forecast to 2032, delivering a practical playbook for executives who must make high-stakes decisions in 2026. The market is no longer niche: after rising from the teens in 2020, the global IoT in energy market reached an estimated USD 32.4 billion in 2025 and is projected to expand to roughly USD 76.8 billion by 2032, at a compound annual growth rate (CAGR) of 13.08%. This trajectory forces a different set of choices about vendor selection, architecture, and investment timing — choices the report is designed to clarify.
Internet Of Things Iot In Energy Market
Why 2026 Is a Pivotal Year for Enterprise Decision-Makers
-
From experimental to operational: 2024–25 marked the transition from laboratory-scale use cases to grid-level deployments. Organizations moving in 2026 must choose between commoditized components and vertically integrated platforms that promise faster time-to-scale.
Internet Of Things Iot In Energy Market -
Policy and capital tailwinds: Massive energy investment flows into renewables, grids, storage and enabling infrastructure are creating favorable economics for digitalization. Simultaneously, regulatory attention on grid reliability and security is raising the bar for vendor assurances and operational continuity.
Internet Of Things Iot In Energy Market -
Edge and connectivity are decisive: Network architectures that place compute and analytics at the edge are emerging as the default for latency-sensitive and resilience-critical energy applications. Connectivity technologies — from purpose-built LPWANs to private cellular and secure mesh networks — determine operational cost and scalability.
What the Report Delivers: Practical, Executable Intelligence
The PW Consulting report is structured to move leaders from strategy to execution. Without exposing confidential granular slices, the publication provides:
-
Executive playbooks tailored by organizational archetype — utilities, IPPs, energy service companies and industrial energy consumers — describing prioritized use cases, sample P&L impacts, and pilot-to-scale roadmaps.
-
Technology & architecture decision frameworks that map required capabilities (edge compute, secure provisioning, software lifecycle, integration APIs) to vendor archetypes and procurement vehicles.
-
Vendor evaluation scorecards and negotiation levers that translate technical capabilities into measurable criteria for RFPs and SLAs — including testable cybersecurity commitments and interoperability checkpoints.
-
Operational playbooks for rollout sequencing: small-scale validation, controlled scaling, operations maturity, and legacy migration patterns that reduce stranded asset risk.
-
Regulatory impact matrix and compliance checklists: how prominent regional policy shifts (including updated reliability orders and incentivized grid investments) alter deployment timelines and funding eligibility.
-
Financial modeling templates — total cost of ownership (TCO), capex vs opex scenarios, and sensitivity analyses for energy price and device failure rates — enabling rapid alignment with corporate finance.
-
Risk & resilience playbooks for cyber-physical systems and supply chains, with incident response templates and requirements for vendor transparency in firmware and component provenance.
Competitive Landscape: How Market Leaders Are Positioning
The IoT in energy ecosystem is characterized by a mix of industrial incumbents, networking specialists, and software platforms. Market concentration remains modest — a reflection of deep vertical specialization plus an active field of systems integrators and niche innovators (CR3 ~18.4%; CR5 ~25.15%) — which creates both choice and complexity for buyers.
-
Siemens AG deploys digital twins and industrial IoT platforms that tie device telemetry to asset lifecycle workflows. Its strengths are deep domain engineering and integration across generation, transmission and distribution assets; procurement teams should expect premium integration and lifecycle services.
-
Schneider Electric emphasizes an IoT-first architecture for energy management and building-level optimization. Its platform approach accelerates energy-efficiency projects and renewable integration but requires deliberate API and data-model alignment when integrating third-party analytics.
-
ABB Ltd. focuses on asset performance and grid stability, blending industrial control expertise with digital services. ABB’s offerings suit operators who prioritize deterministic control and uptime guarantees across substations and distribution networks.
-
GE Vernova (GE Digital) brings industrial-scale analytics and distribution management systems that target utilities seeking enterprise analytics and asset orchestration at scale. Their Industrial IoT stack is optimized for predictability and heavy-asset environments.
-
Honeywell and Cisco drive complementary strengths — Honeywell in building and industrial energy systems, and Cisco in secure, resilient networking and edge compute. Together, they represent options for secure, converged operational technology and IT architectures.
-
Hitachi Energy , Itron , and Landis+Gyr are prominent in grid automation and metering domains, offering tried-and-true AMI solutions and grid-edge intelligence that are central to utilities’ modernization agendas.
-
Semtech (and cellular IoT vendors) provide the connectivity building blocks for large-scale device deployments; connectivity vendors will increasingly define marginal deployment economics for metering and distribution use cases.
For 2026, the vendor strategy is not binary. Buyers must assemble ecosystems: core platform owners, specialized analytics partners, systems integrators and connectivity vendors. The report includes a recommended sourcing matrix that maps organizational priorities (speed, cost, control, innovation) to optimal partner mixes.
Market Dynamics & Near-Term Risks
-
Connectivity growth and scale effects: LPWAN deployments reached a new scale, with some protocols surpassing a hundred million devices globally and sustaining aggressive CAGRs in the mid-twenties. This matters because connectivity economics cascade into device replacement cycles and lifecycle costs.
-
Capital flow into clean energy: Global energy investment is at historic levels, enabling accelerated grid upgrades and storage deployments that in turn create demand for IoT-enabled operational platforms.
-
Policy & reliability pressure: Recent policy moves emphasizing grid resilience and the increasing penetration of intermittent resources mean that utilities will be judged on both reliability metrics and integration speed — a dual mandate that favors IoT solutions capable of real-time situational awareness.
-
Fragmentation & interoperability risk: A fragmented supplier environment increases vendor lock-in and integration risk. Buyers who postpone standards-based design and interoperability testing face higher costs when scaling beyond pilots.
-
Cyber-physical exposure: As operational systems connect to broader networks, the attack surface increases. The report’s cyber resilience playbook should be a procurement checklist for 2026 contracts.
Actionable Strategic Playbook for 2026
-
Prioritize high-value, low-integration pilots: Start with use cases that deliver measurable operational savings and require the least architecture upheaval. Use the report’s ROI templates to formalize go/no-go criteria.
-
Design for modularity: Insist on open APIs, modular edge nodes, and vendor-neutral data schemas to preserve optionality and reduce switching costs.
-
Insist on evidence-based SLAs: Shift from feature checklists to outcome-based commitments (uptime, latency, reconciliation error rates) and third-party verification clauses.
-
Embed security and governance early: Integrate cyber-physical threat modeling into procurement; require firmware provenance and secure update mechanisms.
-
Build financing into rollout plans: Align opex-friendly connectivity and managed services with capital budgets for hardware upgrades; our financial templates help embed subscription economics into board-level approval packages.
-
Measure vendor concentration risk: Use market-concentration diagnostics to evaluate whether a multi-vendor strategy or platform consolidation better matches your resilience targets and cost constraints.
Why PW Consulting’s Report Is Strategic for 2026 Decisions
Decision-makers in 2026 face compressed timelines: regulatory deadlines, grid modernization funding windows, and vendor roadmaps that lock in technology choices. PW Consulting’s market outlook combines macro trajectory (historical benchmarks and a 13.08% forecast CAGR), vendor benchmarking, and tactical playbooks that translate market signals into executable steps. The report intentionally provides the diagnostic and prescriptive layers needed to de-risk vendor selection and accelerate value capture — while keeping granular commercial data consolidated in the full dataset to protect commercial sensitivity and support interactive modeling on our platform.
Next Steps
For executives preparing capital plans, procurement teams defining RFPs, and technology officers assessing architecture choices, the full PW Consulting IoT in Energy report offers the detailed segmentation tables, regional forecasts, vendor scorecards, and interactive financial models that underpin the strategic guidance summarized here. Access to the full dataset and downloadable templates is available on our report page — where you can also request a bespoke briefing tailored to your organization’s priorities.
PW Consulting remains ready to support scenario modeling, vendor diligence, and pilot-to-scale implementation planning as organizations move from experimentation to operations in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Internet Of Things Iot In Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com