

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts Digital Noise Meter Market to Reach USD 2,144.6 Million by 2032, Expanding at a 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
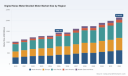
Digital Noise Meter (Decibel Meter) Market: Strategic Outlook for 2026 — PW Consulting Report Preview
Executive summary
PW Consulting’s latest market research on the Digital Noise Meter (Decibel Meter) market offers a tactical blueprint for executives planning capital, product, and go-to-market decisions in 2026. The market has demonstrated steady expansion, rising from approximately USD 1,024.35 Million in 2020 to around USD 1,440.15 Million in 2025, and is forecast to continue its upward trajectory to roughly USD 2,144.55 Million by 2032. Across the forecast window (2026–2032) we model a compound annual growth rate of 5.85%. These headline dynamics—combined with shifting regulatory drivers, accelerating factory digitization, and evolving buyer requirements—make 2026 a pivotal year for repositioning in hardware, software, and services tied to acoustic measurement.
Digital Noise Meter Decibel Meter Market
Why this matters for 2026 decision-makers
- Regulatory enforcement is sharpening demand — Recent international updates and workplace safety thresholds are driving more frequent, higher-fidelity measurement requirements. Compliance is now a procurement trigger rather than a nice-to-have.
- Industrial digitization creates new use cases — Integration of sound monitoring into predictive maintenance, smart factories, and environmental dashboards turns meters from standalone tools into ongoing data sources.
- Monetization is shifting to recurring services — Customers increasingly value analytics, cloud storage, and compliance reporting; vendors who pair hardware with services capture higher lifetime value.
- Precision vs. affordability is a two-speed market — There is simultaneous demand for high-accuracy Class 1 instruments for regulatory and research uses and lower-cost Class 2/portable devices for field and occupational screening.
What PW Consulting’s report delivers (practical, operational intelligence)
The study is built to be operational from day one. Beyond market sizing and top-line forecasts, the report furnishes tools and templates designed for execution rather than only insight:
Digital Noise Meter Decibel Meter Market
- Comprehensive forecast model with scenario toggles (base, conservative, aggressive) and sensitivity settings for price, volume, and service uptake.
- Vendor benchmarking and a proprietary scorecard that evaluates technical accuracy, connectivity, certification compliance, software ecosystem, and channel strength.
- Go-to-market playbooks tailored to incumbent OEMs, new entrants, distributors, and systems integrators, including pricing strategy, channel incentives, and key partner archetypes.
- Regulatory impact matrix mapping OSHA, IEC, ISO and major regional standards to product specifications, procurement cycles, and audit cadence.
- Use-case ROI calculators for industrial noise control, environmental monitoring, building acoustics, transportation noise surveys, and occupational safety programs.
- Supply-chain and component-risk assessment, including lead-time scenarios for MEMS/condensor microphones and calibration service dependencies.
- M&A and partnership screening framework to prioritize targets and partnership structures aligned to strategic objectives (capability buy, customer access, or product roadblocking).
- Implementation accelerators: RFP templates, lab acceptance test (LAT) checklists, and field-deployment validation protocols for Class 1/Class 2 instruments.
Competitive landscape — synthesis and strategic implications
The market exhibits moderate consolidation at the top: our concentration analysis indicates that the three largest players account for a meaningful portion of global revenue, with the top five capturing a clear majority. This creates both defensive pressures for incumbents and targeted opportunities for challengers to differentiate via software, services, or niche specialization.
Digital Noise Meter Decibel Meter Market
- Brüel & Kjær (Nærum, Denmark) — A legacy leader in precision measurement. Strengths: high-accuracy Class 1 instruments, strong brand in environmental and research communities, and advanced analytics. Strategic implication: incumbents should defend by accelerating cloud analytics and service-bundling for long-tail research and compliance customers.
- Extech Instruments (Nashua, USA) — Cost-focused portfolio and strong distributor relationships. Strengths: accessible devices for field teams and occupational safety programs. Strategic implication: expand channel-led service offerings and low-friction upgrade paths (trade-in, firmware unlocks) to migrate users up the value chain.
- PCE Instruments (Meschede, Germany) — Broad product range across Class 1/2 segments. Strengths: flexibility for industrial customers. Strategic implication: prioritize platform unification (single OS/firmware) and centralized calibration services to lock in aftermarket revenue.
- REED Instruments (Wilmington, USA) — Portable and user-friendly meters serving quick-assessment needs. Strategic implication: partner with hearing conservation programs and safety-tech vendors to embed devices into bundled occupational offerings.
- Larson Davis (Provo, USA) — Focused on high-end, instrument-grade meters and advanced analytics. Recent development: May 2025 launch of the Spartan Sound Level Meter Model 821IH, tailored for occupational health with built-in dose metrics. Strategic implication: capitalize on product momentum by expanding subscription analytics and long-term monitoring services.
- Casella (Bedford, UK) — Strong compliance focus with trusted instruments for workplace regulation. Strategic implication: leverage certification expertise to win public-sector tenders and compliance-as-a-service contracts.
- Svantek (Warsaw, Poland) — High-end analyzers and sound-level solutions for professional acoustic measurement. Strategic implication: pursue integration with acoustic simulation and digital twin providers to broaden solution scope.
- RION (Tokyo, Japan) — Precision instruments aligned to JIS/IEC; deep presence in industrial/research segments. Strategic implication: use regional standards compliance to expand into adjacent markets requiring certified measurement.
- Pulsar Instruments (Filey, UK) — Specialization in personal dosimeters and workplace monitoring. Strategic implication: bundle dosimetry hardware with long-term compliance monitoring and employee health dashboards.
Recent sector movements to watch
- Product launches — New instruments with embedded dose metrics and improved ergonomics are accelerating adoption among occupational health teams who demand turnkey reporting.
- Sensor-to-enterprise integrations — Collaborations between metrology providers and smart factory platforms are starting to embed acoustic sensors as routine asset-health signals rather than one-off measurements.
- Regulatory tightening — International standards and national OSHA-level clarifications are elevating minimum device specifications for compliance-grade monitoring, increasing the value of certified instruments.
Strategic playbook for 2026
Based on our analysis, firms should consider the following prioritized actions for the year ahead:
- Invest selectively in IoT and analytics: Prioritize device architectures that enable secure, low-latency telemetry to cloud platforms and offer modular analytics subscriptions. This supports recurring revenue and stickier customer relationships.
- Differentiate on compliance packaging: Create certified solution bundles (hardware + accredited calibration + automated compliance reporting) for regulated buyers to simplify procurement and justify premium pricing.
- Build channel-led service models: Equip distributors and integrators with managed-service playbooks so they can sell outcomes (e.g., continuous monitoring programs) instead of one-off instruments.
- Pursue bolt-on M&A and partnerships: Given the market’s mid-level concentration, targeted acquisitions of analytics firms, calibration labs, or regional specialists can accelerate market access and product breadth.
- Mitigate supply and calibration risk: Map critical components and third-party calibration dependencies, and establish dual-sourcing and regional calibration reciprocal agreements to protect uptime for enterprise customers.
- Align R&D to standards evolution: Ensure product roadmaps are synchronized with IEC and ISO updates so that new releases are compliance-ready on launch.
How PW Consulting’s report supports your 2026 decisions
This preview highlights macro trends and strategic options; the full report equips decision-makers with the granular tools needed to act. Subscribers will receive:
- Detailed segment-level demand curves and pricing bands (note: segment tables are intentionally omitted from this preview to preserve proprietary models).
- Ready-to-use commercial assets: RFP templates, LAT checklists, market-entry financial models, and prioritized target lists for M&A.
- Vendor scorecards with mapped strengths/weaknesses and go-to-partner recommendations by buyer persona.
- Interactive forecast files allowing scenario runs aligned to capital planning cycles for 2026.
Final perspective
The Digital Noise Meter market is entering a phase where instrumentation excellence must be paired with software, services, and ecosystem integration to capture disproportionate value. For 2026, leaders will be those who translate measurement accuracy into compliance certainty, operational intelligence, and recurring revenue streams. PW Consulting’s research provides the route map for those decisions—surface-level headlines are public; the precision instruments of strategy are reserved for the full report.
To access the complete dataset, vendor scorecards, and executable playbooks referenced in this preview, visit the PW Consulting report landing page for the Digital Noise Meter Decibel Meter Market. Our team stands ready to brief executive committees and support bespoke scenario modeling for 2026 investment planning.
For detailed analysis of this topic, please visit the official page: Digital Noise Meter Decibel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra White Rolled Solar Glass Market Poised for Rapid Growth — USD 16.4 Billion in 2025 and a 12.84% CAGR Through 2032
By pmarketresearch, 2026-07-13
Ultra White Rolled Solar Glass Market — Strategic Insights for 2026 Decision-Making
PW Consulting today releases a focused industry briefing drawn from our comprehensive Ultra White Rolled Solar Glass Market Report (base year 2025, forecast 2026–2032). The sector has entered a decisive growth phase: global market value more than doubled from roughly USD 8.4 billion in 2020 to about USD 16.4 billion in 2025 and is projected to reach approximately USD 38.2 billion by 2032, implying a compound annual growth rate (CAGR) of 12.84% through the forecast period. For C-suite leaders, corporate development teams, and industrial investors planning capital allocation in 2026, our analysis translates this top-line trajectory into operational choices, investment roadmaps, and procurement strategies that materially affect margin and time-to-market.
Ultra White Rolled Solar Glass Market
Why this report matters now
-
Structural demand shift: Module manufacturers’ efficiency roadmaps and increasing adoption of BIPV and distributed generation are elevating demand for ultra-clear, low-iron rolled glass with high transmissivity and anti-reflective properties. This is not a cyclical bump; it is a structural re-rating of glass quality requirements across multiple solar product families.
Ultra White Rolled Solar Glass Market -
Supply-side realignment: Manufacturing capacity is reallocating geographically via greenfield builds, onshoring initiatives, and targeted investments in specialized furnaces and roll-forming technology. Recent capacity recognitions and start-ups signal a new era of regional diversification and competitive dynamics.
Ultra White Rolled Solar Glass Market -
Raw material and input risk: The upstream market for ultra-low-iron silica sand is tightening — a market we estimate at USD 2.8 billion in 2025 with long-term growth implications — making feedstock contracting, quality assurance, and alternative sourcing critical priorities.
-
Policy levers and incentives: Recent regulatory changes and targeted tax incentives in major markets are reshaping the calculus for greenfield investments and localization. These measures materially affect project IRR profiles and should influence siting and financing decisions in 2026.
What PW Consulting’s report delivers — practical, transaction-ready outputs
-
Robust market-sizing and scenario engine: Top-down and bottoms-up models spanning 2020–2032 with alternative demand scenarios tied to module efficiency pathways and BIPV adoption curves.
-
Supply-chain heat maps: End-to-end supplier rosters, capacity corridors, logistics chokepoints, and a raw materials dashboard focused on ultra-low-iron silica sand and critical additives.
-
Cost and margin playbook: Manufacturing cost curves by process family (rolled/calendered, embossed/ patterned, float-derived alternatives), sensitivity analyses for energy and material costs, and break-even timelines for capacity investments.
-
Vendor scorecards and benchmarking: Independent assessment criteria including product optical performance (transmittance and AR coating efficacy), tempering quality, daily melting and throughput metrics, and commercial readiness indicators.
-
Go-to-market and procurement templates: Contract structures to secure long-term feedstock supply, sample RFP language for capacity-offtake, and negotiation levers to align industrial partners with module manufacturing roadmaps.
-
M&A and partnership pipeline: Prioritized targets for bolt-on capacity, strategic JV archetypes for rapid localization, valuation frameworks adapted to CAPEX-heavy assets, and integration risks specific to glass manufacturing.
Competitive landscape — who matters and why
The ultra white rolled glass sector is consolidating. Our concentration metrics point to material dominance by the market leaders: the top three producers account for roughly 56.45% of the market, and the top five capture about 74.12%. This level of concentration shapes pricing dynamics, access to premium feedstock, and the competitive playbook for new entrants.
-
Xinyi Solar Holdings Limited — A global anchor in the segment. Xinyi’s calendering expertise and anti-reflective coated offerings set optical performance benchmarks, supported by very large melt capacities in Asia. Its recent commissioning activity in Indonesia (first photovoltaic glass furnace ignited in early 2026) is illustrative of offshore expansion strategies that also target module assembly clusters.
-
Şişecam Group — Turkey’s major industrial champion in patterned and low-iron tempered glass, with a strong foothold in product design for high-efficiency panels and thermal collectors; its differentiated patterned options are favored where light management is a priority.
-
AGC Inc. — Known for extra-clear float glass adapted for solar uses; AGC’s arsenic- and antimony-free product positioning targets premium module lines where material purity is a differentiator.
-
Vitro Architectural Glass — The US expansion program (significant production line additions supported by a major investment tax credit) demonstrates how fiscal incentives can accelerate domestic capacity build-out for patterned solar glass.
-
Stewart Glass LLC — Its new US facility (first fully operational solar glass plant in the country) signals the strategic importance of near-market production; its initial 3.2mm low-iron rolled glass capacity offers insights into entry-scale sizing for localized supply.
-
Regional Chinese and specialized manufacturers — Several established players continue to dominate volume production and technological iterations, especially on roll-forming and tempering innovations that control unit economics.
Notable recent developments that reshape 2026 choices
-
Xinyi’s early-2026 furnace ignition in Indonesia, designed to support multi-gigawatt module production, underlines the strategic emphasis on proximity to module OEM clusters and logistics-optimized capacity.
-
Stewart Glass’s March 2026 production start in Ohio — backed by a USDA loan guarantee — is a practical example of public-private instruments used to de-risk industrial investments that shorten supply chains.
-
Vitro’s Texas expansion, supported by a substantial investment tax credit, highlights how targeted fiscal policy can tip location economics and accelerate installation schedules for patterned lites.
-
Regulatory pivots, including mid-decade tax-credit and sourcing rules in major markets, require companies to model both compliance paths and opportunity capture for stimulus-linked incentives.
Strategic implications and recommended actions for executives in 2026
-
Prioritize supplier locking and feedstock hedging within the next 6–12 months. Given upstream tightness in ultra-low-iron silica sand, long-tenor contracts and quality clauses will protect margin and acceptance rates.
-
Evaluate localization via hybrid models. Where incentives and logistics favor onshore production (and where module makers demand shorter lead times), a phased greenfield or JV approach can preserve capital while securing offtake.
-
Invest selectively in product differentiation: anti-reflective coatings, tailored patterning for BIPV, and advanced tempering yield premium pricing and higher adoption within efficiency-sensitive segments.
-
Embed regulatory scenario workstreams into project finance. Price your projects with and without prevailing tax credits and model the sensitivity to policy changes that can materialize within 12–36 months.
-
Plan M&A with operational integration playbooks. Targets will often be capacity-rich but require upgrades in automation and quality control; our report includes integration checklists and valuation adjustments specific to glass assets.
How PW Consulting’s deliverables accelerate your 2026 decisions
The deliverables are structured to support immediate executive action. We provide an executive decision memo template calibrated to board-level approval cycles; a capital allocation grid that translates demand scenarios into NPV-ranked projects; and procurement negotiation scripts keyed to both feedstock suppliers and toll-processing partners. These tools reduce analysis time by converting raw market signals into prioritized, risk-adjusted choices that can be executed within 90–180 days.
Executive checklist — immediate next steps
-
Run a 90-day supplier diligence and secure quality-anchored silica sand contracts.
-
Evaluate eligibility for local incentives and pre-apply where possible to de-risk timelines.
-
Engage with one or two strategic glass suppliers on pilot AR-coated lites to de-risk product qualification cycles.
-
Commission a short-form M&A screen to identify accretive capacity targets with upgrade potential.
PW Consulting’s Ultra White Rolled Solar Glass Market Report is designed as a strategic operational playbook for 2026. It delivers the market context, competitive benchmarking, and transaction-grade templates executives need to convert growth opportunity into profitable, de-risked action. For full segmentation tables, proprietary supplier scorecards, and our detailed scenario models, visit PW Consulting’s report page to request the complete dataset and executive briefing package.
For detailed analysis of this topic, please visit the official page: Ultra White Rolled Solar Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Explosive Growth in Water Recycling & Reuse Market — 11.25% CAGR Projected Through 2032
By pmarketresearch, 2026-07-13
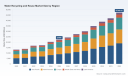
Water Recycling and Reuse Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
As corporate leaders reframe resilience and resource efficiency as board-level priorities, water recycling and reuse has moved from niche sustainability projects to core infrastructure investment. PW Consulting’s new market study — grounded in five years of historical tracking and a seven-year forecast — shows a market that has already expanded from approximately USD 13.2 billion in 2020 to USD 22.5 billion in 2025, and that our modeling anticipates will grow at a compound annual growth rate (CAGR) of 11.25% through the 2026–2032 forecast window, reaching roughly USD 47.4 billion by 2032. For decision-makers preparing 2026 capital plans, procurement roadmaps, or M&A strategies, the report offers practical, investment-grade intelligence calibrated to operational realities.
Water Recycling And Reuse Market
Why 2026 is a Pivot Year
Several converging forces make 2026 a watershed moment for water reuse investments. Regulatory bodies are accelerating reuse-friendly frameworks and standards that reduce technical and permitting friction for reuse projects. Public agencies and major utilities are advancing large-scale municipal reuse programs toward final approvals and construction, while private-sector actors are launching industrial reuse and zero-liquid-discharge initiatives as part of operational decarbonization and cost-avoidance strategies.
Water Recycling And Reuse Market
At the same time, we are seeing consolidation and capability-building among suppliers: strategic acquisitions that combine membrane, analytics, and service capabilities; large project awards that lock in long-term operations-and-maintenance (O&M) revenue streams; and an uptick in modular, decentralized solutions targeted at sites where centralized infrastructure is infeasible. In short, 2026 is the year when policy, project pipelines, and supplier sophistication align — creating actionable windows for investment, partnership, and market entry.
Water Recycling And Reuse Market
What the Report Contains — Practical Tools for 2026 Decisions
- Market sizing & forecast model: A verified time series (2020–2025) and a transparent forecast engine (2026–2032) that isolates demand drivers, sensitivity levers, and upside scenarios for corporations and investors.
- Regulatory and standards map: An operational guide to the current regulatory environment and standards referenced by major plumbing and reuse codes, with decision trees that identify permitting bottlenecks and mitigation strategies.
- Technology and cost archetypes: Comparative techno-economic profiles (membrane, biological, chemical/UV and multi-barrier systems), integration patterns, and lifecycle cost envelopes to support budgetary and CAPEX/OPEX trade-offs.
- Competitive vendor playbooks: Detailed company assessments, capability matrices, contract and partnership templates, and red-flag items for vendor diligence.
- Project-level case studies: Executable dossiers spanning municipal potable reuse, industrial recycling, decentralized community systems, and site-level ZLD deployments — each with procurement timelines, financing approaches, and operational risk registers.
- Investment & M&A scenarios: Value-creation models for strategic buyers and financial sponsors, including accretion/dilution tests for bolt-on acquisitions and partner/joint-venture structures for greenfield projects.
- Digital & service monetization models: Guidance on how to pair monitoring, analytics and service contracts with hardware sales to create annuity streams and improve retention.
Competitive Landscape — How to Read the Leaderboard
The market shows both global system integrators with broad service portfolios and a diverse array of specialized technology suppliers. Ownership of the value chain is increasingly hybrid: membrane manufacturers and chemical suppliers partner with digital platform vendors and EPCs to deliver bundled solutions. PW Consulting’s vendor dossiers in the report synthesize public filings, project evidence, and primary interviews to highlight where incumbents are investing, where capability gaps remain, and how new entrants can win.
- Large integrated players (e.g., Veolia, SUEZ): These firms retain advantages in project delivery, long-term O&M contracts, and industrial-scale engagements. Their scale supports heavy lift projects and multi-decade service agreements.
- Technology specialists (e.g., membrane suppliers, ZLD-focused firms): Companies with deep product portfolios in membranes or zero-liquid-discharge solutions are positioned to capture retrofit and high-recovery industrial opportunities. Their R&D cadence is a decisive differentiator.
- Digital and automation partners (e.g., Siemens, Xylem post-acquisition): Firms combining analytics, sensors, and control systems are winning on operational efficiency and remote O&M models. Recent strategic transactions have married membranes, analytics, and recurring service models, reshaping competitive dynamics.
- Modular & decentralized vendors (e.g., Fluence, Kubota): These players address the growing market segment for compact, rapid-deployment reuse systems — attractive to emerging markets, campuses, and industrial sites seeking reduced permitting complexity and faster paybacks.
Overall, market dynamics favor partnerships: membrane and chemical innovators paired with digital operators and established EPCs create the combinations that win larger, more complex contracts. While top-tier firms command recognizable strengths, the market remains sufficiently fragmented to enable mid-sized specialists and agile new entrants to scale quickly via regional focus, vertical specialization, or technology differentiation.
Recent Industry Developments That Matter for 2026 Strategy
- Strategic M&A continues to reshape capabilities: transactions that integrate membranes, analytics, and service networks accelerate the shift to bundled offerings and longer contract terms.
- Large-scale municipal reuse programs are progressing from planning to permitting and construction, creating multi-year procurement windows for suppliers and financiers.
- Industrial projects — from heavy manufacturing to energy sectors — are moving from pilot to commercial stages as operators prioritize water security and regulatory compliance.
- Standards and codes are converging toward clearer testing and certification regimes for onsite and decentralized reuse systems, reducing market friction for certified solutions.
Strategic Takeaways for Corporates, Utilities, and Investors
- Prioritize optionality in 2026 capital plans: Given the market’s double-digit growth trajectory, reserve capital or structured financing for scalable reuse pilots that can be upsized into full-scale projects when permitting and offtake certainty align.
- Use short-term pilots to de-risk long-term contracts: Modular technologies and service contracts allow operations teams to validate performance and water quality pathways before committing to high-capex builds.
- Bundle products with O&M services: Vendors and investors should favor business models that combine hardware, software, and recurring services to capture long-duration value and mitigate technology obsolescence risks.
- Align procurement with regulatory trajectories: Incorporate anticipated changes in reuse policy and standards into procurement clauses, acceptance testing, and escalation pathways to avoid retrofit costs.
- Evaluate M&A as a fast-track to capability: Where time-to-market matters, strategic acquisitions can instantly add membranes, analytics, or regional footprints; the report includes integration checklists to protect deal value.
How PW Consulting Supports Execution
Beyond the report, PW Consulting offers a suite of advisory services designed for boards and operational leaders executing in 2026: bespoke scenario modeling aligned to corporate finance, vendor selection processes and RFP design, transaction due diligence (technical, commercial and contractual), and structured procurement frameworks that accelerate go-live while protecting downside. Our specialists also provide O&M contract templates and performance-based KPIs that convert uncertain projects into bankable assets for sponsors and lenders.
Conclusion — What to Do Next
The water recycling and reuse market now presents a clear strategic inflection: a sizable and accelerating market backed by maturing standards, large public programs, and shifting supplier economics. For companies that move in 2026 with disciplined pilots, intelligently structured contracts, and strategic partnerships, reuse will deliver not only resilience but new revenue streams and operational savings. For those who delay, the cost of entry and competitive headwinds will rise as incumbents lock long-term O&M deals and capture advantaged project pipelines.
PW Consulting’s Water Recycling and Reuse Market report is designed to be the operational handbook for that first mover — providing the data models, scenario analyses, vendor playbooks, and execution templates that corporate and investment leaders need to act confidently in 2026. For access to the segmented demand tables, project-level financials, vendor scorecards, and full forecast datasets, please visit our report page and request the complete research package.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paid Micro Short Drama Market Reaches USD 1,250 Million in 2025, Poised to Grow at a 22.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Paid Micro Short Drama Production Market: Strategic Outlook for 2026 — PW Consulting Insights
PW Consulting’s new Paid Micro Short Drama Production Market report (base year 2025; forecast period 2026–2032) arrives at a turning point for content strategy and production economics. Our analysis quantifies a market that expanded rapidly through 2020–2025 and is projected to grow at a robust compound annual growth rate (CAGR) of 22.45% across the 2026–2032 forecast window. From an industry value measured in the low hundreds of millions in 2020, the ecosystem exceeded one billion USD by 2025 and is forecast to reach multiple billions by the early 2030s. For decision-makers planning 2026 budgets and strategic initiatives, this trajectory reframes every investment question — from greenlighting slates to selecting production partners and monetization stacks.
Paid Micro Short Drama Production Market
Why this report matters for 2026 decisions
-
Timing: The market has reached commercial scale. Where previously micro-short drama was experimental or promotional, 2025 marked the inflection where dedicated paid channels, vertical-first formats, and coin/subscription mechanisms became repeatable revenue engines. 2026 is the first full planning year where firms can confidently allocate meaningful content CAPEX and expect market-level returns.
Paid Micro Short Drama Production Market -
Cost transformation: Production economics are compressing rapidly due to two forces — compact live-action shoots optimized for vertical formats, and the emergence of AI-native or AI-assisted production workflows. Our report distills how those forces change cost-per-minute and per-episode economics, and what that means for margin-sensitive business models.
Paid Micro Short Drama Production Market -
Structural concentration and competition: The market is not winner-take-all. Top players collectively account for a meaningful but not overwhelming share of revenues, creating opportunity for well-capitalized entrants, regional champions, and specialized studios. We quantify concentration metrics and analyze why differentiated IP and distribution partnerships matter more than scale alone.
Key strategic themes executives must confront in 2026
-
Monetization architecture: Paid micro short dramas are monetized through hybrid mechanisms — microtransactions, time-gated subscriptions, and sponsorship integrations. The right combination depends on audience cohort, content genre, and distribution channel economics. Our report provides frameworks to map unit economics to pricing strategies and lifetime-value (LTV) expectations for core customer segments.
-
Production playbooks and total-cost modelling: Production budgets for professional vertical series vary by ambition, but the sector now supports models from lean rapid-shoot titles to premium “S-class” serialized IP. AI-assisted pipelines can reduce certain production costs dramatically; our modelling shows the trade-offs in quality, speed-to-market, and rights ownership that determine where to deploy AI versus traditional crews.
-
Distribution and partnership engineering: Distribution is multi-architectural — from dedicated short-drama apps and social ecosystems to select OTT partnerships and telco bundles. The most successful strategies in 2025–2026 combine platform placement with direct-to-consumer monetization and strategic regional localizers. We map the commercial levers needed to optimize revenue share, promotional support, and discovery economics.
-
IP strategy and localization: Original IP, licensed adaptations, and brand-sponsored custom content each carry different margin profiles and scalability characteristics. Executives must decide whether to build repeatable original franchises, purchase and localize foreign IP, or monetize through bespoke brand storytelling. Our report offers decision matrices for IP investment versus licensing, including valuation heuristics for short-form serialized formats.
-
Regulatory and labor risk management: Regulatory frameworks and guild agreements have adapted to new formats. Authorities in key markets are introducing transparency and labeling rules for AI-generated content, while major talent guilds have established contracts tailored to microdrama budgets. These developments change cost lines and compliance obligations; our compliance checklist and negotiation playbooks prepare legal and production teams for 2026 realities.
What’s inside the report — practical deliverables
-
Executive dashboards and scenario models: Interactive revenue and cost scenarios across multiple monetization mixes, with stress-testing for acquisition costs and retention decay assumptions.
-
Production cost benchmark toolkit: Line-item templates for vertical microdrama shoots, AI-assisted workflows, and hybrid production; break-even and margin levers for different budget bands.
-
Go-to-market playbooks: Channel strategies for apps, social platforms, OTT windows, and telco partnerships; promotional mechanics and subscriber conversion best practices.
-
IP and content strategy frameworks: Decision matrices for original vs. licensed vs. branded formats, with guidance on territorial rights, localization, dubbing/subtitling economics, and franchise development roadmaps.
-
Regulatory and labor compliance modules: Checklists for AI labeling, content review protocols in regulated markets, and contract templates aligned to the microdrama-specific guild agreements.
-
Competitive intelligence and M&A screen: Profiles of leading studios, platform operators, and production hubs; acquisition scoring templates and integration risk assessments.
Competitive landscape — players shaping 2026
The industry now includes platform-focused operators, vertically specialized producers, and emergent AI-native studios. Notable companies captured in our competitive analysis include:
-
Crazy Maple Studio (ReelShort) — A California-based leader with significant backing and a platform-driven model; focuses on vertical episodic content with coin-based unlocks and subscription hybrids tailored for international audiences.
-
Beijing Dianzhong Technology (DramaBox) — A major China-origin platform and producer with demonstrated strength in overseas markets via localized translations, in-app monetization strategies, and distribution synergies with regional partners.
-
Linmon Media — Expanding from established content production into vertical microdrama slates targeting Asian markets; recent slate launches demonstrate how traditional production houses are adapting format and release strategies for short-form serialized IP.
-
AR Asia Productions — A Hong Kong-based studio that leverages platform and telco partnerships for content delivery across multiple Asian territories and genres, experimenting with bundled distribution models.
-
Vigloo (SpoonLabs) — A Seoul headquartered studio at the vanguard of AI-assisted production, releasing fully AI-native titles in compressed timelines to test English-language and global audiences.
-
Holywater (MyDrama/MyMuse) — A European-based outfit producing Hollywood-caliber microdramas with strategic investment ties and a focus on premium vertical storytelling for international paid platforms.
These companies illustrate three sustainable competitive approaches: platform-anchored ecosystems that control discovery and payments; studio-driven IP owners focusing on franchise value and licensing; and technology-first entrants that compress production cycles and cost bases through AI. Our concentration analysis quantifies that the top-three participants capture a material portion of market revenue while the top-five broaden that footprint — a structure that supports both consolidation and continued niche-entry opportunities.
Recent developments shaping the 2026 playbook
-
Slate launches and regional expansion: Established studios are converting proven long-form IP strategies into microdrama slates geared to regional consumption windows and mobile-first viewing patterns.
-
AI-native releases: Fully AI-produced titles are commercially viable experiments that demonstrate dramatically compressed production cycles; such releases are reshaping content timelines and unit economics.
-
Production infrastructure scaling: Government-backed and private AI-assisted production hubs are enabling thousands of micro-production teams to access tooling and standardized pipelines — accelerating output but also increasing supply-side competition.
-
Regulatory and guild alignment: New labeling requirements for AI-generated content and microdrama-specific talent agreements have created operational constraints and protections that buyers and studios must incorporate into budgets and contracts.
Five recommended moves for 2026
-
Run controlled experiments on monetization hybrids. Test microtransaction-first titles alongside timed subscription windows to identify highest LTV cohorts before large-scale rollouts.
-
Invest selectively in AI-assisted tooling but protect premium IP. Use AI to lower marginal production costs on high-volume slates, while reserving higher-budget human-centric shoots for flagship franchises.
-
Secure distribution partnerships that combine discovery and revenue share. Favor partners offering marketing levers and cross-border promotion rather than pure hosting.
-
Integrate compliance and guild negotiation into pre-production. Treat labeling, content review, and talent contracts as strategic line items that influence scheduling, costs, and release tactics.
-
Adopt an acquisition pipeline for tech and IP. Prioritize targets that enhance production velocity, localization capability, or proprietary audience analytics rather than raw content libraries alone.
How PW Consulting can accelerate your 2026 agenda
Our report is designed as an operational toolkit for executives: from CFOs building content budgets to CMOs optimizing acquisition spend, and from studio heads evaluating production models to corporate development teams screening M&A. The report’s datasets, scenario models, and playbooks translate market-level growth forecasts into executable strategies for 2026 decision cycles.
Note on proprietary detail: This article highlights the report’s major findings and strategic implications but intentionally omits granular segment tables and regional splits to encourage direct engagement with the full dataset and accompanying Excel models. Those detailed segment-level breakouts, company-level revenue estimates, and modelable outputs are available on the report’s source page for subscribers and enterprise clients.
For a copy of the full Paid Micro Short Drama Production Market report, including interactive financial models, company scorecards, and the complete segmentation breakdown used to inform 2026 planning, visit our official report page or contact PW Consulting’s industry desk for a briefing.
For detailed analysis of this topic, please visit the official page: Paid Micro Short Drama Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bottle Valve Market Set to Rise from USD 1,275.6 Million in 2025 to USD 2,216.06 Million by 2032 at an 8.2% CAGR
By pmarketresearch, 2026-07-13
Bottle Valve Market 2026: Strategic Imperatives for Decision‑Makers — PW Consulting Industry Brief
As PW Consulting’s newest market study on the Bottle Valve industry reaches publication, this briefing outlines the research’s strategic value for corporate and investment decisions in 2026. The study synthesizes historic performance (2020–2025), an evidence‑based forecast horizon (2026–2032), and a practical playbook designed to convert market intelligence into executable actions. With the overall market expanding at a compound annual growth rate (CAGR) of 8.2%, and the global market scaling from a mid‑sized market in 2025 into a substantially larger market by the end of the forecast window, the next three to five years will separate incumbents that adapt from those that are merely exposed to structural shifts.
Bottle Valve Market
Why this report matters to 2026 strategic planning
- Timing of decisions: 2026 is the inflection year when near‑term regulatory and supply dynamics converge with technology adoption curves. Investments made now in product re‑engineering, supply resilience, or strategic partnerships will compound materially as the market grows at the reported CAGR.
- Actionable intelligence: The study couples top‑down market sizing and scenario modelling with bottom‑up implications — from materials sourcing to channel economics — enabling CFOs, heads of product, and corporate development teams to prioritize capital allocation with confidence.
- Risk calibration: Our analysis identifies where regulatory tightening, input‑cost pressure, and supplier concentration create asymmetric downside, and where innovation and consolidation offer outsized upside.
Market trajectory at a glance
Built on a consistent historical series through 2025, PW Consulting projects continued expansion through 2032. After the stabilization observed in the early 2020s, the market reaccelerates, reflecting renewed demand across consumer and industrial applications and the adoption of differentiated dispensing technologies. This trajectory is reinforced by our proprietary demand drivers model and scenario stress‑testing, which together quantify the sensitivity of revenue and margin pools to changes in regulation, raw material pricing, and supplier consolidation.
Bottle Valve Market
Key dynamics shaping competitive advantage
- Regulatory tightening: Recent policy moves — including stricter national VOC standards for aerosol coatings enacted in 2025 and ongoing compliance demands under established aerosol safety directives in major trading blocs — are increasing product compliance costs and redefining acceptable formulations and pack designs. Organizations that build robust regulatory systems and compliance‑ready product pipelines will avoid disruptive reformulation cycles.
- Cost and manufacturing structure: Advanced dispensing solutions (e.g., alternative valve architectures) deliver consumer and environmental benefits but typically involve higher manufacturing complexity and unit costs. Successful players balance premium product strategies against operational levers such as economies of scale, localized manufacturing, and vertical integration of critical components.
- Supply and concentration: The market exhibits moderate concentration at the top, creating both opportunity and vulnerability. A few global suppliers command meaningful share, and our concentration metrics underscore why access to second‑tier capacity and contingency suppliers is now a strategic priority.
- M&A and consolidation momentum: Strategic acquisitions are unfolding, reshaping portfolios and capability sets. These moves accelerate time‑to‑market for adjacent capabilities (e.g., high‑pressure gas valves, precision metering systems) and alter sourcing calculus for OEMs and contract packers.
Competitive landscape — who to watch
Our competitive review profiles established global players, regional specialists, and strategic consolidators whose moves will influence 2026 deal flow and sourcing strategies. Highlights include:
Bottle Valve Market
- Precision Valve Corporation (Greenville, SC) — a long‑standing leader in aerosol valve technologies with an expanding innovation agenda. Recent leadership changes and industry recognition for new smart valve designs underscore its focus on differentiated, high‑performance dispensing systems.
- Sherwood Valve (Control Devices / Pittsburgh, PA) — now part of a broader flow‑control platform following a strategic acquisition in early 2026. The combination strengthens capabilities in compressed gas and cylinder valve markets and has implications for industrial and specialty gas customers.
- AptarGroup Inc. (Crystal Lake, IL) — continues to bridge pharmaceutical‑grade dispensing with consumer beauty and personal care, leaning on regulatory compliance and validated manufacturing as competitive moats.
- Lindal Group, Coster Tecnologie, Mitani Valve — European and Asian specialists that collectively sustain innovation in actuator designs, metering and Bag‑on‑Valve (BoV) systems for premium consumer and technical applications.
- Cavagna, Rotarex, GCE Group — strong players in gas cylinder valves and regulators where safety certification and high‑pressure expertise are entry barriers for new entrants.
These profiles are complemented in the full report by capability maps, supplier scorecards, and scenario analyses that translate each competitor’s positioning into likely strategic responses and market share trajectories. For executives evaluating partnerships, JV structures, or M&A targets, the report makes the link from corporate actions to financial and operational outcomes clear and actionable.
Operationally focused deliverables in the report
PW Consulting intentionally structured the deliverables to support execution, not just insight. The report includes:
- Top‑line forecasts and scenario models (base, upside, downside) with sensitivity testing for regulatory, cost, and demand shocks.
- Commercial playbooks for product segmentation, channel rationalization, and pricing strategies that preserve margin under tightening compliance regimes.
- Supply‑chain risk matrices, including second‑source strategies and nearshoring impact assessments, designed to reduce single‑point supplier exposure.
- Technical dossiers and capex case templates for transitioning to alternative valve platforms and scaling differentiated dispensing technologies.
- Regulatory compliance checklist and go‑to‑market timing matrices aligned with major jurisdictional requirements.
- M&A target shortlist methodology, valuation ranges, and integration stress‑tests tailored to strategic buyers and financial sponsors.
Strategic recommendations for 2026
Based on our synthesis of market sizing, competitive moves, and regulatory trends, PW Consulting recommends that leadership teams prioritize three near‑term initiatives:
- Secure regulatory advantage: Invest in compliance and product re‑engineering programs now. Regulatory cycles are shortening, and early movers gain first‑mover shelf access and reduced downstream reformulation costs.
- De‑risk supply and captive capabilities: Develop a two‑track sourcing strategy that combines preferred global suppliers with regionally distributed capacities to limit operational disruption and tariff exposure.
- Targeted inorganic expansion: Use M&A selectively to accelerate capabilities in high‑growth dispensing technologies or to consolidate supply positions. Acquisition activity in early 2026 signals willingness to pay for scale and specialized know‑how; disciplined integration planning will separate value‑creating deals from costly consolidations.
Regulatory and trade signals to monitor
- National and regional VOC and aerosol safety standards — these influence permissible formulations and packaging solutions and can widen competitive moats.
- Tariff and trade policy developments affecting filled aerosol packages — considerations for both sourcing and export strategies.
- Certification and safety protocols for high‑pressure gas valves — critical for customers in industrial and medical markets where failure costs are high.
How executives should use this study
Use the report as a decision‑ready toolset: align budgetary cycles to the scenarios, prioritize capex for compliant product platforms, and set M&A filters that reflect both market growth and concentration dynamics. The study is deliberately structured to bridge strategy and operations — enabling your organization to move from insight to procurement, development, and deal execution with a calibrated risk/return lens.
Closing — what’s withheld and why
To preserve the report’s role as a transaction‑grade, subscription asset, this brief highlights the study’s analytical breadth and operational utility while withholding granular segment-by-region and application‑level revenue breakdowns. Those detailed splits, supplier level‑loadings, and downloadable financial models are available in full via the official report access channel.
For teams preparing 2026 capital plans, supplier negotiations, or M&A pipelines, PW Consulting’s Bottle Valve Market study offers the empirical foundation and practical tools to act with speed and conviction as the market enters its next growth phase.
For detailed analysis of this topic, please visit the official page: Bottle Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Winter Loungewear Market at USD 18.5B in 2025, Set to Rise to USD 28.28B by 2032 on a 6.25% CAGR
By pmarketresearch, 2026-07-13
Winter Loungewear Market: 2026 Strategic Outlook — PW Consulting Winter Loungewear Market Report (Preview)
PW Consulting’s Winter Loungewear Market report (base year 2025) delivers a compact, decision-grade preview for executives shaping product, channel and investment strategies in 2026. The market matured from approximately USD 13.9 billion in 2020 to USD 18.5 billion in 2025, and our modeling projects steady expansion at a 6.25% CAGR through the 2026–2032 forecast window, with the market crossing the USD 28 billion mark by 2032. This briefing outlines the report’s strategic value, core industry dynamics, competitor implications and the tangible playbooks we provide — while intentionally withholding the granular split tables and proprietary segment matrices that are available in full on our client portal.
Winter Loungewear Market
Why this report matters for 2026 corporate decision-making
-
Macro clarity underpins tactical choices: The market’s persistent mid-single-digit CAGR signals an environment where disciplined product differentiation, channel optimization and cost control drive share gains more than broad category expansion. Companies that treat growth as run-rate expansion plus selective disruption will outperform peers.
Winter Loungewear Market -
Fragmented supplier landscape: With a low market concentration (our CR3 and CR5 metrics confirm a fragmented field), scale benefits are bounded and nimble, well-capitalized challengers can win by owning consumer experience, supply chain agility and sustainability credentials rather than by pure volume.
Winter Loungewear Market -
Timing matters: 2026 is a pivotal year for converting pandemic-driven loungewear adoption into sustainable margins. The next 12–18 months will define which brands convert trial into loyalty through assortment engineering, premiumization, and hybrid channel plays.
What the PW Consulting report delivers (practical, action-ready content)
-
Proprietary market sizing and forecast model — built on historical 2020–2025 performance, seasonality adjustments and bottom-up SKU and pricing analytics — enabling bespoke scenario runs for management teams and investors.
-
Go-to-market playbooks — channel-specific initiatives and KPI scorecards for e-commerce/DTC, department store partnerships, and specialty retail. Each playbook contains launch calendars, margin impact simulations, and recommended promotional ladders tailored to winter cycles.
-
Product roadmap templates — prioritization frameworks for fabric mixes, thermal performance vs. comfort trade-offs, and layering strategies to align product development with 2026 consumer segments.
-
Supply chain and sourcing playbook — raw material risk heatmaps, cost-to-serve models, and a phased plan for integrating recycled and sustainable polyester blends while protecting gross margin performance.
-
Retailer and channel negotiation toolkit — win-win merchandising frameworks and promotional timing that preserve ASPs and lifetime value while maintaining share in peak winter windows.
-
M&A and partnership scouting lists — thematic targets across adjacent categories (performance-loungewear, premium sleepwear, fabric technology start-ups) and quick-bid valuation ranges to accelerate due diligence.
-
Risk scenarios and contingency playbooks — six downside and upside scenarios (raw material shocks, demand softness, fast-fashion countermoves) with operational triggers and response matrices for 2026 executives.
Key industry dynamics shaping strategy
-
Material science and circularity: Polyester continues to dominate global fiber output and remains central to fleece and synthetic blends used in winter loungewear. At the same time, recycled fleece and sustainable polyester blends are moving from niche to mainstream as brands respond to consumer demand and regulatory pressure. Expect sourcing complexity as firms balance cost, traceability and circularity.
-
Raw material supply landscape: Global cotton supply trends and polyester production dynamics introduce a multi-year cost backdrop that affects margin management, particularly for mid-market players. Hedging strategies and long-term supplier agreements will be differentiators in 2026.
-
Consumer behaviour: Comfort-first design remains foundational, but premiumization (softness, fit, and performance hybridization) and occasion diversification (home, travel, casual out-of-home) are expanding average order values. Loyalty drivers are moving from price to fabric experience and sustainable credentials.
-
Channel evolution: Digital-first and DTC models continue to capture share, but omnichannel integration — especially flexible returns, try-at-home, and localized fulfillment — will be decisive in improving unit economics and conversion rates.
Competitive landscape — what leading players are signaling
-
Hanesbrands Inc.: A scale-focused incumbent, Hanes leverages affordable comfort staples and deep distribution. Their emphasis on everyday warmth and thermal basics makes them resilient in value-conscious segments. Strategic priority: retain penetration in core channels while testing premium fleece innovations.
-
Gap Inc. & Old Navy (including Athleta): Gap’s multi-brand approach spans value through performance. Old Navy’s Bounce Fleece launches and Athleta’s Forever Fleece hybrids show a two-pronged strategy — keep wide-market reach while monetizing performance and lifestyle upgrades. Strategic priority: cross-brand migration and portfolio margin management.
-
SKIMS: Premium, brand-driven moves (including recent holiday and Team USA Winter Olympics capsule launches) emphasize limited-edition, storytelling-led strategies that drive higher ASPs and social buzz. Strategic priority: scale exclusivity without diluting brand cachet.
-
H&M: Fast-fashion play with broad winter loungewear offerings — competitive on price, quick on trend adoption. Strategic priority: speed-to-shelf and cost management through large-scale sourcing.
-
Eberjey and Aritzia: Boutique-to-premium brands focusing on fabric hand-feel and curated fits. These players demonstrate that targeted premiumization can command margin premiums even in a crowded market. Strategic priority: deepen direct consumer relationships and limited distribution partnerships.
-
PVH (Calvin Klein, etc.): Leveraging brand equity to capture premium sleep-loungewear opportunities with strong margin potential. Strategic priority: licensing and selective retail partnerships to broaden reach while protecting brand positioning.
Recent product moves — such as SKIMS’ Team USA Winter Olympics collection (Jan 2026) and Old Navy’s Bounce Fleece launches (Dec 2025) — underscore two concurrent trends: (1) seasonal limited collections that drive urgency and high-margin lift, and (2) continuous core innovation (fleece hybrids, wide-leg joggers) aimed at sustaining repeat purchases. PW Consulting’s report analyzes these initiatives to show how to replicate gains without sacrificing lifetime value.
Strategic implications and recommended plays for 2026
-
Prioritize “fabric-first” SKU rationalization: Shift assortments toward fewer, higher-performing fabric families that deliver clear consumer benefits and simplify inventory turns. Use our SKU decision matrix to identify top 10 SKUs to double down on for winter 2026.
-
Accelerate circular product pilots: Implement a two-step program — lightweight recycled blend integration to test consumer acceptance, followed by scaled take-back programs with key retail partners. This preserves margin while meeting evolving expectations.
-
Optimize channel economics: Implement differentiated pricing and promotional cadence across DTC and wholesale, supported by dynamic fulfillment strategies to protect margins. Use our channel scorecard to reallocate marketing spend toward the highest IRR customer cohorts.
-
Leverage limited-edition drop strategies: Combine seasonal capsule launches with influencer partnerships to drive short-term ASP uplift and long-term brand heat — an approach validated by recent brand activity across premium and mass-market players.
-
Prepare for concentrated M&A and partnerships: Seek targets that provide either proprietary fabric technologies, direct-to-consumer audience access, or sustainable sourcing capability. Our M&A playbook provides valuation heuristics and fast due-diligence checklists.
How to use this report — from boardroom to product floor
-
Executive briefing pack — one-page CFO and CEO decision summaries that translate market moves into P&L and cash-flow implications.
-
Operational toolkits — SKU rationalization templates, promotional calendars, and supplier negotiation scripts ready for immediate deployment.
-
Data access and modeling — clients receive the underlying forecast model (editable) to run bespoke scenarios, plus a dashboard that links market forecasts to SKU and channel-level KPIs.
Final note — what’s intentionally absent here
This release follows the “trailer” principle: it demonstrates the depth and utility of our analysis and the practical levers available to executives, while intentionally omitting the full granular segmentation tables, regional breakdowns, and the proprietary SKU-level matrices that represent the core intelligence deliverable. Those detailed datasets and interactive models are available through our report subscription and client service portal — where buyers can access complete regional, material and distribution channel splits, plus customizable scenario outputs tailored to 2026 planning cycles.
Next steps
-
For immediate strategic use: request the “Executive Brief + Channel Playbooks” package to receive the editable forecast model and retailer negotiation toolkits.
-
For investment teams: commissioning a tailored deep-dive (M&A screening, due diligence data room) accelerates transaction readiness for late-2026 windows.
-
For product and sourcing teams: schedule a two-day workshop with PW Consulting to convert the report’s roadmaps into a timed, KPI-driven implementation plan for the 2026 winter season.
PW Consulting’s Winter Loungewear Market report equips leaders to transform market momentum into durable competitive advantage. For access to the complete report, proprietary segment tables and the interactive forecast model, visit our official report page or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Winter Loungewear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Utility Monitoring Market to Expand at 14.33% CAGR, Reaching USD 16,155.5 Million by 2032
By pmarketresearch, 2026-07-13
Water Utility Monitoring System Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As water utilities worldwide accelerate digital transformation, PW Consulting’s latest market research — anchored on a 2025 base-year assessment and a 2026–2032 forecast window — delivers the strategic intelligence executives need to make high-consequence decisions in 2026. Our model shows the global water utility monitoring system market expanding at a compound annual growth rate (CAGR) of 14.33% through 2032, reflecting a multi-year lift from the historical period we analyzed (2020–2025). Over that horizon, the market moves from an established multi-billion-dollar base in the mid-2020s toward a materially larger opportunity by 2032. This brief highlights why the report is essential reading for utility CIOs, infrastructure investors, technology OEMs, and procurement leaders preparing budgets, partnerships, and deployment roadmaps next year.
Water Utility Monitoring System Market
Why 2026 Is a Pivot Year
Three converging trends make 2026 a pivotal planning year: an acceleration of AMI/AMI-adjacent deployments, stronger regulatory focus on critical infrastructure cybersecurity, and the urgent capital-replacement cycle driven by aging networks and non-revenue water realities. Utilities that lock in vendor partnerships, data architectures, and procurement strategies in 2026 will be positioned to capture outsized operational and financial benefits across the 2026–2032 forecast window.
Water Utility Monitoring System Market
-
Technology adoption momentum: Smart metering, sensor networks, and cloud-based analytics are moving from pilot to production at scale. Expect 2026 procurement cycles to emphasize interoperability, over-the-air updates, and composable analytics rather than one-off hardware installs.
Water Utility Monitoring System Market -
Cyber and compliance inflection: With SCADA and smart meter networks now explicitly classified as critical infrastructure by regulatory bodies, network segmentation, end-to-end encryption, and continuous monitoring are becoming non-negotiable specifications in RFPs.
-
CapEx re-prioritization: The magnitude of infrastructure renewal requirements — and the persistent drag of non-revenue water — is forcing utilities to triangulate investments that deliver immediate leakage and metering ROI while embedding long-term digital capabilities.
Macro Market Trajectory — What the Numbers Mean for Strategy
PW Consulting’s topline model captures the transition from an early-deployment phase into a rapid commercial expansion. Using our base year of 2025, the market exhibits robust year-on-year scale-up consistent with the 14.33% CAGR through 2032. For executives, that trajectory signals two strategic realities: first, the supplier landscape will continue consolidating around software and systems capabilities (even as hardware remains a substantial component); second, time-to-market and deployment velocity will be critical competitive differentiators.
Our concentration analysis indicates a market that is neither monopolized nor fully fragmented. The three- and five-firm concentration ratios (CR3 and CR5) show meaningful incumbent strength while leaving room for niche innovators and regional specialists to capture share through differentiated offerings and service models. This dynamic produces windows for tactical M&A, partnerships, and selective geographic expansion in 2026.
Actionable Report Components — What You Get
PW Consulting’s full report is designed as an operational toolkit, not just an academic forecast. Key deliverables include:
-
Practical market-sizing and forecast models tailored to support multi-year budget scenarios and sensitivity analysis for capex vs. opex funding pathways.
-
Vendor benchmarking and capability heatmaps that score suppliers across metering hardware, communications stacks, analytics maturity, cybersecurity posture, and professional services delivery.
-
Deployment playbooks with phased implementation templates (pilot → scale → operations), rollout timelines, and workforce-impact assessments to manage the labor shift from manual reading to remote monitoring and analytics operations.
-
Regulatory impact assessment mapping emerging cybersecurity and data privacy requirements to procurement contract language and technical acceptance criteria.
-
Total Cost of Ownership (TCO) and ROI tools including leak-reduction, labor-savings, and asset-replacement scenarios to prioritize projects under constrained budgets.
-
Investment prioritization matrix for utilities and private investors to evaluate technology bets, partnership structures, and near-term M&A targets.
-
RFP and procurement templates incorporating cybersecurity checklists, SLAs for data integrity and latency, and modular procurement options for hardware-agnostic analytics deployments.
Competitive Landscape — How to Read Supplier Moves in 2026
The supplier ecosystem blends global industrial giants with specialist metering OEMs and systems integrators. Our strategic assessment of leading vendors highlights where each competitor is likely to compete for 2026 business and which capabilities are table stakes.
-
Metering specialists (Badger Meter, Kamstrup, Diehl Metering, Neptune/Neptune Technology Group): These firms are consolidating hardware leadership through sensor innovation (ultrasonic, acoustic) and closer coupling of mechanical meters with communications modules. Their value proposition in 2026 will be reliability in the field, low-maintenance lifetime costs, and tight integration into AMI/AMI ecosystems.
-
Communications and platform providers (Itron, Sensus/Xylem, Aclara, Landis+Gyr): These vendors are pushing systems-level solutions — AMI/AMR, network management, and cloud-enabled analytics — with a focus on scale deployments and network robustness. Recent projects and regional expansions demonstrate an aggressive push to convert pilots into city- and region-wide rollouts.
-
Water technology and systems integrators (Xylem, Mueller Water Products, Hach/Danaher): These companies combine sensing, digital twins, and domain expertise to target both quality monitoring and distribution optimization. Their advantage is the ability to bundle advanced sensing with service contracts and long-term performance guarantees.
-
Industrial automation and software heavyweights (Siemens, ABB, Schneider Electric): With mature SCADA, AI, and cybersecurity toolsets, these firms are positioning to serve utilities demanding enterprise-grade analytics and hardened control systems. Their 2025–2026 product launches underscore a push to embed AI-driven predictive maintenance and enhanced cyber-resilience into standard offerings.
Notable recent moves underscore competitive dynamics relevant to 2026 planning: a major metering vendor expanded sensing into wastewater environments through acquisition to pursue end-to-end utility monitoring; another supplier launched next-generation smart meters with enhanced cybersecurity and AI diagnostics; and platform providers continued to broaden regional footprint through targeted projects and partnerships. These developments indicate a market where breadth of capability, depth of data services, and proven cybersecurity are decisive procurement filters.
Regulation, Risk, and Operational Noise — Planning for the Unknown
Senior decision-makers must account for several non-market forces shaping procurement and deployment dynamics in 2026:
-
Cybersecurity as procurement criteria: National guidance treating water control systems as critical infrastructure is already changing contract requirements — expect mandatory network segmentation, encrypted comms, and continuous threat detection to be standard.
-
Capital pressure and infrastructure scale: Large capital needs for water and wastewater systems are forcing staged investment strategies; projects that demonstrate rapid payback through non-revenue water reduction or avoided asset failure will rise to the top of capital plans.
-
Telecom and spectrum constraints: In certain markets, local telecommunications regulation affects IoT deployment models (LoRaWAN, NB-IoT), influencing choices between private networks and carrier partnerships.
-
Workforce transitions: The shift from manual meter-reading to continuous remote monitoring reduces certain O&M costs but increases demand for cybersecurity, data engineering, and remote-operations skill sets — a rebalancing that must be budgeted and planned.
How PW Consulting’s Report Enables 2026 Decisions
Utilities and investors reading this brief should consider three concrete uses of the full PW Consulting report during 2026 planning cycles:
-
De-risk procurement timing: Use our phased deployment templates and vendor maturity scores to decide whether to accelerate purchases in 2026 or to consolidate spending while waiting for next-generation modules with embedded cyber controls.
-
Optimize vendor selection: Apply the benchmarking tools to match utility priorities (leak detection, billing accuracy, asset management) against supplier strengths, then negotiate outcome-based contracts supported by our TCO and ROI calculators.
-
Prioritize investments for regulatory compliance: Leverage our regulatory mapping and cybersecurity checklists to ensure RFPs and contracts meet evolving federal and sector guidance — converting compliance requirements into competitive differentiation.
Next Steps and How to Access Full Intelligence
This executive brief is a strategic preview: it reveals the market direction, key competitive dynamics, practical deliverables, and regulatory considerations that should shape 2026 decisions. For detailed, actionable intelligence — including the full financial model, vendor scorecards, and downloadable procurement templates — PW Consulting’s full report provides the indispensible granularity procurement teams need. Detailed regional and application-level splits, proprietary vendor scoring matrices, and scenario-modeled TCO outputs are reserved for subscribers and purchasers of the report.
In a market growing at double-digit CAGR and transforming how utilities operate and secure critical infrastructure, timely intelligence is the difference between a tactical purchase and a strategic program. PW Consulting’s Water Utility Monitoring System Market report is built for decision-makers who must translate market momentum into resilient, scalable, and secure investments in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Water Utility Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dried Fruit Ingredients Market to Expand at a 5.45% CAGR Through 2032, Report Says
By pmarketresearch, 2026-07-13
Dried Fruit Ingredients Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As food manufacturers recalibrate portfolios toward clean-label, plant-forward, and convenience-driven products, dried fruit ingredients have moved from commodity inputs to strategic levers for innovation and margin. PW Consulting’s latest market study — base year 2025, forecast through 2032 — shows the global dried fruit ingredients market reached approximately USD 9,547 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 horizon, approaching an estimated USD 13,842 million by 2032. For leadership teams setting 2026 plans, this report functions as both a playbook and an early-warning system: it quantifies near-term opportunity while exposing structural risks that can erode value if left unmanaged.
Dried Fruit Ingredients Market
Why this matters for 2026 decision-making
-
Portfolio strategy: Dried fruit ingredients are no longer interchangeable commodities. Premiumization, reduced-sugar formulations and functional positioning (fiber, natural antioxidants) create distinct margin pools. Manufacturers need forward-looking demand signals to prioritize SKUs and R&D investments.
Dried Fruit Ingredients Market -
Supply-chain resilience: Climatic variability, concentrated growing regions and periodic yield shocks create procurement risk that directly impacts cost and service levels. Tactical sourcing and supplier diversification will be essential to stabilize 2026 production plans.
Dried Fruit Ingredients Market -
Regulatory and label-driven reformulation: Continued regulatory focus on added sugars and front-of-pack disclosures reshapes product formulation choices. Regulatory-readiness must feed into product roadmaps and commercial claims ahead of 2026 launches.
-
M&A and partnership prioritization: With innovation accelerating, acquiring dehydration technologies, private-label capabilities or targeted grower relationships may accelerate time-to-market and protect supply.
Key market dynamics highlighted in the PW Consulting study
-
Demand drivers: Convenience snacking, clean-label ingredient demand, and cross-category penetration (bakery, cereal, bars, dairy inclusions) are underpinning steady volumetric growth. Manufacturers are leveraging dried fruits for texture and natural sweetness while seeking reduced-sugar pathways.
-
Supply-side constraints: Weather-induced variability in key production regions and shifting grower economics raise the premium on secure, traceable supply chains. Our scenario work illustrates how a single poor harvest cycle can ripple through costs and availability for up to 18 months.
-
Structural competition: The market displays meaningful fragmentation: a diversified set of specialty processors, grower cooperatives and branded incumbents each compete on quality, form factor (diced, pureed, infused) and technical service. This creates opportunities for differentiation — and for consolidation.
-
Regulatory and trade pressures: Ongoing label modernization and trade actions require active compliance and tariff strategy. Food-safety events and recalls, while infrequent, have outsized reputational and commercial consequences; traceability investments materially reduce this risk.
What the report delivers — operational, commercial, and strategic tools
-
Granular market model (2020–2032) with year-by-year sizing and a bottom-up forecasting engine: scenario settings allow users to stress-test demand and supply shocks, and to project margin outcomes under different pricing regimes.
-
Segmentation architecture by region, fruit type and application — with strategic implications and adoption curves for each cluster. (Note: detailed segmentation tables and downloadable datasets are available in the full report portal.)
-
Supply-chain heatmap and sourcing-risk matrix: evaluates concentration risk, seasonal exposure, and cold-chain complexity for core fruit types and processing forms.
-
Commercial playbooks: negotiation levers for long-term contracting, indexation mechanisms tied to raw-material benchmarks, and sample term sheets tailored for buyers and co-manufacturers.
-
Innovation tracker and technology radar: captures dehydration methods, low-moisture blending techniques, sugar-reduction platforms and packaging innovations that materially affect shelf life and sensory performance.
-
Regulatory matrix and recall-response protocols: compliance timelines, label-risk checklists and an incident escalation framework to protect brand equity.
-
Competitive landscaping and company dossiers: strategic profiles, capability maps and risk/strength assessments of the major suppliers operating in the sector.
Competitive landscape — what the leading suppliers reveal about market direction
PW Consulting’s fieldwork and primary interviews with processors, growers and food manufacturers show a pattern of specialization and capability-led competition among industry participants. Several themes emerge when evaluating the core players:
-
Product-form differentiation: Suppliers that can deliver bespoke textures and controlled moisture — whether through low-moisture diced blends or advanced purees — command a technical premium. Recent trade-show activity has highlighted new low-moisture blends designed for minimal impact on final-product water activity, extending shelf life and simplifying bakery integration.
-
Premiumization and brand-led supply: Established cooperatives and branded processors continue to defend value through quality claims, traceability and supply assurance channels. This is particularly evident where companies position dried fruit as a “premium natural inclusion” for yogurt, cereals and upmarket baked goods.
-
Operational and food-safety focus: Certification updates and new product launches illustrate two parallel priorities — expanding product portfolios while tightening food-safety and traceability systems. Conversely, high-impact recalls remain a salient risk that can rapidly reset customer contracts and procurement behavior.
Examples from recent market activity reinforce these themes: suppliers demonstrating innovation at trade expos, launches of specialized prune and diced fruit ingredient lines, and certification or compliance upgrades. Parallelly, high-profile recalls in the space underscore the need for rigorous supplier audits and enhanced sampling protocols.
Strategic implications and recommended actions for 2026
-
Buyers: Implement multi-sourcing strategies and include agricultural hedge clauses in supplier contracts to manage raw-material volatility. Fast-track validation of alternative fruit forms that achieve sensory parity but reduce supply risk.
-
Ingredient suppliers: Invest selectively in low-moisture processing and value-added blends to differentiate on technical performance, not just raw commodity price. Document traceability and co-develop label-first formulations with major customers.
-
Retailers and brands: Reassess private-label sourcing economics versus brand partnerships. Prioritize suppliers that can support reduced-sugar narratives and provide verified origin claims.
-
Investors and M&A teams: Look for bolt-on targets that provide access to dehydration technology, packaging innovations or direct-farm relationships to secure margins and improve working capital dynamics.
How PW Consulting’s work supports 2026 execution
This report is designed for immediate operational use by procurement, innovation and corporate strategy teams. Key deliverables intended to accelerate action in 2026 include:
-
An interactive Excel model enabling rapid scenario runs (price shocks, tariff changes, yield shortfalls) with P&L and margin outputs.
-
A supplier scorecard and audit checklist that reduces audit cycle time and frames corrective-action plans for high-risk suppliers.
-
Concrete negotiation templates and indexation formulations to align supplier incentives with buyer risk tolerances.
-
Go-to-market and product-development recommendations prioritized by expected margin uplift and time-to-market.
What is deliberately withheld in this preview — and why
Consistent with the “trailer” approach, this preview demonstrates the directional insights and the strategic utility of the full study while intentionally withholding the granular segment-level tables, regional breakout percentages, and the full set of price curves that form the operational core of supplier negotiations and M&A valuations. Those datasets — including downloadable tables, sensitivity dashboards and the full competitive scorecards — are available through the PW Consulting report portal for licensed clients and subscribers.
Final note — immediate priorities for executives
For 2026, executives should prioritize three pragmatic actions informed by the report’s findings: (1) codify supply resilience through diversified contracting and scenario-based inventory plans; (2) accelerate qualification of value-added product forms that enable reduced-sugar and clean-label claims; and (3) implement enhanced traceability and recall-prevention measures that protect brand equity. The market’s projected steady growth creates opportunity, but the path to winning is increasingly technical and operational — not just commercial.
PW Consulting’s full Dried Fruit Ingredients Market report supplies the market-sizing, segmentation detail, supplier intelligence and executable playbooks required to convert this growth into durable commercial advantage. For access to the complete report, interactive datasets and bespoke advisory engagements, please visit our website or contact PW Consulting’s insights team.
For detailed analysis of this topic, please visit the official page: Dried Fruit Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com