

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ultra White Rolled Solar Glass Market Poised for Rapid Growth — USD 16.4 Billion in 2025 and a 12.84% CAGR Through 2032

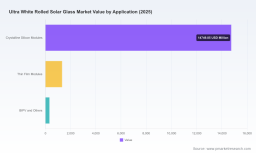
Ultra White Rolled Solar Glass Market — Strategic Insights for 2026 Decision-Making
PW Consulting today releases a focused industry briefing drawn from our comprehensive Ultra White Rolled Solar Glass Market Report (base year 2025, forecast 2026–2032). The sector has entered a decisive growth phase: global market value more than doubled from roughly USD 8.4 billion in 2020 to about USD 16.4 billion in 2025 and is projected to reach approximately USD 38.2 billion by 2032, implying a compound annual growth rate (CAGR) of 12.84% through the forecast period. For C-suite leaders, corporate development teams, and industrial investors planning capital allocation in 2026, our analysis translates this top-line trajectory into operational choices, investment roadmaps, and procurement strategies that materially affect margin and time-to-market.
Ultra White Rolled Solar Glass Market
Why this report matters now
-
Structural demand shift: Module manufacturers’ efficiency roadmaps and increasing adoption of BIPV and distributed generation are elevating demand for ultra-clear, low-iron rolled glass with high transmissivity and anti-reflective properties. This is not a cyclical bump; it is a structural re-rating of glass quality requirements across multiple solar product families.
Ultra White Rolled Solar Glass Market -
Supply-side realignment: Manufacturing capacity is reallocating geographically via greenfield builds, onshoring initiatives, and targeted investments in specialized furnaces and roll-forming technology. Recent capacity recognitions and start-ups signal a new era of regional diversification and competitive dynamics.
Ultra White Rolled Solar Glass Market -
Raw material and input risk: The upstream market for ultra-low-iron silica sand is tightening — a market we estimate at USD 2.8 billion in 2025 with long-term growth implications — making feedstock contracting, quality assurance, and alternative sourcing critical priorities.
-
Policy levers and incentives: Recent regulatory changes and targeted tax incentives in major markets are reshaping the calculus for greenfield investments and localization. These measures materially affect project IRR profiles and should influence siting and financing decisions in 2026.
What PW Consulting’s report delivers — practical, transaction-ready outputs
-
Robust market-sizing and scenario engine: Top-down and bottoms-up models spanning 2020–2032 with alternative demand scenarios tied to module efficiency pathways and BIPV adoption curves.
-
Supply-chain heat maps: End-to-end supplier rosters, capacity corridors, logistics chokepoints, and a raw materials dashboard focused on ultra-low-iron silica sand and critical additives.
-
Cost and margin playbook: Manufacturing cost curves by process family (rolled/calendered, embossed/ patterned, float-derived alternatives), sensitivity analyses for energy and material costs, and break-even timelines for capacity investments.
-
Vendor scorecards and benchmarking: Independent assessment criteria including product optical performance (transmittance and AR coating efficacy), tempering quality, daily melting and throughput metrics, and commercial readiness indicators.
-
Go-to-market and procurement templates: Contract structures to secure long-term feedstock supply, sample RFP language for capacity-offtake, and negotiation levers to align industrial partners with module manufacturing roadmaps.
-
M&A and partnership pipeline: Prioritized targets for bolt-on capacity, strategic JV archetypes for rapid localization, valuation frameworks adapted to CAPEX-heavy assets, and integration risks specific to glass manufacturing.
Competitive landscape — who matters and why
The ultra white rolled glass sector is consolidating. Our concentration metrics point to material dominance by the market leaders: the top three producers account for roughly 56.45% of the market, and the top five capture about 74.12%. This level of concentration shapes pricing dynamics, access to premium feedstock, and the competitive playbook for new entrants.
-
Xinyi Solar Holdings Limited — A global anchor in the segment. Xinyi’s calendering expertise and anti-reflective coated offerings set optical performance benchmarks, supported by very large melt capacities in Asia. Its recent commissioning activity in Indonesia (first photovoltaic glass furnace ignited in early 2026) is illustrative of offshore expansion strategies that also target module assembly clusters.
-
Şişecam Group — Turkey’s major industrial champion in patterned and low-iron tempered glass, with a strong foothold in product design for high-efficiency panels and thermal collectors; its differentiated patterned options are favored where light management is a priority.
-
AGC Inc. — Known for extra-clear float glass adapted for solar uses; AGC’s arsenic- and antimony-free product positioning targets premium module lines where material purity is a differentiator.
-
Vitro Architectural Glass — The US expansion program (significant production line additions supported by a major investment tax credit) demonstrates how fiscal incentives can accelerate domestic capacity build-out for patterned solar glass.
-
Stewart Glass LLC — Its new US facility (first fully operational solar glass plant in the country) signals the strategic importance of near-market production; its initial 3.2mm low-iron rolled glass capacity offers insights into entry-scale sizing for localized supply.
-
Regional Chinese and specialized manufacturers — Several established players continue to dominate volume production and technological iterations, especially on roll-forming and tempering innovations that control unit economics.
Notable recent developments that reshape 2026 choices
-
Xinyi’s early-2026 furnace ignition in Indonesia, designed to support multi-gigawatt module production, underlines the strategic emphasis on proximity to module OEM clusters and logistics-optimized capacity.
-
Stewart Glass’s March 2026 production start in Ohio — backed by a USDA loan guarantee — is a practical example of public-private instruments used to de-risk industrial investments that shorten supply chains.
-
Vitro’s Texas expansion, supported by a substantial investment tax credit, highlights how targeted fiscal policy can tip location economics and accelerate installation schedules for patterned lites.
-
Regulatory pivots, including mid-decade tax-credit and sourcing rules in major markets, require companies to model both compliance paths and opportunity capture for stimulus-linked incentives.
Strategic implications and recommended actions for executives in 2026
-
Prioritize supplier locking and feedstock hedging within the next 6–12 months. Given upstream tightness in ultra-low-iron silica sand, long-tenor contracts and quality clauses will protect margin and acceptance rates.
-
Evaluate localization via hybrid models. Where incentives and logistics favor onshore production (and where module makers demand shorter lead times), a phased greenfield or JV approach can preserve capital while securing offtake.
-
Invest selectively in product differentiation: anti-reflective coatings, tailored patterning for BIPV, and advanced tempering yield premium pricing and higher adoption within efficiency-sensitive segments.
-
Embed regulatory scenario workstreams into project finance. Price your projects with and without prevailing tax credits and model the sensitivity to policy changes that can materialize within 12–36 months.
-
Plan M&A with operational integration playbooks. Targets will often be capacity-rich but require upgrades in automation and quality control; our report includes integration checklists and valuation adjustments specific to glass assets.
How PW Consulting’s deliverables accelerate your 2026 decisions
The deliverables are structured to support immediate executive action. We provide an executive decision memo template calibrated to board-level approval cycles; a capital allocation grid that translates demand scenarios into NPV-ranked projects; and procurement negotiation scripts keyed to both feedstock suppliers and toll-processing partners. These tools reduce analysis time by converting raw market signals into prioritized, risk-adjusted choices that can be executed within 90–180 days.
Executive checklist — immediate next steps
-
Run a 90-day supplier diligence and secure quality-anchored silica sand contracts.
-
Evaluate eligibility for local incentives and pre-apply where possible to de-risk timelines.
-
Engage with one or two strategic glass suppliers on pilot AR-coated lites to de-risk product qualification cycles.
-
Commission a short-form M&A screen to identify accretive capacity targets with upgrade potential.
PW Consulting’s Ultra White Rolled Solar Glass Market Report is designed as a strategic operational playbook for 2026. It delivers the market context, competitive benchmarking, and transaction-grade templates executives need to convert growth opportunity into profitable, de-risked action. For full segmentation tables, proprietary supplier scorecards, and our detailed scenario models, visit PW Consulting’s report page to request the complete dataset and executive briefing package.
For detailed analysis of this topic, please visit the official page: Ultra White Rolled Solar Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com