

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Explosive Growth in Water Recycling & Reuse Market — 11.25% CAGR Projected Through 2032

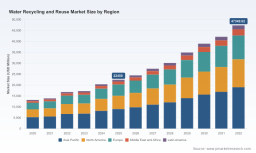
Water Recycling and Reuse Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
As corporate leaders reframe resilience and resource efficiency as board-level priorities, water recycling and reuse has moved from niche sustainability projects to core infrastructure investment. PW Consulting’s new market study — grounded in five years of historical tracking and a seven-year forecast — shows a market that has already expanded from approximately USD 13.2 billion in 2020 to USD 22.5 billion in 2025, and that our modeling anticipates will grow at a compound annual growth rate (CAGR) of 11.25% through the 2026–2032 forecast window, reaching roughly USD 47.4 billion by 2032. For decision-makers preparing 2026 capital plans, procurement roadmaps, or M&A strategies, the report offers practical, investment-grade intelligence calibrated to operational realities.
Water Recycling And Reuse Market
Why 2026 is a Pivot Year
Several converging forces make 2026 a watershed moment for water reuse investments. Regulatory bodies are accelerating reuse-friendly frameworks and standards that reduce technical and permitting friction for reuse projects. Public agencies and major utilities are advancing large-scale municipal reuse programs toward final approvals and construction, while private-sector actors are launching industrial reuse and zero-liquid-discharge initiatives as part of operational decarbonization and cost-avoidance strategies.
Water Recycling And Reuse Market
At the same time, we are seeing consolidation and capability-building among suppliers: strategic acquisitions that combine membrane, analytics, and service capabilities; large project awards that lock in long-term operations-and-maintenance (O&M) revenue streams; and an uptick in modular, decentralized solutions targeted at sites where centralized infrastructure is infeasible. In short, 2026 is the year when policy, project pipelines, and supplier sophistication align — creating actionable windows for investment, partnership, and market entry.
Water Recycling And Reuse Market
What the Report Contains — Practical Tools for 2026 Decisions
- Market sizing & forecast model: A verified time series (2020–2025) and a transparent forecast engine (2026–2032) that isolates demand drivers, sensitivity levers, and upside scenarios for corporations and investors.
- Regulatory and standards map: An operational guide to the current regulatory environment and standards referenced by major plumbing and reuse codes, with decision trees that identify permitting bottlenecks and mitigation strategies.
- Technology and cost archetypes: Comparative techno-economic profiles (membrane, biological, chemical/UV and multi-barrier systems), integration patterns, and lifecycle cost envelopes to support budgetary and CAPEX/OPEX trade-offs.
- Competitive vendor playbooks: Detailed company assessments, capability matrices, contract and partnership templates, and red-flag items for vendor diligence.
- Project-level case studies: Executable dossiers spanning municipal potable reuse, industrial recycling, decentralized community systems, and site-level ZLD deployments — each with procurement timelines, financing approaches, and operational risk registers.
- Investment & M&A scenarios: Value-creation models for strategic buyers and financial sponsors, including accretion/dilution tests for bolt-on acquisitions and partner/joint-venture structures for greenfield projects.
- Digital & service monetization models: Guidance on how to pair monitoring, analytics and service contracts with hardware sales to create annuity streams and improve retention.
Competitive Landscape — How to Read the Leaderboard
The market shows both global system integrators with broad service portfolios and a diverse array of specialized technology suppliers. Ownership of the value chain is increasingly hybrid: membrane manufacturers and chemical suppliers partner with digital platform vendors and EPCs to deliver bundled solutions. PW Consulting’s vendor dossiers in the report synthesize public filings, project evidence, and primary interviews to highlight where incumbents are investing, where capability gaps remain, and how new entrants can win.
- Large integrated players (e.g., Veolia, SUEZ): These firms retain advantages in project delivery, long-term O&M contracts, and industrial-scale engagements. Their scale supports heavy lift projects and multi-decade service agreements.
- Technology specialists (e.g., membrane suppliers, ZLD-focused firms): Companies with deep product portfolios in membranes or zero-liquid-discharge solutions are positioned to capture retrofit and high-recovery industrial opportunities. Their R&D cadence is a decisive differentiator.
- Digital and automation partners (e.g., Siemens, Xylem post-acquisition): Firms combining analytics, sensors, and control systems are winning on operational efficiency and remote O&M models. Recent strategic transactions have married membranes, analytics, and recurring service models, reshaping competitive dynamics.
- Modular & decentralized vendors (e.g., Fluence, Kubota): These players address the growing market segment for compact, rapid-deployment reuse systems — attractive to emerging markets, campuses, and industrial sites seeking reduced permitting complexity and faster paybacks.
Overall, market dynamics favor partnerships: membrane and chemical innovators paired with digital operators and established EPCs create the combinations that win larger, more complex contracts. While top-tier firms command recognizable strengths, the market remains sufficiently fragmented to enable mid-sized specialists and agile new entrants to scale quickly via regional focus, vertical specialization, or technology differentiation.
Recent Industry Developments That Matter for 2026 Strategy
- Strategic M&A continues to reshape capabilities: transactions that integrate membranes, analytics, and service networks accelerate the shift to bundled offerings and longer contract terms.
- Large-scale municipal reuse programs are progressing from planning to permitting and construction, creating multi-year procurement windows for suppliers and financiers.
- Industrial projects — from heavy manufacturing to energy sectors — are moving from pilot to commercial stages as operators prioritize water security and regulatory compliance.
- Standards and codes are converging toward clearer testing and certification regimes for onsite and decentralized reuse systems, reducing market friction for certified solutions.
Strategic Takeaways for Corporates, Utilities, and Investors
- Prioritize optionality in 2026 capital plans: Given the market’s double-digit growth trajectory, reserve capital or structured financing for scalable reuse pilots that can be upsized into full-scale projects when permitting and offtake certainty align.
- Use short-term pilots to de-risk long-term contracts: Modular technologies and service contracts allow operations teams to validate performance and water quality pathways before committing to high-capex builds.
- Bundle products with O&M services: Vendors and investors should favor business models that combine hardware, software, and recurring services to capture long-duration value and mitigate technology obsolescence risks.
- Align procurement with regulatory trajectories: Incorporate anticipated changes in reuse policy and standards into procurement clauses, acceptance testing, and escalation pathways to avoid retrofit costs.
- Evaluate M&A as a fast-track to capability: Where time-to-market matters, strategic acquisitions can instantly add membranes, analytics, or regional footprints; the report includes integration checklists to protect deal value.
How PW Consulting Supports Execution
Beyond the report, PW Consulting offers a suite of advisory services designed for boards and operational leaders executing in 2026: bespoke scenario modeling aligned to corporate finance, vendor selection processes and RFP design, transaction due diligence (technical, commercial and contractual), and structured procurement frameworks that accelerate go-live while protecting downside. Our specialists also provide O&M contract templates and performance-based KPIs that convert uncertain projects into bankable assets for sponsors and lenders.
Conclusion — What to Do Next
The water recycling and reuse market now presents a clear strategic inflection: a sizable and accelerating market backed by maturing standards, large public programs, and shifting supplier economics. For companies that move in 2026 with disciplined pilots, intelligently structured contracts, and strategic partnerships, reuse will deliver not only resilience but new revenue streams and operational savings. For those who delay, the cost of entry and competitive headwinds will rise as incumbents lock long-term O&M deals and capture advantaged project pipelines.
PW Consulting’s Water Recycling and Reuse Market report is designed to be the operational handbook for that first mover — providing the data models, scenario analyses, vendor playbooks, and execution templates that corporate and investment leaders need to act confidently in 2026. For access to the segmented demand tables, project-level financials, vendor scorecards, and full forecast datasets, please visit our report page and request the complete research package.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com