

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Utility Monitoring Market to Expand at 14.33% CAGR, Reaching USD 16,155.5 Million by 2032

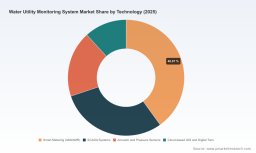
Water Utility Monitoring System Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As water utilities worldwide accelerate digital transformation, PW Consulting’s latest market research — anchored on a 2025 base-year assessment and a 2026–2032 forecast window — delivers the strategic intelligence executives need to make high-consequence decisions in 2026. Our model shows the global water utility monitoring system market expanding at a compound annual growth rate (CAGR) of 14.33% through 2032, reflecting a multi-year lift from the historical period we analyzed (2020–2025). Over that horizon, the market moves from an established multi-billion-dollar base in the mid-2020s toward a materially larger opportunity by 2032. This brief highlights why the report is essential reading for utility CIOs, infrastructure investors, technology OEMs, and procurement leaders preparing budgets, partnerships, and deployment roadmaps next year.
Water Utility Monitoring System Market
Why 2026 Is a Pivot Year
Three converging trends make 2026 a pivotal planning year: an acceleration of AMI/AMI-adjacent deployments, stronger regulatory focus on critical infrastructure cybersecurity, and the urgent capital-replacement cycle driven by aging networks and non-revenue water realities. Utilities that lock in vendor partnerships, data architectures, and procurement strategies in 2026 will be positioned to capture outsized operational and financial benefits across the 2026–2032 forecast window.
Water Utility Monitoring System Market
-
Technology adoption momentum: Smart metering, sensor networks, and cloud-based analytics are moving from pilot to production at scale. Expect 2026 procurement cycles to emphasize interoperability, over-the-air updates, and composable analytics rather than one-off hardware installs.
Water Utility Monitoring System Market -
Cyber and compliance inflection: With SCADA and smart meter networks now explicitly classified as critical infrastructure by regulatory bodies, network segmentation, end-to-end encryption, and continuous monitoring are becoming non-negotiable specifications in RFPs.
-
CapEx re-prioritization: The magnitude of infrastructure renewal requirements — and the persistent drag of non-revenue water — is forcing utilities to triangulate investments that deliver immediate leakage and metering ROI while embedding long-term digital capabilities.
Macro Market Trajectory — What the Numbers Mean for Strategy
PW Consulting’s topline model captures the transition from an early-deployment phase into a rapid commercial expansion. Using our base year of 2025, the market exhibits robust year-on-year scale-up consistent with the 14.33% CAGR through 2032. For executives, that trajectory signals two strategic realities: first, the supplier landscape will continue consolidating around software and systems capabilities (even as hardware remains a substantial component); second, time-to-market and deployment velocity will be critical competitive differentiators.
Our concentration analysis indicates a market that is neither monopolized nor fully fragmented. The three- and five-firm concentration ratios (CR3 and CR5) show meaningful incumbent strength while leaving room for niche innovators and regional specialists to capture share through differentiated offerings and service models. This dynamic produces windows for tactical M&A, partnerships, and selective geographic expansion in 2026.
Actionable Report Components — What You Get
PW Consulting’s full report is designed as an operational toolkit, not just an academic forecast. Key deliverables include:
-
Practical market-sizing and forecast models tailored to support multi-year budget scenarios and sensitivity analysis for capex vs. opex funding pathways.
-
Vendor benchmarking and capability heatmaps that score suppliers across metering hardware, communications stacks, analytics maturity, cybersecurity posture, and professional services delivery.
-
Deployment playbooks with phased implementation templates (pilot → scale → operations), rollout timelines, and workforce-impact assessments to manage the labor shift from manual reading to remote monitoring and analytics operations.
-
Regulatory impact assessment mapping emerging cybersecurity and data privacy requirements to procurement contract language and technical acceptance criteria.
-
Total Cost of Ownership (TCO) and ROI tools including leak-reduction, labor-savings, and asset-replacement scenarios to prioritize projects under constrained budgets.
-
Investment prioritization matrix for utilities and private investors to evaluate technology bets, partnership structures, and near-term M&A targets.
-
RFP and procurement templates incorporating cybersecurity checklists, SLAs for data integrity and latency, and modular procurement options for hardware-agnostic analytics deployments.
Competitive Landscape — How to Read Supplier Moves in 2026
The supplier ecosystem blends global industrial giants with specialist metering OEMs and systems integrators. Our strategic assessment of leading vendors highlights where each competitor is likely to compete for 2026 business and which capabilities are table stakes.
-
Metering specialists (Badger Meter, Kamstrup, Diehl Metering, Neptune/Neptune Technology Group): These firms are consolidating hardware leadership through sensor innovation (ultrasonic, acoustic) and closer coupling of mechanical meters with communications modules. Their value proposition in 2026 will be reliability in the field, low-maintenance lifetime costs, and tight integration into AMI/AMI ecosystems.
-
Communications and platform providers (Itron, Sensus/Xylem, Aclara, Landis+Gyr): These vendors are pushing systems-level solutions — AMI/AMR, network management, and cloud-enabled analytics — with a focus on scale deployments and network robustness. Recent projects and regional expansions demonstrate an aggressive push to convert pilots into city- and region-wide rollouts.
-
Water technology and systems integrators (Xylem, Mueller Water Products, Hach/Danaher): These companies combine sensing, digital twins, and domain expertise to target both quality monitoring and distribution optimization. Their advantage is the ability to bundle advanced sensing with service contracts and long-term performance guarantees.
-
Industrial automation and software heavyweights (Siemens, ABB, Schneider Electric): With mature SCADA, AI, and cybersecurity toolsets, these firms are positioning to serve utilities demanding enterprise-grade analytics and hardened control systems. Their 2025–2026 product launches underscore a push to embed AI-driven predictive maintenance and enhanced cyber-resilience into standard offerings.
Notable recent moves underscore competitive dynamics relevant to 2026 planning: a major metering vendor expanded sensing into wastewater environments through acquisition to pursue end-to-end utility monitoring; another supplier launched next-generation smart meters with enhanced cybersecurity and AI diagnostics; and platform providers continued to broaden regional footprint through targeted projects and partnerships. These developments indicate a market where breadth of capability, depth of data services, and proven cybersecurity are decisive procurement filters.
Regulation, Risk, and Operational Noise — Planning for the Unknown
Senior decision-makers must account for several non-market forces shaping procurement and deployment dynamics in 2026:
-
Cybersecurity as procurement criteria: National guidance treating water control systems as critical infrastructure is already changing contract requirements — expect mandatory network segmentation, encrypted comms, and continuous threat detection to be standard.
-
Capital pressure and infrastructure scale: Large capital needs for water and wastewater systems are forcing staged investment strategies; projects that demonstrate rapid payback through non-revenue water reduction or avoided asset failure will rise to the top of capital plans.
-
Telecom and spectrum constraints: In certain markets, local telecommunications regulation affects IoT deployment models (LoRaWAN, NB-IoT), influencing choices between private networks and carrier partnerships.
-
Workforce transitions: The shift from manual meter-reading to continuous remote monitoring reduces certain O&M costs but increases demand for cybersecurity, data engineering, and remote-operations skill sets — a rebalancing that must be budgeted and planned.
How PW Consulting’s Report Enables 2026 Decisions
Utilities and investors reading this brief should consider three concrete uses of the full PW Consulting report during 2026 planning cycles:
-
De-risk procurement timing: Use our phased deployment templates and vendor maturity scores to decide whether to accelerate purchases in 2026 or to consolidate spending while waiting for next-generation modules with embedded cyber controls.
-
Optimize vendor selection: Apply the benchmarking tools to match utility priorities (leak detection, billing accuracy, asset management) against supplier strengths, then negotiate outcome-based contracts supported by our TCO and ROI calculators.
-
Prioritize investments for regulatory compliance: Leverage our regulatory mapping and cybersecurity checklists to ensure RFPs and contracts meet evolving federal and sector guidance — converting compliance requirements into competitive differentiation.
Next Steps and How to Access Full Intelligence
This executive brief is a strategic preview: it reveals the market direction, key competitive dynamics, practical deliverables, and regulatory considerations that should shape 2026 decisions. For detailed, actionable intelligence — including the full financial model, vendor scorecards, and downloadable procurement templates — PW Consulting’s full report provides the indispensible granularity procurement teams need. Detailed regional and application-level splits, proprietary vendor scoring matrices, and scenario-modeled TCO outputs are reserved for subscribers and purchasers of the report.
In a market growing at double-digit CAGR and transforming how utilities operate and secure critical infrastructure, timely intelligence is the difference between a tactical purchase and a strategic program. PW Consulting’s Water Utility Monitoring System Market report is built for decision-makers who must translate market momentum into resilient, scalable, and secure investments in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Water Utility Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com