

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dried Fruit Ingredients Market to Expand at a 5.45% CAGR Through 2032, Report Says

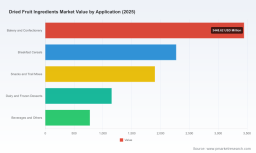
Dried Fruit Ingredients Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As food manufacturers recalibrate portfolios toward clean-label, plant-forward, and convenience-driven products, dried fruit ingredients have moved from commodity inputs to strategic levers for innovation and margin. PW Consulting’s latest market study — base year 2025, forecast through 2032 — shows the global dried fruit ingredients market reached approximately USD 9,547 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 horizon, approaching an estimated USD 13,842 million by 2032. For leadership teams setting 2026 plans, this report functions as both a playbook and an early-warning system: it quantifies near-term opportunity while exposing structural risks that can erode value if left unmanaged.
Dried Fruit Ingredients Market
Why this matters for 2026 decision-making
-
Portfolio strategy: Dried fruit ingredients are no longer interchangeable commodities. Premiumization, reduced-sugar formulations and functional positioning (fiber, natural antioxidants) create distinct margin pools. Manufacturers need forward-looking demand signals to prioritize SKUs and R&D investments.
Dried Fruit Ingredients Market -
Supply-chain resilience: Climatic variability, concentrated growing regions and periodic yield shocks create procurement risk that directly impacts cost and service levels. Tactical sourcing and supplier diversification will be essential to stabilize 2026 production plans.
Dried Fruit Ingredients Market -
Regulatory and label-driven reformulation: Continued regulatory focus on added sugars and front-of-pack disclosures reshapes product formulation choices. Regulatory-readiness must feed into product roadmaps and commercial claims ahead of 2026 launches.
-
M&A and partnership prioritization: With innovation accelerating, acquiring dehydration technologies, private-label capabilities or targeted grower relationships may accelerate time-to-market and protect supply.
Key market dynamics highlighted in the PW Consulting study
-
Demand drivers: Convenience snacking, clean-label ingredient demand, and cross-category penetration (bakery, cereal, bars, dairy inclusions) are underpinning steady volumetric growth. Manufacturers are leveraging dried fruits for texture and natural sweetness while seeking reduced-sugar pathways.
-
Supply-side constraints: Weather-induced variability in key production regions and shifting grower economics raise the premium on secure, traceable supply chains. Our scenario work illustrates how a single poor harvest cycle can ripple through costs and availability for up to 18 months.
-
Structural competition: The market displays meaningful fragmentation: a diversified set of specialty processors, grower cooperatives and branded incumbents each compete on quality, form factor (diced, pureed, infused) and technical service. This creates opportunities for differentiation — and for consolidation.
-
Regulatory and trade pressures: Ongoing label modernization and trade actions require active compliance and tariff strategy. Food-safety events and recalls, while infrequent, have outsized reputational and commercial consequences; traceability investments materially reduce this risk.
What the report delivers — operational, commercial, and strategic tools
-
Granular market model (2020–2032) with year-by-year sizing and a bottom-up forecasting engine: scenario settings allow users to stress-test demand and supply shocks, and to project margin outcomes under different pricing regimes.
-
Segmentation architecture by region, fruit type and application — with strategic implications and adoption curves for each cluster. (Note: detailed segmentation tables and downloadable datasets are available in the full report portal.)
-
Supply-chain heatmap and sourcing-risk matrix: evaluates concentration risk, seasonal exposure, and cold-chain complexity for core fruit types and processing forms.
-
Commercial playbooks: negotiation levers for long-term contracting, indexation mechanisms tied to raw-material benchmarks, and sample term sheets tailored for buyers and co-manufacturers.
-
Innovation tracker and technology radar: captures dehydration methods, low-moisture blending techniques, sugar-reduction platforms and packaging innovations that materially affect shelf life and sensory performance.
-
Regulatory matrix and recall-response protocols: compliance timelines, label-risk checklists and an incident escalation framework to protect brand equity.
-
Competitive landscaping and company dossiers: strategic profiles, capability maps and risk/strength assessments of the major suppliers operating in the sector.
Competitive landscape — what the leading suppliers reveal about market direction
PW Consulting’s fieldwork and primary interviews with processors, growers and food manufacturers show a pattern of specialization and capability-led competition among industry participants. Several themes emerge when evaluating the core players:
-
Product-form differentiation: Suppliers that can deliver bespoke textures and controlled moisture — whether through low-moisture diced blends or advanced purees — command a technical premium. Recent trade-show activity has highlighted new low-moisture blends designed for minimal impact on final-product water activity, extending shelf life and simplifying bakery integration.
-
Premiumization and brand-led supply: Established cooperatives and branded processors continue to defend value through quality claims, traceability and supply assurance channels. This is particularly evident where companies position dried fruit as a “premium natural inclusion” for yogurt, cereals and upmarket baked goods.
-
Operational and food-safety focus: Certification updates and new product launches illustrate two parallel priorities — expanding product portfolios while tightening food-safety and traceability systems. Conversely, high-impact recalls remain a salient risk that can rapidly reset customer contracts and procurement behavior.
Examples from recent market activity reinforce these themes: suppliers demonstrating innovation at trade expos, launches of specialized prune and diced fruit ingredient lines, and certification or compliance upgrades. Parallelly, high-profile recalls in the space underscore the need for rigorous supplier audits and enhanced sampling protocols.
Strategic implications and recommended actions for 2026
-
Buyers: Implement multi-sourcing strategies and include agricultural hedge clauses in supplier contracts to manage raw-material volatility. Fast-track validation of alternative fruit forms that achieve sensory parity but reduce supply risk.
-
Ingredient suppliers: Invest selectively in low-moisture processing and value-added blends to differentiate on technical performance, not just raw commodity price. Document traceability and co-develop label-first formulations with major customers.
-
Retailers and brands: Reassess private-label sourcing economics versus brand partnerships. Prioritize suppliers that can support reduced-sugar narratives and provide verified origin claims.
-
Investors and M&A teams: Look for bolt-on targets that provide access to dehydration technology, packaging innovations or direct-farm relationships to secure margins and improve working capital dynamics.
How PW Consulting’s work supports 2026 execution
This report is designed for immediate operational use by procurement, innovation and corporate strategy teams. Key deliverables intended to accelerate action in 2026 include:
-
An interactive Excel model enabling rapid scenario runs (price shocks, tariff changes, yield shortfalls) with P&L and margin outputs.
-
A supplier scorecard and audit checklist that reduces audit cycle time and frames corrective-action plans for high-risk suppliers.
-
Concrete negotiation templates and indexation formulations to align supplier incentives with buyer risk tolerances.
-
Go-to-market and product-development recommendations prioritized by expected margin uplift and time-to-market.
What is deliberately withheld in this preview — and why
Consistent with the “trailer” approach, this preview demonstrates the directional insights and the strategic utility of the full study while intentionally withholding the granular segment-level tables, regional breakout percentages, and the full set of price curves that form the operational core of supplier negotiations and M&A valuations. Those datasets — including downloadable tables, sensitivity dashboards and the full competitive scorecards — are available through the PW Consulting report portal for licensed clients and subscribers.
Final note — immediate priorities for executives
For 2026, executives should prioritize three pragmatic actions informed by the report’s findings: (1) codify supply resilience through diversified contracting and scenario-based inventory plans; (2) accelerate qualification of value-added product forms that enable reduced-sugar and clean-label claims; and (3) implement enhanced traceability and recall-prevention measures that protect brand equity. The market’s projected steady growth creates opportunity, but the path to winning is increasingly technical and operational — not just commercial.
PW Consulting’s full Dried Fruit Ingredients Market report supplies the market-sizing, segmentation detail, supplier intelligence and executable playbooks required to convert this growth into durable commercial advantage. For access to the complete report, interactive datasets and bespoke advisory engagements, please visit our website or contact PW Consulting’s insights team.
For detailed analysis of this topic, please visit the official page: Dried Fruit Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com