

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Paid Micro Short Drama Market Reaches USD 1,250 Million in 2025, Poised to Grow at a 22.45% CAGR Through 2032

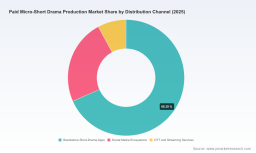
Paid Micro Short Drama Production Market: Strategic Outlook for 2026 — PW Consulting Insights
PW Consulting’s new Paid Micro Short Drama Production Market report (base year 2025; forecast period 2026–2032) arrives at a turning point for content strategy and production economics. Our analysis quantifies a market that expanded rapidly through 2020–2025 and is projected to grow at a robust compound annual growth rate (CAGR) of 22.45% across the 2026–2032 forecast window. From an industry value measured in the low hundreds of millions in 2020, the ecosystem exceeded one billion USD by 2025 and is forecast to reach multiple billions by the early 2030s. For decision-makers planning 2026 budgets and strategic initiatives, this trajectory reframes every investment question — from greenlighting slates to selecting production partners and monetization stacks.
Paid Micro Short Drama Production Market
Why this report matters for 2026 decisions
-
Timing: The market has reached commercial scale. Where previously micro-short drama was experimental or promotional, 2025 marked the inflection where dedicated paid channels, vertical-first formats, and coin/subscription mechanisms became repeatable revenue engines. 2026 is the first full planning year where firms can confidently allocate meaningful content CAPEX and expect market-level returns.
Paid Micro Short Drama Production Market -
Cost transformation: Production economics are compressing rapidly due to two forces — compact live-action shoots optimized for vertical formats, and the emergence of AI-native or AI-assisted production workflows. Our report distills how those forces change cost-per-minute and per-episode economics, and what that means for margin-sensitive business models.
Paid Micro Short Drama Production Market -
Structural concentration and competition: The market is not winner-take-all. Top players collectively account for a meaningful but not overwhelming share of revenues, creating opportunity for well-capitalized entrants, regional champions, and specialized studios. We quantify concentration metrics and analyze why differentiated IP and distribution partnerships matter more than scale alone.
Key strategic themes executives must confront in 2026
-
Monetization architecture: Paid micro short dramas are monetized through hybrid mechanisms — microtransactions, time-gated subscriptions, and sponsorship integrations. The right combination depends on audience cohort, content genre, and distribution channel economics. Our report provides frameworks to map unit economics to pricing strategies and lifetime-value (LTV) expectations for core customer segments.
-
Production playbooks and total-cost modelling: Production budgets for professional vertical series vary by ambition, but the sector now supports models from lean rapid-shoot titles to premium “S-class” serialized IP. AI-assisted pipelines can reduce certain production costs dramatically; our modelling shows the trade-offs in quality, speed-to-market, and rights ownership that determine where to deploy AI versus traditional crews.
-
Distribution and partnership engineering: Distribution is multi-architectural — from dedicated short-drama apps and social ecosystems to select OTT partnerships and telco bundles. The most successful strategies in 2025–2026 combine platform placement with direct-to-consumer monetization and strategic regional localizers. We map the commercial levers needed to optimize revenue share, promotional support, and discovery economics.
-
IP strategy and localization: Original IP, licensed adaptations, and brand-sponsored custom content each carry different margin profiles and scalability characteristics. Executives must decide whether to build repeatable original franchises, purchase and localize foreign IP, or monetize through bespoke brand storytelling. Our report offers decision matrices for IP investment versus licensing, including valuation heuristics for short-form serialized formats.
-
Regulatory and labor risk management: Regulatory frameworks and guild agreements have adapted to new formats. Authorities in key markets are introducing transparency and labeling rules for AI-generated content, while major talent guilds have established contracts tailored to microdrama budgets. These developments change cost lines and compliance obligations; our compliance checklist and negotiation playbooks prepare legal and production teams for 2026 realities.
What’s inside the report — practical deliverables
-
Executive dashboards and scenario models: Interactive revenue and cost scenarios across multiple monetization mixes, with stress-testing for acquisition costs and retention decay assumptions.
-
Production cost benchmark toolkit: Line-item templates for vertical microdrama shoots, AI-assisted workflows, and hybrid production; break-even and margin levers for different budget bands.
-
Go-to-market playbooks: Channel strategies for apps, social platforms, OTT windows, and telco partnerships; promotional mechanics and subscriber conversion best practices.
-
IP and content strategy frameworks: Decision matrices for original vs. licensed vs. branded formats, with guidance on territorial rights, localization, dubbing/subtitling economics, and franchise development roadmaps.
-
Regulatory and labor compliance modules: Checklists for AI labeling, content review protocols in regulated markets, and contract templates aligned to the microdrama-specific guild agreements.
-
Competitive intelligence and M&A screen: Profiles of leading studios, platform operators, and production hubs; acquisition scoring templates and integration risk assessments.
Competitive landscape — players shaping 2026
The industry now includes platform-focused operators, vertically specialized producers, and emergent AI-native studios. Notable companies captured in our competitive analysis include:
-
Crazy Maple Studio (ReelShort) — A California-based leader with significant backing and a platform-driven model; focuses on vertical episodic content with coin-based unlocks and subscription hybrids tailored for international audiences.
-
Beijing Dianzhong Technology (DramaBox) — A major China-origin platform and producer with demonstrated strength in overseas markets via localized translations, in-app monetization strategies, and distribution synergies with regional partners.
-
Linmon Media — Expanding from established content production into vertical microdrama slates targeting Asian markets; recent slate launches demonstrate how traditional production houses are adapting format and release strategies for short-form serialized IP.
-
AR Asia Productions — A Hong Kong-based studio that leverages platform and telco partnerships for content delivery across multiple Asian territories and genres, experimenting with bundled distribution models.
-
Vigloo (SpoonLabs) — A Seoul headquartered studio at the vanguard of AI-assisted production, releasing fully AI-native titles in compressed timelines to test English-language and global audiences.
-
Holywater (MyDrama/MyMuse) — A European-based outfit producing Hollywood-caliber microdramas with strategic investment ties and a focus on premium vertical storytelling for international paid platforms.
These companies illustrate three sustainable competitive approaches: platform-anchored ecosystems that control discovery and payments; studio-driven IP owners focusing on franchise value and licensing; and technology-first entrants that compress production cycles and cost bases through AI. Our concentration analysis quantifies that the top-three participants capture a material portion of market revenue while the top-five broaden that footprint — a structure that supports both consolidation and continued niche-entry opportunities.
Recent developments shaping the 2026 playbook
-
Slate launches and regional expansion: Established studios are converting proven long-form IP strategies into microdrama slates geared to regional consumption windows and mobile-first viewing patterns.
-
AI-native releases: Fully AI-produced titles are commercially viable experiments that demonstrate dramatically compressed production cycles; such releases are reshaping content timelines and unit economics.
-
Production infrastructure scaling: Government-backed and private AI-assisted production hubs are enabling thousands of micro-production teams to access tooling and standardized pipelines — accelerating output but also increasing supply-side competition.
-
Regulatory and guild alignment: New labeling requirements for AI-generated content and microdrama-specific talent agreements have created operational constraints and protections that buyers and studios must incorporate into budgets and contracts.
Five recommended moves for 2026
-
Run controlled experiments on monetization hybrids. Test microtransaction-first titles alongside timed subscription windows to identify highest LTV cohorts before large-scale rollouts.
-
Invest selectively in AI-assisted tooling but protect premium IP. Use AI to lower marginal production costs on high-volume slates, while reserving higher-budget human-centric shoots for flagship franchises.
-
Secure distribution partnerships that combine discovery and revenue share. Favor partners offering marketing levers and cross-border promotion rather than pure hosting.
-
Integrate compliance and guild negotiation into pre-production. Treat labeling, content review, and talent contracts as strategic line items that influence scheduling, costs, and release tactics.
-
Adopt an acquisition pipeline for tech and IP. Prioritize targets that enhance production velocity, localization capability, or proprietary audience analytics rather than raw content libraries alone.
How PW Consulting can accelerate your 2026 agenda
Our report is designed as an operational toolkit for executives: from CFOs building content budgets to CMOs optimizing acquisition spend, and from studio heads evaluating production models to corporate development teams screening M&A. The report’s datasets, scenario models, and playbooks translate market-level growth forecasts into executable strategies for 2026 decision cycles.
Note on proprietary detail: This article highlights the report’s major findings and strategic implications but intentionally omits granular segment tables and regional splits to encourage direct engagement with the full dataset and accompanying Excel models. Those detailed segment-level breakouts, company-level revenue estimates, and modelable outputs are available on the report’s source page for subscribers and enterprise clients.
For a copy of the full Paid Micro Short Drama Production Market report, including interactive financial models, company scorecards, and the complete segmentation breakdown used to inform 2026 planning, visit our official report page or contact PW Consulting’s industry desk for a briefing.
For detailed analysis of this topic, please visit the official page: Paid Micro Short Drama Production Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com