

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Automotive Ethernet Market to Reach USD 15.7B by 2032, Growing at a 19.52% CAGR

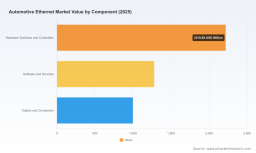
Automotive Ethernet Market: Strategic Imperatives for 2026 — PW Consulting Releases New Industry Report
Executive Summary
As vehicles evolve into software-defined platforms, the shift to high-bandwidth, deterministic in-vehicle networking has accelerated. Our new Automotive Ethernet Market report positions industry leaders, OEMs, Tier‑1 suppliers and investors to make decisive, risk-calibrated choices in 2026. The report documents a clear inflection: market value expanded from roughly USD 1.5 billion in 2020 to USD 4.5 billion in 2025 and is forecast to continue growing at a compound annual growth rate (CAGR) of 19.52% over the 2026–2032 window. By 2026 the market is projected to exceed USD 5.4 billion, with multi‑gigabit and zonal architectures driving the next wave of demand through 2032.
Automotive Ethernet Market
Why this report matters for 2026 decision-makers
-
Timing matters. The convergence of advanced driver assistance systems (ADAS), centralized compute, and zonal architectures turns 2026 into a pivotal procurement and architecture year for automotive programs launching in the 2028–2030 model cycles.
Automotive Ethernet Market -
Risk vs. reward. High bandwidth Ethernet variants (from 100BASE‑T1 up to emerging 10GBASE‑T1 implementations) offer dramatic system simplifications and performance gains but introduce new design, EMC and cybersecurity trade‑offs. Our modeling quantifies these trade‑offs in ways that support contract negotiations and supplier selection.
Automotive Ethernet Market -
Regulatory compliance is non‑negotiable. With UN ECE R155 and international cybersecurity requirements in force, Ethernet architecture decisions are inseparable from compliance roadmaps — affecting certification timelines and supplier obligations. The report embeds a regulatory impact matrix linked to adoption scenarios.
What’s inside — actionable elements of the report
-
Proprietary market model and scenario layers: A base forecast (2026–2032) plus three alternate scenarios that stress-test adoption pathways for zonal ECUs, centralized compute, and high‑bandwidth ADAS domains. The model is delivered with a modifiable spreadsheet and sensitivity knobs for component pricing, design-in lead times, and node‑level bandwidth assumptions.
-
Supplier scorecards: Comparative assessments of PHY, switch and software providers across technological maturity, product roadmap clarity, supply chain resilience, and compliance posture. Scorecards are designed to inform shortlist creation for RfPs and strategic partnerships.
-
Technology readiness and integration playbooks: Practical guidance on PHY selection, multi‑drop vs. point‑to‑point tradeoffs, EMC mitigation for unshielded twisted pair deployments, and deterministic networking strategies for real‑time domains. Each playbook includes recommended test protocols and acceptance criteria aligned with ISO and OPEN Alliance standards.
-
TCO and lifecycle models: Total cost of ownership frameworks that capture up‑front hardware delta, wiring harness simplification gains, software migration costs, and long‑term support exposures for security and functional updates.
-
Compliance & certification checklists: Step-by-step preparation plans for UN ECE R155 and ISO 10681 interplay, including cybersecurity evidence packages and integration milestones that influence type‑approval timelines.
-
Market entry and M&A playbook for investors: Identification of capability gaps, supplier consolidation signals, and valuation levers for targets in PHY IP, switch silicon, and validation toolchains.
Competitive landscape — who matters and why
The market exhibits meaningful concentration: the top three firms account for roughly 45.2% of relevant market turnover, and the top five capture about 60.8%. This structure produces a bifurcated competitive dynamic — a high barrier-to-entry silicon and IP tier, and a vibrant ecosystem of tool, test and integration vendors supporting rapid adoption.
-
Broadcom Inc. — Positioned as a silicon leader with BroadR‑Reach and multi‑Gb PHY/switch portfolios. Certification progress on high‑speed Ethernet standards strengthens Broadcom’s relevance for vehicle programs that prioritize margin and integration density.
-
Marvell Technology, Inc. — Marvell’s push into 10GBASE‑T1 and demonstrable vehicle integrations highlight its strategy to capture bandwidth‑intensive ADAS and centralized compute use cases. Integration wins with OEM platforms serve as a template for market penetration.
-
NXP Semiconductors — NXP is notable for marrying PHY and MAC capabilities with its broader MCU/SoC portfolio. Recent switch launches targeted at zonal architectures underscore NXP’s play to lock down domain controller and gateway positions.
-
Texas Instruments — A consistent value player with cost‑optimized PHYs, attractive for high‑volume mid‑tier programs where price and proven supply chains matter most.
-
Microchip Technology — Focused on gateway and domain controller components, Microchip’s offerings are frequently selected in designs where integration and extended temperature support are priorities.
-
Analog Devices — ADI’s portfolio targets niche long‑reach and sensor network applications, leveraging differentiated analog and mixed‑signal expertise for 10BASE‑T1L deployments.
-
Renesas Electronics — With SoC integrations aimed at high‑bandwidth automotive compute, Renesas’ partnerships with Tier‑1s and automotive suppliers seek to accelerate centralized architectures.
-
TTTech Auto — A specialist in deterministic Ethernet and motion‑control networks; TTTech’s real‑time software and switch products appeal to safety‑critical domains and software‑defined vehicle architectures.
-
Vector Informatik — A dominant test, validation and ECU development provider; Vector’s tools remain essential for development process integration and compliance testing.
-
Intrepid Control Systems — Offers diagnostics and connectivity tools optimized for evolving PHY standards; valuable to OEMs and labs managing multi‑protocol testbeds.
Recent strategic moves to watch (selected highlights)
-
Marvell reported production integration of 10GBASE‑T1 PHYs into a major OEM platform in mid‑2025, a milestone that materially de‑risks multi‑gigabit deployments for ADAS.
-
Broadcom achieved key OPEN Alliance compliance for higher‑speed PHY families in late 2025, accelerating qualification cycles for vendors seeking 10Gb solutions.
-
NXP launched a dedicated automotive Ethernet switch in late 2025 aimed at zonal architectures, signaling a defensive move to maintain SoC‑adjacency in vehicle platforms.
-
Renesas’ collaboration with Tier‑1s on 10GBASE‑T1 for next‑generation ECUs underlines the industry’s push to consolidate compute and I/O stacks around standardized Ethernet backbones.
-
TTTech Auto’s public demonstrations of deterministic 10Gb switching underscore the growing need for real‑time guarantees in safety‑relevant, software‑defined vehicle domains.
Standards, bottlenecks and regulatory headwinds
-
Standards momentum: ISO 10681 defines requirements for PHYs up to 10 Gbps while OPEN Alliance workstreams (including TC8 and TC10) continue to shape multi‑drop and multi‑gigabit interoperability. These standards are catalysts — they lower integration friction but raise qualification costs.
-
Technology bottlenecks: High‑speed PHYs (e.g., 1000BASE‑T1 and beyond) impose demanding signal‑processing requirements to mitigate EMI over unshielded cabling. Design teams should budget additional validation cycles and testbed complexity into development plans.
-
Regulatory requirements: UN ECE R155 and related cybersecurity mandates have turned functional architecture decisions into compliance decisions; non‑compliant design paths can trigger protracted rework and delayed type approvals.
-
Safety constraints and power over data: In certain PHY classes, PoDL is effectively excluded due to isolation and ISO 26262 safety constraints — a nuance that affects sensor node power strategies and harness planning.
Strategic recommendations for stakeholders in 2026
-
OEMs: Adopt a phased Ethernet migration roadmap that aligns program milestones with supplier qualification timelines. Prioritize vendor diversity for critical silicon while negotiating long‑term supply agreements to mitigate lead‑time risks.
-
Tier‑1 suppliers: Invest in integration teams with deep PHY, EMC and cybersecurity expertise. Build repeatable zoning architectures and modular domain controllers to accelerate design reuse across programs.
-
Semiconductor vendors: Differentiate on software stacks and deterministic networking features, not only on PHY performance. Prove compliance through third‑party certifications and publish integration guides tailored to automotive toolchains.
-
Investors and M&A teams: Target companies that close capability gaps in test & validation, deterministic switch software, and long‑reach PHYs — assets that unlock acceleration of high‑bandwidth adoption.
-
Compliance teams: Treat cybersecurity and regulatory evidence as program long‑lead items. Embed UN ECE R155 milestones in program reviews and acceptance criteria for new suppliers.
How PW Consulting’s report supports execution
This report is built to be immediately operational: modifiable financial models, supplier scorecards, test regimes and compliance checklists are all included to shorten decision cycles. For procurement teams, the report provides negotiation levers grounded in supplier concentration metrics and TCO scenarios; for system architects, it supplies validated playbooks to manage EMC, deterministic networking and security trade‑offs.
Next steps — where to get the full intelligence
The analysis above is a strategic preview. For program‑level granularity — including the full set of scenario spreadsheets, supplier scorecards, detailed technology adoption timelines and the regional‑application matrices — visit the PW Consulting Automotive Ethernet Market report page. Our subscribers gain access to downloadable models, extended data appendices and a dedicated analyst Q&A session designed to accelerate program decision‑making for 2026 launches.
PW Consulting remains committed to translating complex technical, regulatory and commercial dynamics into executable strategy. For boards, product leaders and investors planning for the mid‑cycle inflection, the choices made in 2026 will materially shape competitive position across the 2028–2032 vehicle generations.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com