

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rechargeable Handheld Metal Detector Market Set to Grow at a 6.25% CAGR, Driving Industry Momentum

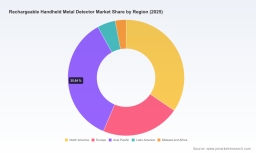
Rechargeable Handheld Metal Detector Market: Strategic Preview for 2026 Decision-Makers
Executive Snapshot
PW Consulting’s new market study on Rechargeable Handheld Metal Detectors (base year 2025, forecast 2026–2032) quantifies a market transitioning from steady, procurement-driven demand into a phase of technology-led replacement and higher-value specification. Our analysis pegs the global market at approximately USD 240.5 Million in 2025, with a near-term uptick to about USD 261.0 Million in 2026 and a compound annual growth rate (CAGR) of 6.25% across the 2026–2032 forecast window, reaching the mid-hundreds by 2032. These headline metrics set the stage for executive decisions on product roadmaps, vendor selection, and operational investments in FY-2026 and beyond.
Rechargeable Handheld Metal Detector Market
Why this report matters for 2026 strategy
-
Procurement clarity: As public security budgets reallocate toward value-per-touch technologies, procurement teams must balance unit cost vs. lifetime operational value (battery life, calibration needs, serviceability). Our report translates market growth into realistic procurement volumes and replacement cycles that will inform 2026 CAPEX planning.
Rechargeable Handheld Metal Detector Market -
Technology differentiation: The marketplace is shifting from commodity wands to differentiated rechargeable models that emphasize battery chemistry, ergonomics, waterproofing, and regulatory compliance. The report identifies which features materially affect adoption and total cost of ownership.
Rechargeable Handheld Metal Detector Market -
Competitive posture: Suppliers and buyers alike need a compact view of market concentration and the innovation vectors of tier‑one and fast‑growing OEMs to prioritize partnerships, certification efforts, and distribution strategies.
What the full report delivers (practical, actionable content)
-
Validated market sizing and forecasting: A transparent methodology covering historicals (2020–2025), 2026 base recalibration, and scenario-based projections to 2032 in USD Million—designed to be plug‑and‑play for procurement forecasts and financial models.
-
Buyer decision matrix: Comparative frameworks that map product features (battery life, charging interfaces, sensitivity modes, IP ratings, NIJ compliance) to buyer personas (aviation security, events, law enforcement, industrial loss prevention).
-
Technology and product benchmarks: Side‑by‑side technical scoring (operational hours, charging standards, multi-frequency capability, environmental ruggedness) to support spec sheet decisions without having to reverse engineer vendor claims.
-
Regulatory and standards matrix: A concise treatment of relevant certifications and evolving standards—critical for vendors and purchasers to secure government and airport contracts.
-
Go‑to‑market and service playbooks: Regional channel archetypes, aftersales service models, warranty and battery-replacement economics, and a recommended pricing architecture for 2026 product launches.
-
Supply‑chain risk assessment: Raw‑material exposure (notably lithium‑ion battery supply and USB charging componentry), contract manufacturing patterns, and mitigation strategies for near‑term disruption.
-
Investment and M&A signals: Identifies capability gaps where bolt‑on acquisitions or strategic partnerships yield rapid market access or technological leapfrogging.
Competitive Landscape — who shapes purchasing choices
The market remains a mix of longstanding security-equipment incumbents and specialized OEMs. Leading manufacturers continue to compete on reliability, certification, battery performance, and service networks. Our study profiles the major players and articulates what each brings to procurement tables:
-
Garrett Metal Detectors (Garland, TX): A legacy brand with strong recognition across airports and events. Recent product introductions emphasize USB‑C rechargeable options, enhanced sensitivity tiers, waterproofing, and application‑specific models for law enforcement—moves that protect their installed base while targeting selective upgrades.
-
CEIA (Arezzo, Italy): Known for high‑performance units with compliance to NIJ standards. Their product positioning favors institutional buyers prioritizing certified performance and traceable calibration practices.
-
Securina Detection (Shenzhen): Aggressive on price‑performance, integrating contemporary conveniences (USB‑C charging, vibration alerts) that align with fast replacement cycles in schools and events markets.
-
NUCTECH and Smiths Detection: These larger security-systems firms leverage integrated sales channels (e.g., aviation security suites) and established service contracts to lock in long‑term deployments of rechargeable handhelds alongside other screening technologies.
-
Smaller specialized OEMs (e.g., GXC, Autoclear, Westminster Group partners, Shenzhen Pinpoint, Dongguan Viking): These vendors focus on specific niches—extended battery life, NIJ compliance without calibration, or compact designs for constrained checkpoints—making them attractive for targeted procurement strategies.
Notably, product announcements through 2025–early‑2026 reflect two converging dynamics: (1) manufacturers are standardizing around lithium‑ion chemistries and USB‑C charging for usability and logistical simplicity; and (2) vendors pursue NIJ-aligned certification paths and ruggedized designs to win institutional contracts. These themes are documented and benchmarked in the report.
Market dynamics and risk factors shaping 2026 choices
-
Demand drivers: Rising public security concerns and evolving threat models continue to prop demand from transportation hubs, venues, and public institutions. Buyers are moving away from disposable battery models toward rechargeable devices with predictable lifecycle costs.
-
Standards and certification: Compliance to NIJ test standards and their updates is increasingly a procurement precondition. Buyers should prioritize certified units or those with clear certification roadmaps to avoid retrofit costs or lost tenders.
-
Battery supply and end‑of‑life management: Lithium‑ion battery sourcing and lifecycle handling (including safe disposal and swap programs) are operational issues that will affect TCO and regulatory compliance, especially in jurisdictions strengthening e‑waste rules.
-
Channel and service economics: Warranty terms, replacement battery availability, and local servicing partners materially affect long‑term cost and uptime. The report models service scenarios to guide vendor selection.
Actionable recommendations for 2026
-
Procurement strategy — adopt a total cost of ownership lens: For 2026 purchases, specify battery‑life minima, certified sensitivity thresholds, and charger standardization (USB‑C) to reduce logistics complexity and operating costs.
-
Certification hedge — require roadmaps: Where immediate NIJ certification is not mandatory, require vendors to commit to certification milestones within contract timelines to protect compliance risk.
-
Modular product requirements — favor upgradeability: Define contracts that allow firmware updates, replaceable batteries, and accessory options to extend device lifecycles and reduce waste.
-
Service and spares — price and contract: Negotiate multi‑year service agreements that include battery replacement bundles and local spares to avoid downtime during peak events.
-
Strategic sourcing — diversify supplier mix: Combine established incumbents for mission‑critical deployments with regional OEMs for volume or price‑sensitive use cases; use short pilot programs to validate performance before scale procurement.
-
M&A and partnerships — pursue capability fills: For vendors seeking growth in 2026, consider acquiring battery‑management expertise, local service networks, or software analytics providers to productize value‑added services (e.g., device health telemetry).
How to use this research in your 2026 planning
Operational leaders should use the report as the basis for three linked workstreams: capital planning (buy vs. lease decisions tied to projected device lifecycles), standards compliance (alignment to NIJ and local regulatory regimes), and supplier performance contracting (service level agreements tied to device uptime and battery replacement cadence). Procurement teams can directly extract forecasted demand profiles and scenario outputs to populate annual budgets, while product teams can prioritize feature investments with direct evidence of buyer willingness to pay.
Next steps and access to the full intelligence
This article highlights core findings and strategic implications; detailed sub‑segment data, regional demand matrices, vendor scorecards, and full pricing and service models are intentionally reserved for the full PW Consulting report to preserve the tactical value of the primary research. For procurement leaders, technology strategists, and investors preparing for 2026, the complete study provides the requisite granularity—down to buyer personas, channel economics, and a tactical procurement checklist.
To obtain the comprehensive dataset, vendor scorecards, and the 2026 tactical playbook, please refer to the full Rechargeable Handheld Metal Detector Market report available from PW Consulting.
For detailed analysis of this topic, please visit the official page: Rechargeable Handheld Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com