

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Aircraft Brake Calipers Market to Rise from USD 592.28 Million in 2025 to USD 1,022.99 Million by 2032 at an 8.12% CAGR
By pmarketresearch, 2026-07-15
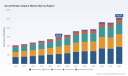
Worldwide Aircraft Brake Calipers Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As aviation stakeholders prepare for a pivotal planning cycle in 2026, PW Consulting’s latest market study on the Worldwide Aircraft Brake Calipers Market offers a concise, decision-focused intelligence package. Grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study documents a market that expanded from approximately USD 412.5 million in 2020 to USD 592.3 million in 2025. Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of 8.12% through 2032, reaching roughly USD 1,023.0 million by the end of the forecast period. This briefing highlights the implications of those dynamics for strategic planning, while directing experienced readers to the full report for granular segment and competitive tables reserved for subscribers.
Worldwide Aircraft Brake Calipers Market
Why this matters for 2026 strategic planning
-
Recovering traffic profiles, fleet modernisation and renewed aftermarket activity are shifting capital and service priorities across OEMs, MROs and component suppliers. The pace implied by an ~8.1% CAGR demands active portfolio and capacity decisions in the next 12–18 months.
Worldwide Aircraft Brake Calipers Market -
Concentration is meaningful: the market shows a high degree of vendor clustering at the top (three-firm and five-firm concentration measures indicate a consolidated competitive landscape). That concentration alters bargaining dynamics, M&A calculus and aftermarket capture strategies.
Worldwide Aircraft Brake Calipers Market -
Certification and materials choices (lightweight aluminium/titanium architectures versus carbon-ceramic high-performance options) are becoming strategic differentiators rather than purely engineering decisions — with direct bearings on product roadmaps, supplier selection and total life-cycle cost models.
Core demand drivers and near-term constraints
-
Fleet growth and replacement cycles: Airlines renewing narrow- and wide-body fleets and military platforms modernising braking systems are primary demand sources. As operators prioritise fuel-efficiency and weight reduction, caliper design trade-offs influence procurement specifications.
-
Aftermarket and MRO tailwinds: Increased utilisation and a stretched supply chain elevates demand for component repairs, FAA-PMA replacements and aftermarket-certified caliper parts. The market’s aftermarket segment represents a strategic margin pool for firms that can secure OEM approvals or strong distribution partnerships.
-
Regulatory & certification complexity: FAA advisory circulars and technical standard orders remain binding constraints that shape product development timetables and testing budgets. Regulatory compliance for rejected takeoff (RTO) and landing performance is a gating item that directly affects time-to-revenue for new caliper designs.
-
Material and supply-chain volatility: Titanium and carbon-ceramic composites offer performance upside but come with supply, cost and manufacturing complexity. Aluminium alloys still dominate where balance of cost, weight and manufacturability matter.
Technology, materials and the electrification vector
Three technology threads are set to re-shape competitive advantage through 2032. First, material engineering — the selective use of titanium and carbon-ceramic composites — enables higher thermal tolerance and lower life-cycle weight but requires investments in process control and supplier relationships. Second, actuation systems are evolving: while hydraulic calipers remain the incumbent workhorse, electric brake actuation architectures are gaining attention for integrated brake-by-wire functionality and potential maintenance advantages on next-generation platforms. Third, digital enablement — sensorised calipers, prognostics and integrated health-management — is emerging as a service enabler for MROs and fleet operators seeking to reduce unscheduled removals and extend component intervals.
Regulatory and certification landscape
-
FAA AC 25.735-1 and related airworthiness guidance continue to frame dynamic testing and wear-limit regimes used in certification programs. Familiarity with these advisory circulars and their interpretation is table stakes for entering transport-category platforms.
-
TSO-C26d establishes minimum performance and dynamic test protocols for transport wheels and brakes. Suppliers targeting large commercial platforms should factor the cost and schedule impact of dynamic testing into 2026 development budgets.
Competitive landscape — who matters and why
The market is shaped by a mix of global OEM-tier incumbents and specialist niche players. Leading landing and brake systems integrators, multi-national aerospace suppliers, and specialised general aviation manufacturers each play distinct roles across OEM sales, aftermarket spares and MRO channels.
-
Safran Landing Systems (France) — Positioned as a global leader in integrated landing and braking systems for large commercial platforms. Its portfolio breadth (complete wheels-and-brakes systems) and programme level relationships with large OEMs give it strategic leverage on both new-build and aftersales capture.
-
Meggitt Aircraft Braking Systems / Parker Meggitt (UK/USA) — Strong in business, regional and military segments, with an installed-base focus and vertical capability through component subsidiaries. Their depth in both products and repair networks supports resilient aftermarket revenue.
-
Collins Aerospace (RTX Corporation) and Honeywell Aerospace (USA) — Major diversified aerospace suppliers with cross-platform reach. They combine product engineering, integration experience and OEM relationships that make them natural partners for platform-level contracts and integrated actuation solutions.
-
Tier 2 and specialist players — Cleveland Wheel & Brake Systems, Grove, NMG Aerospace, Nasco and FAA-PMA suppliers — are critical in the general aviation, business-jet and aftermarket replacement ecosystems. Their agility and certification portfolios make them the go-to for MROs and operators seeking rapid turnarounds and approved spares.
-
Smaller OEMs and niche manufacturers (Beringer Aero, MATCO, Jay-Em, Rapco Fleet Support, Aerobrake) continue to serve light aircraft and experimental markets, preserving high-margin niches and enabling platform-specific innovation.
Notably, the market concentration metrics underline that a small number of firms capture the lion’s share of value — an important data point for executives weighing partnership, pricing and defensive M&A options.
Recent developments worth watching
-
April 2026: Cleveland Wheel and Brake Systems was awarded a firm fixed-price purchase order for wheel and brake components — a concrete reminder that government and defence-linked procurement remains a current source of demand and cash flow for component suppliers.
-
Across the supplier community, announcements around electric actuation pilots, sensorised brake trials and supply-chain safeguards are accelerating. These are early indicators of where aftermarket service models and certification investments will concentrate over the next 24 months.
Practical implications and recommended 2026 actions
-
Prioritise product-roadmap triage. Allocate investment to designs that balance near-term certification feasibility with medium-term weight and thermal gains (e.g., selective use of titanium or hybrid material architectures).
-
Define an aftermarket capture plan. For OEMs and distributors, securing maintenance contracts and FAA-PMA approvals can generate high-margin revenue and stabilise order books during new-build cyclicality.
-
De-risk certification paths early. Incorporate FAA advisory circular and TSO testing requirements into programme budget and timeline planning to avoid costly rework and missed contract milestones.
-
Assess M&A and partnership opportunities against concentration dynamics. For mid-tier players, targeted acquisitions or long-term supply agreements with top-tier integrators can accelerate scale and improve bargaining power.
-
Invest in digital prognostics. Brakes-as-a-service pilots and health-management offerings can reduce operator on-wing time and create recurring revenue streams tied to predictive maintenance.
-
Hedge material exposure. Create dual-sourcing strategies for critical alloys and composite inputs to limit price volatility and supply disruptions.
What the PW Consulting report delivers (practical, actionable contents)
The full report is structured to support commercial and technical decision-making. Key deliverables include:
-
Bottom-up market sizing and validated forecast model (2026–2032), with scenario sensitivity and demand drivers by fleet type and actuation architecture.
-
Competitive intelligence dossiers on leading suppliers, including capability maps, go-to-market models, manufacturing footprints and MRO channel analysis.
-
Regulatory and certification playbook summarising test regimes, timeline implications and typical cost buckets for compliance (including guidance tied to FAA AC and TSO requirements).
-
Supply-chain risk matrix and raw-material exposure analysis with mitigation options tailored for procurement and operations leaders.
-
Strategic growth playbook: M&A screening templates, pricing levers, aftermarket commercial models and a 12–36 month implementation roadmap.
-
Proprietary scenario analyses and an interactive financial model to stress-test capital allocation, production scale-up and aftermarket capture strategies.
To preserve the report’s commercial value for subscribing clients, we refrain from reproducing detailed segment-level shares and company-specific revenue figures in this release. The full dataset and downloadable models are accessible on the report landing page.
How to use this intelligence in 90 days
-
30 days — Rapid internal alignment: Share the executive brief with product, procurement and commercial leads and map current programs against certification timelines highlighted in the report.
-
60 days — Tactical decisions: Finalise supplier hedging arrangements for critical materials, and prioritise a single pilot for digital prognostics or electric-actuation integration.
-
90 days — Strategic actions: Execute an M&A screening or partnership outreach to close capability gaps identified in the competitive intelligence dossiers.
Next steps
For procurement leaders, OEM product strategists, private equity investors and MRO executives preparing budgets and bids in 2026, the full PW Consulting report provides the granular segmentation, competitor revenue breakouts and downloadable forecast model necessary to convert insight into action. Access to the complete dataset and bespoke advisory support is available via the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Off‑Highway Wheels Market to Grow at 5.6% CAGR, Reaching USD 12,306.15 Million by 2032 — Asia Pacific Leads with USD 3,361.51M
By pmarketresearch, 2026-07-15
Worldwide Off-highway Wheels Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s newest market study—Worldwide Off-highway Wheels Market Intelligence, base year 2025—arrives at a pivotal moment for manufacturers, OEMs, suppliers and investors shaping heavy-equipment ecosystems. Built on a historical series (2020–2025) and a forward-looking projection window (2026–2032), the report combines quantitative market sizing with operational diagnostics and scenario-based strategy playbooks intended to inform high-stakes decisions in 2026 and beyond.
Worldwide Off-highway Wheels Market
Why this report matters for 2026 strategic planning
As the off-highway wheels market continues its steady expansion—our modeling shows a compound annual growth rate (CAGR) of 5.6% across the 2026–2032 forecast—the window for decisive moves is narrowing. With the market size measured in USD Million rising from a 2025 baseline to an expected multi-billion-dollar opportunity by the end of the forecast horizon, 2026 is the inflection year when choices around materials, supply chain resiliency, product architecture and channel strategy will materially change competitive positioning.
Worldwide Off-highway Wheels Market
PW Consulting designed this release to be a practical instrument for decision-makers: not merely a map of where demand is growing, but a toolkit that aligns commercial, engineering and procurement levers with near-term market dynamics and longer-term structural shifts.
Worldwide Off-highway Wheels Market
Core actionable outputs inside the report
-
Reliable market trajectory: A validated historical series (2020–2025) and deterministic/probabilistic forecasts for 2026–2032, enabling topline planning, capacity allocation and investor valuation under multiple macro scenarios. The report highlights the 2025 base year position and the expected growth trajectory through 2032 under our base case assumptions.
-
Segment-informed go-to-market playbooks: Practical GTM templates tailored to OEMs, aftermarket distributors, and component suppliers—addressing pricing, warranty structures, spare-parts inventory strategies, and dealer incentives that work in heavy-duty off-highway contexts.
-
Supply-chain and raw-material stress testing: Scenario analyses that quantify exposure to steel-price volatility and logistics disruptions, along with mitigation options—dual-sourcing roadmaps, hedging guidance and regional manufacturing footprint trade-offs.
-
Product architecture and materials roadmap: Comparative frameworks for evaluating steel vs. alternative materials, lightweighting pathways, and integration of sensors to support electrification and predictive maintenance strategies.
-
Regulatory and technical compliance checklist: An operational guide covering critical conformity requirements—e.g., relevant SAE standards and best-practice test protocols—mapped to product development and aftermarket documentation processes.
-
Competitive benchmarking and M&A playbook: A pragmatic screen for M&A and JV candidates, plus valuation sensitivity models that reflect market concentration dynamics and margin profiles across OEM and aftermarket channels.
Market dynamics and the forces reshaping supplier economics
Several structural dynamics are converging to reshape supplier economics in off-highway wheels. Steel remains the foundational material of production—valued for its load-bearing strength and cost-effectiveness—so fluctuations in global steel production and pricing materially influence unit economics. Our analysis references industry indicators showing global crude-steel demand at roughly 1,749 million tonnes in 2025 and observed U.S. structural steel price points that have direct pass-through implications to wheel manufacturers’ cost bases.
At the same time, OEMs and large fleet operators are pressing for lighter assemblies, smarter components and designs compatible with electrified powertrains. This accelerates R&D into hybrid-material concepts and sensor-ready hubs. Compliance and safety standards also remain an operational reality: off-highway components typically must align with established SAE test protocols and machine-safety requirements that influence design cycles and aftermarket documentation.
Competitive landscape — who matters and why
The market exhibits a moderate degree of concentration: the three-largest players account for a meaningful share of revenue, and the top five capture well over half of the accessible market, per our competitive concentration metrics. This structure creates a high-stakes environment where scale, global service networks and product breadth drive winning economics.
-
Titan International, Inc. (West Chicago, Illinois, USA) : A vertically integrated player with deep OEM and aftermarket relationships, Titan’s strength lies in its broad product portfolio across agricultural and construction categories and its capability to service whole-vehicle OEM programs. Strategic moves in financial reporting and capital allocation indicate ongoing focus on margin recovery and aftermarket expansion.
-
moveero Limited (UK) : A legacy specialist in multi-piece steel wheels, moveero is sharply focused on technical differentiation—recent product introductions demonstrate an emphasis on flotation and high-performance fitments for agribusiness. Their visible activity at major industry exhibitions and product launches signals an aggressive innovation cadence aimed at high-margin subsegments.
-
Maxion Wheels (Novi, Michigan, USA) : As one of the largest global steel-wheel manufacturers, Maxion competes on scale and diversified volume across road and off-highway platforms. Their global footprint offers resilience against localized demand shocks and positions them well for large OEM programs requiring consistent cross-border supply.
-
Accuride Corporation : An established wheel-and-rim supplier with strong ties to commercial and off-highway channels. Accuride’s emphasis on durable steel solutions and aftermarket reach make it a natural partner for fleets prioritizing lifecycle cost efficiency.
-
Trelleborg AB : Bringing materials engineering strengths to off-highway wheel and integrated tire systems, Trelleborg competes by integrating performance rubber systems with wheel assemblies—an approach increasingly attractive as customers pursue whole-system efficiency rather than discrete components.
-
Regional and specialist manufacturers : A cohort of regional producers and specialty firms—from Japan, India, Turkey, Canada and Europe—supply customized heavy-duty wheels for mining, forestry and project-specific applications. Their role is to deliver localized technical service and rapid customization—capabilities that larger global players sometimes struggle to match efficiently.
Recent industry moves that matter for 2026
-
Product innovation continues to be a primary battleground: recent launches of next-generation flotation wheels and expanded hub ranges reflect suppliers’ push to capture premium use-cases and address soil compaction and fuel-efficiency demands in agriculture.
-
Trade shows and exhibitions remain strategic accelerants for product validation and channel discovery: leading suppliers used ConExpo and major agritech events to present integrated wheel-and-hub systems and to surface retrofit opportunities for fleet operators.
-
Public financial disclosures and reporting timelines from major players provide signals on profitability trajectories and capital deployment. These disclosures are a primary input into our near-term cash-flow scenario models used by private-equity and corporate development teams.
How executives should use this intelligence in 2026
-
Prioritize modularization and serviceability: Product roadmaps that reduce repair time and simplify aftermarket logistics deliver measurable reductions in total cost of ownership for end customers. Our TCO simulations quantify where investment in three- and five-piece wheel designs or modular hubs returns value within typical fleet replacement cycles.
-
Align sourcing to price-volatility playbooks: Given steel’s dominance in bill-of-materials, procurement teams should deploy layered hedging, regional sourcing diversification, and long-term vendor agreements tied to performance KPIs. The report includes contract templates and negotiation heuristics calibrated to current steel-market behavior.
-
Embed electronics and predictive service features selectively: Sensor integration can transition wheels from passive components to diagnostic nodes, but value accrues only where telematics ecosystems are mature. We identify practical retrofit pathways and product variants optimized for fleets already investing in telematics.
-
Use consolidation metrics to evaluate M&A targets: With a moderate top-tier concentration, acquisitive players can access material scale benefits while bolt-on consolidation remains attractive to large OEMs seeking vertical control of wheel supply and aftermarket channels.
What we intentionally omit here—and why
In keeping with the “trailer” principle for this public briefing, we present strategic line-of-sight and operational recommendations while withholding granular segment-by-segment tables and region-level revenue splits. The full report contains detailed segmentation dashboards, granular regional and end-user forecasts, SKU-level pricing matrices and customer-level share analysis—data assets that are essential for transactions, production planning and precise channel deployment.
Next steps and how to access the complete intelligence
For commercial teams preparing 2026 budgets, product leaders setting R&D milestones, and corporate development professionals assessing M&A, this PW Consulting study provides the analytics backbone for decisive action. The full report—complete with downloadable data tables, scenario models, supplier scorecards and a prioritized roadmap of tactical moves—can be accessed through our market research portal.
PW Consulting stands ready to convert the report’s insights into tailored workshops, target screens, and implementation sprints that rapidly translate strategy into measurable outcomes. Contact our off-highway wheels practice to schedule a briefing and to obtain the complete dataset and supporting tools.
For detailed analysis of this topic, please visit the official page: Worldwide Off-highway Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Linear Position Sensors Market to Expand at 6.45% CAGR (2026–2032) as Asia Pacific Emerges as Market Leader
By pmarketresearch, 2026-07-15
Worldwide Automotive Linear Position Sensors Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As vehicle architectures evolve toward greater electrification, automation and tighter emissions control, the humble linear position sensor has become a strategic component rather than a commodity. PW Consulting’s latest market study projects continued, steady expansion of the global automotive linear position sensors market during the 2026–2032 forecast window. The sector’s trajectory is underpinned by a 6.45% compound annual growth rate (CAGR) across the forecast period and a market that has grown from the low‑thousands in revenue back in 2020 to an estimated US$4.3 billion in 2025, with a projected rise toward approximately US$6.66 billion by 2032.
Worldwide Automotive Linear Positions Sensors Market
This briefing distills the report’s most actionable implications for corporate strategy in 2026. It highlights where executive teams should prioritize R&D and sourcing, how procurement and product groups can de‑risk supply, and why M&A and partnership playbooks need to account for both technological and regulatory tailwinds.
Worldwide Automotive Linear Positions Sensors Market
Why this market matters in 2026
- Performance and compliance intersection: Linear position sensors are now integral to powertrain efficiency, transmission automation, advanced braking and steering control, and emissions management. Design choices at the sensor level materially affect fuel economy and compliance outcomes.
- Technology polarization: Magnetic (Hall‑effect) and inductive solutions are consolidating as the primary approaches. Each class of solution brings tradeoffs in cost, tolerance to harsh environments, packaging and calibration complexity—factors that reshape supplier selection and OEM design choices.
- Commercial leverage points: With the market concentrated among a small set of global Tier‑1s (a top‑five concentration that indicates measurable aggregation but room for challengers), opportunities exist for focused suppliers to win design‑ins via platform attachments, software complements and reliability differentiation.
Strategic implications for OEMs and Tier‑suppliers
For senior leaders planning capital allocation and product roadmaps in 2026, the following implications should be prioritized:
Worldwide Automotive Linear Positions Sensors Market
- Align sensor selection with system‑level KPIs: Decisions between Hall‑effect, inductive and contact‑based solutions should be made at the subsystem level, not in isolation. Use system simulations to quantify lifecycle energy, calibration overhead and failure modes, and bake those into module cost models.
- Invest in software and diagnostics: Sensor hardware is increasingly commoditized; value accrues to firms that pair sensors with robust diagnostic algorithms, self‑calibration routines and predictive maintenance signals. These capabilities shorten warranty cycles and reduce field‑service costs.
- Strategic sourcing and dual‑sourcing: Given component criticality, adopt dual‑sourcing strategies that combine global Tier‑1 relationships with regional specialists to mitigate geopolitical, logistics and single‑point‑failure risks.
- M&A and partnerships lens: Mid‑sized players with differentiated inductive designs, ruggedized housings, or integrated IC capabilities are compelling bolt‑on targets. Pursue partnerships that accelerate time‑to‑market for safety‑critical applications rather than purely volume‑capture plays.
Market trajectory — what the macro numbers tell us
The aggregate market dynamics embedded in our analysis show a resilient growth path: from a multi‑billion‑dollar base in 2025 the market is poised to expand materially through 2032. The 6.45% forecast CAGR reflects a mix of steady unit growth driven by higher electronic content per vehicle, and price mix improvements from higher‑value sensing solutions that include smarter ICs and diagnostic features.
Historical performance through 2025 shows recovery and expansion following the supply disruptions of the early 2020s, and the forecast assumes continued adoption of advanced transmissions, active chassis systems and electrified drivetrains that demand precise linear feedback. Importantly, growth is not uniform: pockets of above‑average expansion will appear where regulatory pressure and advanced vehicle architectures coincide—creating corridors of strategic priority for investment.
Key demand drivers and risk factors
- Drivers: Emissions regulations, increased electrification and the proliferation of automated transmissions and advanced driver assistance systems (ADAS) are the primary demand accelerants. Sensors that support throttle control, exhaust actuation and transmission automation will see persistent demand pressure.
- Technological levers: Improved magnetic ICs, miniaturized inductive architectures and contactless sensing that tolerate metal targets and misalignment are shifting engineering preferences, especially in space‑constrained and harsh environments.
- Supply risks: Raw‑material pressures, specialized manufacturing capacity constraints and single‑sourced components present short‑to‑medium term risks. Firms should map supplier criticality and evaluate alternative technologies as hedges.
- Regulatory and commercial cyclicality: Emissions compliance cycles and global commercial vehicle retrofit programs can create demand phasing; scenario planning for tightening standards and for slower macro cycles is essential.
Competitive landscape — who matters and why
The market is anchored by a group of established global players with differentiated propositions across product breadth, systems integration and sensor IC capability. Our report evaluates each firm across engineering depth, manufacturing footprint, product portfolio (mechanical and magnetic), and go‑to‑market reach. High‑level positioning summaries include:
- Bosch (Germany, https://www.bosch-mobility.com): Global leader with wide portfolio across Hall‑effect and other linear solutions for pedals, suspension and transmission systems. Strengths lie in systems integration and scale manufacturing.
- Continental AG (Germany, https://www.continental.com): Broad position‑sensor portfolio focused on powertrain, chassis and safety systems; strong OEM relationships in both passenger and commercial vehicle segments.
- Honeywell International Inc. (United States, https://sensing.honeywell.com): Emphasizes non‑contact Hall‑effect devices and SMART Position Sensors for motion control in harsh duty cycles—priority partner for ruggedized applications.
- CTS Corporation (United States, https://www.ctscorp.com): Noted for both contacting and non‑contacting linear sensors, with a clear focus on pedal and emissions‑sensitive applications.
- Sensata Technologies (United States, https://www.sensata.com): Specializes in compact spring‑return and other space‑efficient designs for feedback in constrained installations.
- TE Connectivity (Switzerland/Ireland, https://www.te.com): Strong in steering and chassis sensors; notable for cross‑domain connector and sensor systems that ease integration.
- Infineon Technologies AG (Germany, https://www.infineon.com): Supplier of magnetic and Hall ICs that underpin many higher‑level sensor modules; a key enabler for smarter sensor electronics.
- Specialists (Piher, Littelfuse, Phinia, Vishay, Allegro, Novotechnik): These firms bring differentiated inductive, magnetostrictive or contactless solutions and are often preferred for unique packaging, customization or specialized commercial vehicle offerings.
Collectively, the top tier of suppliers account for a meaningful share of the market, producing an industry that is neither a pure oligopoly nor highly fragmented. This creates room for both scale players and niche innovators to co‑exist—if strategic plays are executed with clarity on IP, reliability and supply continuity.
Recent signals to act on (selected)
- Product innovation persists: January–March 2026 saw new Hall‑effect introductions with higher electrical stroke and tighter linearity and resolution—evidence that higher‑precision magnetic solutions are moving into mainstream motion‑control applications.
- Regulatory reinforcement: Ongoing emissions standards and efficiency programs continue to elevate the role of sensors in control loops—making early sensor selection a determinant of system compliance and lifecycle cost.
- Technology substitution opportunities: Inductive solutions are being positioned as cost‑effective, misalignment‑tolerant alternatives to LVDTs in several applications—creating choices for cost‑sensitive platforms.
What our full report delivers (operational contents)
PW Consulting’s full market study is designed as a decision‑readiness tool, not just a dataset. It contains:
- Granular demand forecasting models with scenario planning (base, accelerated electrification, and regulatory shock scenarios) that allow you to stress‑test capital and sourcing plans.
- Technology readiness and migration maps that show likely adoption pathways for Hall‑effect, inductive, magnetostrictive and contact‑based solutions across vehicle subsystems.
- Competitive scorecards and supplier heatmaps assessing engineering capability, capacity, geographic footprint and execution risk.
- Supply chain risk matrices and mitigation playbooks, including dual‑sourcing templates and alternative‑technology sourcing ladders.
- Commercial playbooks for OEMs and Tier‑suppliers covering design‑in strategies, cost‑to‑serve calculators, warranty provisioning models and service‑network implications.
- M&A screening framework and 18‑month integration checklists to help buyers prioritize bolt‑on targets that deliver immediate technological or go‑to‑market synergies.
How leading companies should use the report in 2026
- Product heads: Use the technology migration maps to set 24–36 month development priorities and to define feature roadmaps tied to diagnostics and IC integration.
- Procurement teams: Deploy the supplier heatmaps to create prioritized dual‑sourcing plans and to model total cost of ownership under different logistics and commodity scenarios.
- Strategy and corporate development: Use the M&A screening framework to identify targets that accelerate electrified powertrain or commercial‑vehicle automation capabilities.
- Regulatory and compliance functions: Leverage our scenario analyses to quantify the sensor‑level impact of pending emissions and efficiency standards on vehicle architectures and retrofit markets.
Final recommendation and next steps
In 2026, linear position sensors represent both an enabling technology and a competitive battleground. Executive teams should treat sensor strategy as cross‑functional—spanning product engineering, procurement, regulatory, and corporate development. Action priorities for the next 12 months should include:
- Initiate subsystem‑level TCO and reliability trade‑offs for Hall‑effect vs. inductive options on major platforms.
- Build dual‑sourcing plans that combine scale suppliers with regional specialists for critical applications.
- Prioritize investments in diagnostics and sensor IC integration to extend value beyond hardware.
- Use targeted M&A or partnerships to close capability gaps in ruggedized or space‑constrained sensor solutions.
For teams preparing budgets and strategic plans for 2026, the full PW Consulting Worldwide Automotive Linear Position Sensors Market report provides the detailed inputs, models and executable playbooks necessary to convert market growth and technological change into lasting competitive advantage. To access the complete forecast tables, supplier scorecards and strategic annexes, visit the report landing page and download the full document.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Linear Positions Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mobile Unified Communications & Collaboration Market to Grow at 17.52% CAGR (2026–2032), Reaching USD 85,994.92 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Mobile Unified Communications and Collaboration Market: Strategic Imperatives for 2026
Executive Snapshot
PW Consulting today releases its authoritative market study, Worldwide Mobile Unified Communications and Collaboration Market (base year 2025, forecast 2026–2032). The research documents a multi-year expansion that accelerated through the mid-2020s: global market size increased from approximately USD 11.8 billion in 2020 to nearly USD 27.8 billion by 2025, and is projected to reach roughly USD 33.4 billion in 2026. Under our central forecast the market grows at a compound annual growth rate of 17.52% across the 2026–2032 horizon, culminating in an addressable market that exceeds USD 85 billion by 2032.
Worldwide Mobile Unified Communications and Collaboration Market
Why this report matters to 2026 enterprise decision-makers
- Timing and tempo: The near-term surge in demand for mobile-first collaboration capabilities coincides with an inflection in network investments and regulatory activity. C-suite teams that align vendor selection, network architecture, and procurement windows with this momentum will capture disproportionate value.
- Risk-calibrated scaling: Rapid growth is accompanied by rising concentration—the top vendors now control a meaningful share of market revenue—making vendor diversification, integration flexibility, and contractual safeguards essential to manage lock-in and service continuity.
- Operational readiness: The shift from desktop-centric UC to mobile-native experiences adds new security, compliance, and integration vectors. Decisions made in 2026 on identity fabrics, endpoint management, and network QoS will materially influence total cost of ownership over the next investment cycle.
What the report delivers (practical, decision-focused content)
- Executive playbooks: A procurement checklist, contract negotiation levers, and migration roadmaps tailored for phased migration to mobile-first UC platforms.
- Vendor scorecards and selection matrices: Comparative frameworks that weigh strategic fit, integration risk, AI capability, channel ecosystem, and enterprise-grade support—designed to shorten vendor evaluation from months to weeks.
- Network and operations blueprints: Guidelines for hybrid deployments (cloud + on-prem), carrier integration patterns, edge compute placement, and QoS profiles that map to typical enterprise traffic mixes.
- Security, compliance and resiliency frameworks: Practical controls and compliance pathways for data sovereignty, secure voice/video signaling, and incident response—aligned to contemporary regulatory shifts and disaster reporting obligations.
- Commercial models and TCO scenarios: Comparative TCO analyses across cloud-native, managed, and hybrid UC approaches; sensitivity analyses for seat growth, AI add-ons, and international expansions.
- AI readiness and roadmap templates: A phased capability approach for adding agentic and assistive AI to contact centers and collaboration flows without amplifying operational risk.
Market dynamics: Forces shaping vendor and buyer strategies in 2026
Three interlocking trends dominate the strategy landscape.
Worldwide Mobile Unified Communications and Collaboration Market
- Network and infrastructure evolution: Significant investments in multi-gigabit access and node densification—driven by cable operator DOCSIS upgrades, distributed access architectures, and ongoing mid-band spectrum planning—are materially improving mobile UC performance and enabling richer mobile video and low-latency voice experiences.
- Regulation and sovereignty: Policymakers are actively reshaping the operating environment. Notable examples include changes to disaster reporting requirements and sustained policy work around mid-band spectrum allocation; regional investments in sovereign communications infrastructure continue to influence vendor selection and deployment topology for global enterprises.
- Platform intelligence and consolidation: Providers are embedding AI into meeting experiences, agent workflows, and automated contact-center services. This infusion of intelligence accelerates differentiation but also changes procurement criteria—buyers increasingly evaluate vendors on AI governance, data residency, and model retraining controls as much as on classic feature sets.
Competitive landscape — who matters and why
The market is served by a mix of hyperscale platform providers, traditional enterprise communications vendors, cloud-native UCaaS players, and network operators. Our analysis shows a moderate-to-high level of concentration: market share is moving toward established platform leaders even as nimble cloud vendors capture new greenfield opportunities in SMB and mid-market segments.
Worldwide Mobile Unified Communications and Collaboration Market
- Microsoft Corporation — Positioned as a platform anchor, Microsoft leverages a broad productivity ecosystem to embed mobile UC within workflow and identity. Recent AI-enhanced feature releases deepen the value proposition for enterprises on premium suites.
- Cisco Systems, Inc. — Cisco combines device-level and software integration to appeal to large enterprises with demanding security and hardware interoperability requirements. Strategic acquisitions to add document workflows and contact-center capabilities signal an emphasis on end-to-end engagement stacks.
- Zoom Video Communications, Inc. — Zoom continues to compete on simplicity and developer extensibility, extending mobile-first experiences into unified voice and workspace offerings designed for rapid user adoption.
- RingCentral, 8x8, Nextiva and other cloud-native UCaaS vendors — These providers emphasize agility, channel ecosystems, and verticalized feature packs (including contact-center integrations), competing on go-to-market speed and packaged operational services.
- Traditional enterprise vendors (Avaya, Mitel, Alcatel-Lucent Enterprise, NEC) — Their strengths are hybrid architectures and migration services for large, distributed estates where a phased approach to cloud adoption remains the practical reality.
- Telcos and network owners (Verizon and others) — Service providers are moving up the stack, offering bundled connectivity and UCaaS with quality guarantees; their uniquely positioned network assets and managed services appeal to enterprises prioritizing SLA-backed experiences.
Recent market moves to watch
- Vendor feature momentum: Major vendors are accelerating embedded AI releases and agentic capabilities to improve meeting outcomes and customer engagement. Expect AI packaging and consumption models to become negotiation points during contract renewals in 2026.
- Partnerships and distribution plays: Network operators are bundling UC offerings into public-sector and large-enterprise contracts—creating integrated offers that bundle connectivity, managed services, and UCaaS under a single supplier relationship.
- Portfolio modernization by legacy providers: Long-standing vendors are refactoring portfolios for hybrid cloud deployments and are emphasizing continuity controls to keep existing enterprise customers on migration paths that reduce disruption.
Key implications and recommended actions for 2026
- Adopt a “mobile-first, network-aware” strategy: Treat mobile UC not as a set of device apps but as an architectural layer that requires explicit design for network quality, edge compute, and session continuity.
- Negotiate for AI governance and cost predictability: As vendors bundle AI features, buyers must secure transparent pricing and contractual commitments on data usage, model updates, and performance SLAs.
- Prioritize integration and exit flexibility: Insist on standards-based APIs, documented migration paths, and phased pilots to limit vendor lock-in and reduce migration risk across a multi-year technology refresh cycle.
- Embed regulatory and resilience requirements into procurement: With changes to disaster reporting and sovereign infrastructure builds, compliance and continuity clauses should be explicit procurement requirements rather than afterthoughts.
- Plan for a two-tier deployment approach: Combine rapid user enablement for mobile collaboration with a deliberate backend modernization program (identity, session management, contact-center orchestration) to balance speed and long-term resilience.
How PW Consulting’s report helps you act
This report is designed as a near-operational artifact: it translates market trajectories into executable decisions. Buyers will find playbooks to re-platform contact centers, scorecards to evaluate AI-enabled meeting capabilities, network integration schemas, and contractual language templates to protect entitlements and data governance. For strategy teams, the report offers scenario-based forecasts and investment wallets tied to key pivot points (regulatory milestones, spectrum releases, and major vendor roadmap shifts).
Trailer principle: what we show and what we reserve
In keeping with our role as a strategic adviser, this release highlights market scale, growth trajectory, competitive contours, and actionable recommendations to support 2026 decisions. To preserve the commercial utility of our primary research and to encourage rigorous vendor selection and procurement practice, detailed segmented breakouts (regional allocations, solution-by-solution revenue lines, and vertical-specific dollar breakdowns) are purposefully reserved for the full report and dataset. These granular tables, model files, and regional scenario analyses are available on the report landing page.
Next steps
Enterprises preparing procurement cycles, IT modernization roadmaps, or contact-center transformations for 2026 should use this report as a strategic north star. For access to the complete analytical dataset, vendor-by-vendor benchmarks, shaded scenario models, and procurement templates, please consult the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Central Nervous System (CNS) Stimulants Market to Rise from USD 31.35 Billion in 2025 to USD 47.92 Billion by 2032 at a 6.25% CAGR
By pmarketresearch, 2026-07-15
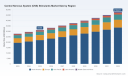
Worldwide CNS Stimulants Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s forthcoming Worldwide Central Nervous System (CNS) Stimulants Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes interoperable quantitative forecasts and qualitative strategic frameworks designed to inform executive decision-making in 2026. Our model projects the global CNS stimulants market to expand at a compound annual growth rate (CAGR) of 6.25% across the 2026–2032 forecast window. Measured in USD (Million), the market has climbed steadily from the mid-2020s and is projected to continue that trajectory through 2032 under our central case assumptions.
Worldwide Central Nervous System (CNS) Stimulants Market
Why this matters to leaders in 2026
- Strategic timing: 2026 is a pivotal year for product launches, reformulation rollouts, and contract negotiations. The combination of regulatory updates and adjusted aggregate production quotas means supply-side decisions made now will determine access and market positioning over the next biannual planning cycle.
- Portfolio resilience: Manufacturers, generics players, and speciality biotech firms must manage a dual challenge — sustaining supply for established ADHD and narcolepsy treatments while selectively investing in differentiated delivery systems, prodrugs and lifecycle extensions that protect value.
- Reimbursement reshaping: Policy initiatives and pilot pricing models introduced in late 2025 and early 2026 are increasing payer scrutiny of high-use CNS categories. Companies that can articulate clear efficiency and adherence cases will have leverage in formulary negotiations and value-based contracting pilots.
Market trajectory — what the headline numbers tell us
PW Consulting’s top-line view is purposefully straightforward: after a period of steady expansion through the early 2020s, the CNS stimulants market reached approximately USD 31,350 Million (base year 2025). Our 2026 baseline positions the market above USD 33,300 Million, with the model compounding annually at 6.25% to reach a mid-2030s range that reflects continuity of demand, constrained but improving supply dynamics, and incremental product differentiation. The forecast is scenario-programmed to reflect regulatory shocks, quota adjustments, and varying uptake rates for new formulations.
Worldwide Central Nervous System (CNS) Stimulants Market
What’s driving growth — structural and tactical factors
- Persistent clinical demand: ADHD and narcolepsy remain the primary clinical anchors for stimulant use globally. Demographic trends, increasing diagnostic awareness in certain markets, and adherence-improving delivery platforms underpin base demand.
- Formulation innovation: Extended-release, delayed‑release, transdermal and prodrug approaches are creating premium niches with margin resilience, even as generic competition intensifies in immediate‑release segments.
- Supply-side dynamics: API concentration and episodic shortages have contributed to volatile availability for amphetamine-based products. This creates both risk and opportunity — premium pricing for reliable supply and incentives for near-shore or dual-source strategies.
- Regulatory and policy momentum: Recent regulatory actions and enforcement levers are altering label requirements, manufacturing oversight, and aggregate production quotas — factors that materially affect production planning and time-to-market for reformulations.
Regulatory and supply landscape — 2025–2026 developments that shape 2026 choices
- Labeling updates: In mid-2025 regulators mandated expanded warnings for certain extended‑release amphetamine and methylphenidate products addressing pediatric safety risks. This alters risk communication strategies, pediatric labelling plans, and clinical trial design for pediatric submissions.
- Quota adjustments: Aggregate production quotas for key stimulants were revised upward in late 2025, responding to manufacturer requests and market shortages. While quota increases can relieve near-term supply pressure, they also formalize manufactured volumes and therefore influence inventory and pricing strategies.
- Quality surveillance and generics assurance: Public sampling and quality confirmations for certain generic extended‑release tablets in early 2026 have moderated some manufacturer risk, but persistent API sourcing constraints mean shortages may continue to be episodic.
- Reimbursement scrutiny: Emerging CMS pricing models and international cost-containment pilots have targeted categories with large utilization footprints; CNS stimulants are on that roster. Companies should prepare differentiated evidence on adherence, clinical outcomes and health economics to safeguard access.
Competitive landscape — what incumbents and challengers are prioritizing
The CNS stimulants arena is a mixed-structure market: concentration is meaningful but not absolute. Leading players command a substantive share of the market while a broad base of generics and niche developers exert pricing and innovation pressure. Our market concentration metrics indicate a moderate level of market share clustering among the top firms, underscoring both incumbent influence and material room for challengers with differentiated value propositions.
Worldwide Central Nervous System (CNS) Stimulants Market
Across the competitive set, strategic priorities diverge:
- Established originators are defending brand equity through lifecycle management — extended-release variants, label expansions where possible, and targeted patient support programs.
- Large generics manufacturers focus on scale, supply reliability and rapid launch readiness when innovator exclusivities lapse.
- Specialty and emerging firms are pursuing technical differentiation — prodrugs, novel delivery systems (including transdermal and delayed-release morning/evening dosing), and pediatric-friendly formulations that respond to new safety labelling demands.
- Manufacturers with integrated manufacturing footprints or diversified API sourcing are converting supply reliability into commercial advantage during periods of constrained availability.
Practical implications and action playbook for 2026
PW Consulting recommends a pragmatic, multi-track approach for corporate leadership, market-access teams and manufacturing strategists:
- Stress-test supply chains now. Scenario-planning should model quota volatility, API disruptions and quality sampling outcomes. Contingency funds for dual‑sourcing, contract manufacturers, and strategic inventory buffers are prudent.
- Prioritize formulary evidence. Prepare concise, payer-focused dossiers that link treatment adherence (supported by differentiated delivery systems) to measurable healthcare utilization reductions.
- Defend margins with targeted innovation. Invest selectively in delivery-platform upgrades and prodrug candidates that create clinically defensible differentiation and delay commoditization.
- Use M&A and capacity partnerships tactically. Strategic bolt-ons that add API capacity, regulatory dossiers, or complementary delivery technologies can be executed with rapid payback in a constrained supply environment.
- Engage regulators proactively. Early dialogue around pediatric labeling implications, post-marketing safety commitments, and quality surveillance programs reduces surprise and shortens approval pathways for lifecycle innovations.
What PW Consulting’s report provides (practical deliverables)
Our full report is constructed to be operationally useful for teams mobilizing in 2026. Key elements include:
- Proprietary forecast model (2026–2032) with scenario toggles (regulatory shock, supply disruption, high/low uptake) and downloadable outputs for integration into corporate financial planning.
- Competitive scorecards and capability heatmaps for the leading and mid‑tier firms, highlighting R&D pipelines, supply footprints, regulatory posture and commercial reach.
- Supply-chain risk matrix and API sourcing map, prioritized by disruption risk and mitigation options.
- Regulatory tracker with timelines, likely labeling impacts and recommended submission strategies aligned to current policy changes.
- Commercial playbooks for market access negotiations, pricing defense tactics, and launch sequencing for differentiated formulations.
What we are intentionally withholding here — and why
In keeping with a “trailer” approach, this announcement emphasizes strategic value and the report’s practical utility while omitting granular regional, drug-type, and indication-specific revenue breakdowns. Those detailed tables, company-level revenue splits, and activation maps are included in the full report and interactive models available through PW Consulting. The goal is to provide decision-makers enough strategic insight to prioritize internal planning while inviting teams to access the full data suite for execution-level actions.
Final note — how to use this intelligence in 2026
For 2026 planning cycles, the imperative is to convert market insight into operational decisions within a tightened regulatory and supply context. Firms that systematically align supply resiliency, payer evidence, and targeted innovation will convert competitive pressure into sustainable advantage. PW Consulting’s report equips leadership teams with the scenarios, tools and tactical playbooks needed to do that work with confidence.
For access to the full forecast model, company scorecards, and region-by-indication detail that underpin our recommendations, refer to the PW Consulting report landing page and request the comprehensive dataset and briefings tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Distribution Power Regulator Market Poised for 6.0% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-15
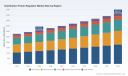
Worldwide Distribution Power Regulator Market — Strategic Insights for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Distribution Power Regulator Market (base year 2025; historical window 2020–2025; forecast 2026–2032) offers a concise, actionable playbook for executives who must make investment, procurement, and product strategy decisions in 2026. The global market is already transitioning from legacy voltage-control architectures to more actively managed distribution systems. Our topline modelling shows the market growing from an estimated USD 3,115.28 Million in 2025 to USD 4,684.23 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.0% over the forecast horizon. These macro dynamics create a portfolio of opportunities — and operational risks — that demand targeted, time-sensitive responses from utilities, OEMs, and private capital.
Worldwide Distribution Power Regulator Market
Why this report matters for 2026 strategy
Decision windows in 2026 will be defined by tightening regulatory expectations, accelerating renewable penetration, and supply-side cost volatility. Our report synthesizes these drivers into commercially pragmatic guidance precisely because 2026 is a crossroads year: organizations that align capital allocation, procurement cadence, and product roadmaps with near-term grid modernization forces will capture outsized value; those that defer will face margin compression and longer lead times for critical hardware.
Worldwide Distribution Power Regulator Market
- Investment timing: We quantify the market trajectory and identify where earlier procurement reduces total cost of ownership in the presence of long lead times for transformer-winding components and mechanical regulator assemblies.
- Supplier selection and negotiation: The research provides a practical framework for evaluating vendor strength, delivery risk, and aftermarket support in a moderately concentrated supplier landscape.
- Regulatory and technical certification readiness: The report maps compliance requirements (performance and enclosure standards, communications protocols) to product-roadmap decisions so product managers can prioritize features that matter to large utility customers.
Market trajectory and what the numbers imply
Our top-line forecast is directional and purpose-built for strategic decision-making: the market expands from roughly USD 2.9–3.1 billion in the mid-2020s to nearly USD 4.7 billion by 2032. This growth reflects the combined effects of distributed generation adoption, electrification of end-uses, and utility-driven voltage management projects. A 6.0% CAGR across 2026–2032 implies that procurement and capacity-planning decisions made in 2026 will materially affect 3–5 year cost curves for utilities and EMS/DER integrators.
Worldwide Distribution Power Regulator Market
Two practical implications for 2026 planners:
- Inventory and contract structure: With steady market expansion, multi-year framework agreements that include indexation to raw-material pass-throughs (notably copper) will limit downside exposure.
- Technology prioritization: Suppliers and buyers must weigh investments in digital-enabled regulator controls and communications interoperability against mechanical reliability and lifecycle maintenance costs.
Market structure and competitive dynamics
The distribution power regulator market is moderately consolidated. PW Consulting’s concentration analysis shows that the three largest suppliers command a meaningful share of the market, while the top five collectively represent a majority position — a structure that advantages established OEMs with global service networks, standardized product portfolios, and deep utility relationships. This concentration translates into differentiated bargaining power, but it also leaves niches and geographies where specialized and agile suppliers can win through technical differentiation and localized service models.
Key competitive positions and implications for 2026:
- ABB Ltd. (Zurich): A strong electrification and grid-solutions portfolio positions ABB to capture large utility projects where integrated solutions and lifecycle services are prioritized.
- Eaton Corporation Plc (Dublin): Eaton’s Cooper Power Series and advanced control options make it a go-to supplier for utilities seeking established single-phase and substation regulator platforms with modern control stacks.
- Siemens AG / Siemens Energy (Munich): Siemens’ long legacy in regulation technologies, combined with system-level offerings for renewable integration, gives it a durable advantage in projects that require tight integration with grid controls.
- GE Vernova (Boston): With IEEE C57.15-compliant pole-mounted and substation regulators that handle reverse power flow, GE Vernova targets distribution circuits increasingly impacted by distributed energy resources.
- Schneider Electric SE (Rueil-Malmaison) and Hitachi Energy (Zurich): Both emphasize medium-voltage distribution equipment and line-voltage regulator solutions that support renewable hosting and feeder-level voltage management.
- Specialists and regional players (Howard Industries, Toshiba, Daihen, Maschinenfabrik Reinhausen, Rockwill, TSI, and others): These vendors are strategically important in regional tenders and for customers who require tailored mechanical/regulatory features or fast local service.
For 2026 buyers, the practical takeaway is clear: align tender design with supplier strengths. Long-term performance guarantees, communication-protocol interoperability, and lifecycle service commitments will be decisive selection criteria.
Regulatory, standards, and raw-material considerations shaping procurement
Design, procurement, and acceptance tests for distribution regulators are governed by established electrical and enclosure standards. Voltage regulators commonly are specified against IEEE C57.15 performance criteria and NEMA 4 enclosure protection; many utility purchasers also require KEMA-level certifications and mechanical endurance validations. Modern regulator solutions increasingly integrate communications using industry protocols such as IEC 61850, IEC 60870-5, DNP3 and MODBUS to support distribution automation and feeder-level telemetry.
Raw-material volatility is not an academic risk in 2026 planning. For example, copper — a primary input for windings — is forecasted under base-case assumptions to average approximately USD 11,400 per tonne in 2026, exerting direct pressure on BOM costs and, by extension, supplier lead times and pricing. Our report includes sensitivity analyses that translate commodity moves into margin, contract-indexation options, and hedging strategies.
Technology and product trends to watch in 2026
- Integrated, transformer-coupled regulators that provide active voltage control at the feeder level; recent product introductions illustrate vendor focus on compact, integrated form factors for space-constrained sites.
- Controls and communications: products that support IEC 61850 and other protocols reduce integration costs with distribution automation platforms and improve operational visibility.
- Reverse-power-flow handling and bidirectional regulation capabilities as feeders become multi-directional with increased DER penetration.
Notable recent development: Hitachi Energy’s June 2025 launch of a Compact Line Voltage Regulator (C-LVR) — a transformer-integrated regulator for active voltage control — exemplifies how OEMs are converging transformer and regulator architectures to reduce footprint and installation complexity. PW Consulting’s vendor readiness matrix highlights which suppliers can scale such innovations into large-volume utility programs and which are still at pilot or niche adoption stages.
What the PW Consulting report delivers (practical, non-academic tools)
PW Consulting’s report is designed as a decision-support toolkit, not just a market estimate. Contents include:
- Top-down and bottom-up market models with scenario branches for high-renewables and conservative-demand outcomes for 2026–2032.
- Supplier scorecards that evaluate commercial terms, technical breadth, field-service coverage, and certification readiness to support procurement RFPs.
- Use-case driven ROI templates (utility feeder upgrade, industrial process-voltage stability, urban residential upgrades) that translate technical specs into financial metrics.
- Regulatory compliance mapping and test-plan checklists to fast-track acceptance testing and reduce commissioning risk.
- Raw-material sensitivity assessments and recommended contract clauses for mitigating copper and critical-components exposure.
- Deal-structuring guidance for capex-light paths (PPAs, service-as-a-product) and lifecycle contracting strategies for municipal and investor-owned utilities.
How to use the report in 2026
Procurement teams should use the report to redesign tender timelines (shorter windows for critical spares, longer lead-time forecasting for major capital programs). Product and engineering leaders should prioritize communications interoperability and reverse-power-flow capability in next-generation product roadmaps. Investors and M&A teams should target specialized niche vendors in regions where global suppliers have limited local footprint but where demand is rising fastest.
Closing — a strategic invitation
PW Consulting’s Worldwide Distribution Power Regulator Market study is purpose-built to convert market intelligence into executable decisions in 2026. The document balances rigorous market-sizing — including our base- and scenario-forecasts for 2026–2032 — with hands-on procurement, specification, and negotiation tools. To protect the commercial integrity of vendor-level and subsegment-level data (and to give you the most actionable, up-to-date inputs for tender and product decisions), detailed splits and supplier-level financials are held within the full report.
Clients seeking to accelerate their 2026 strategy — whether for capital planning, vendor selection, or product development — will find the report a practical roadmap. Contact PW Consulting or visit our report page to access the full dataset, supplier scorecards, and downloadable decision tools that translate these market dynamics into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Distribution Power Regulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High‑Purity Lignin Market Poised for 7.21% CAGR Through 2032 as Europe Emerges as Leading Region
By pmarketresearch, 2026-07-15
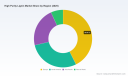
Worldwide High Purity Lignin Market — Strategic Briefing for 2026 Decision‑makers
Executive trailer
PW Consulting today publishes an advanced industry briefing to accompany our forthcoming Worldwide High Purity Lignin Market report. This briefing is designed as a strategic “preview”: it surfaces the decisive trends, competitive dynamics, operational levers and near‑term actions that senior executives, corporate development teams and investment committees must consider as they set priorities for 2026. The full report contains the granular datasets, supplier scorecards and transaction pipeline intelligence necessary to execute on these opportunities; the summary below signals where value will accrue and why immediate alignment to new playbooks matters.
Worldwide High Purity Lignin Market
Macro view: market scale and trajectory
High purity lignin has moved from niche specialty to a commercially investible industrial platform. Our market accounting shows the sector more than doubled in measured revenue through the early 2020s, rising from a lower‑tens position in 2020 to a mid‑double‑digit figure by the 2025 base year. The market enters the 2026–2032 forecast window with a structurally positive outlook — a compound annual growth rate (CAGR) of roughly 7.2% across the forecast period. Under that trajectory, demand and monetizable revenue are expected to converge with new scaling of downstream applications such as carbon materials, resins and bio‑polymers, supported by strengthened policy incentives and industrial adoption curves.
Worldwide High Purity Lignin Market
Why 2026 is an inflection year
-
Commercial readiness and scale: Late‑stage pilot projects are transitioning into early commercial shipments; a number of vendors reported first large‑bag deliveries and demo‑plant launches in 2024–2025. These shifts compress lead times for procurement and qualification cycles, opening windows for offtake agreements in 2026.
Worldwide High Purity Lignin Market -
Policy momentum: Stringent carbon and circular‑economy regulations in key markets, paired with green public procurement, materially improve the business case for lignin substitution in multiple value chains. Expect procurement teams and product stewards to prioritize low‑embodied‑carbon raw materials in 2026 RFPs.
-
Feedstock economics and capacity dynamics: Global kraft pulping and lignin extraction capabilities have reached substantive scale, creating a more predictable feedstock base. That predictability reduces commercial risk but raises the bar for differentiation at the product and application level.
What the full report delivers (practical content)
PW Consulting’s full deliverable is intentionally hands‑on. It is designed not just to inform, but to enable execution across procurement, R&D and M&A. Key practical components include:
-
Granular market-sizing and scenario models (base, adoption, stress) that let clients run bespoke revenue and margin sensitivities.
-
Supplier benchmarking and scorecards covering technology platform, purity specifications, certification, capacity outlook, and commercial terms.
-
Application ROI playbooks for resins, carbon fiber precursors, bioplastics and specialty chemistries, with cost parity thresholds and substitution roadmaps.
-
Regulatory and funding maps showing where public incentives, procurement policy and procurement tenders favor lignin‑based solutions.
-
Technology maturity and commercialization roadmaps with recommended partnership structures (pilot → co‑development → local sourcing) for accelerating product qualification.
-
M&A and JV target shortlists aligned to three buyer archetypes: feedstock owners, downstream formulators and strategic end‑users seeking backward integration.
-
Operational checklists for scaling: quality control protocols, sampling regimes, logistics options (from bulk big‑bag distribution to integrated pipeline solutions) and embodied‑carbon accounting templates.
Competitive landscape: who matters and why
The market is moderately concentrated: the top three suppliers capture a meaningful share of current commercial volumes, while the top five increase that presence substantially. This concentration profile creates both constraints and opportunities for buyers and investors.
From a strategic standpoint, several company profiles merit particular attention:
-
Borregaard (Norway): A legacy incumbent with deep application engineering expertise and a long history of lignin‑based product commercialization. Borregaard’s strength is in formulation support and tailored biopolymer solutions across dispersants, binders and industrial substitutes — a natural partner for formulators seeking rapid product qualification.
-
Stora Enso (Finland): A leader in kraft lignin commercialization with branded portfolios and demonstrated pathway to battery‑grade carbons through partnerships. Their platform is attractive to strategic buyers targeting advanced materials applications, especially where vertical integration with pulp operations is a value lever.
-
UPM Biochemicals (Finland): Emphasizes consistent quality and formulation support, positioning itself as a reliable supplier for resins and adhesives. For industrial customers, UPM represents a lower technical risk option when precision in feedstock behaviour is required.
-
Mercer International, Domtar, West Fraser, Metsä Group and Nippon Paper Industries: These pulp‑operator adjacent players leverage integration into existing mill flows and certifiable forestry supply chains. They are the most credible sources of scale—critical where customers require long‑term security of supply.
-
Pure Lignin, Lignin Industries and other technology‑led SMEs: These players are pioneering high‑purity native fractions and thermoplastic conversion technologies. They are important innovation partners and potential bolt‑on targets for larger integrators or specialty material manufacturers.
Recent industry moves that change the playbook
-
Early commercial shipments (2025): The first large‑scale shipments from pilot phase producers signal that qualification cycles can now be compressed from years to quarters. Corporates should revisit supplier onboarding timelines and consider staged offtake models.
-
Demo‑plant product launches: Demo‑scale outputs for specific uses (for example concrete admixtures) mean that construction and infrastructure procurement teams can pilot lignin‑based chemistries in real projects—opening procurement windows for 2026 tenders.
-
Cross‑industry partnerships: Collaborations that adapt lignin for battery anodes and sodium‑ion chemistries show the material’s versatility beyond traditional resin or binder markets. R&D teams should explore co‑development agreements to de‑risk technical transfer.
Strategic implications and prioritized actions for 2026
Based on our analysis, executives should organize a focused set of cross‑functional initiatives in 2026 to capture first‑mover advantage while reducing commercialization risk:
-
Accelerate supplier qualification with staged offtake and co‑development clauses: Use pilot purchases with defined scale‑up triggers to secure pricing and priority allocation without locking capital prematurely.
-
Deploy application‑level pilots tied to procurement levers: Work with suppliers to instrument pilots where total cost of ownership and carbon accounting can be demonstrated in real projects; prioritize areas where substitution delivers both cost and regulatory compliance benefits.
-
Reassess capex vs contract supply economics: For companies with access to feedstock (pulp mills, forestry operations), evaluate backward integration. For formulators, weigh multi‑supplier contracts to manage supply continuity.
-
Map M&A and JV targets by capability: Identify technology innovators to secure IP footholds and pulp‑integrated players to shore up volumes. The full report provides an expedited target shortlist aligned to buyer strategy archetypes.
-
Institutionalize embodied‑carbon accounting protocols: As disclosure rules tighten, early adoption of consistent carbon metrics will speed market access and reduce commercial friction in green procurement.
Risk matrix and mitigation
Adoption risks are tangible but manageable. Key risk vectors include feedstock price volatility, specification drift across mills, regulatory uncertainty, and competition from alternative bio‑polymers. Effective mitigations include diversified supplier panels, specification harmonization programs, indexed pricing in offtake contracts, and staged technical milestones in co‑development agreements.
How PW Consulting helps clients act in 2026
PW Consulting couples primary supplier diligence with rigorous scenario modeling and executable playbooks. Clients benefit from:
-
Executable procurement templates and negotiation playbooks that incorporate quality spec clauses, escalation pathways and ramp schedules;
-
Tailored application ROI models that translate lab metrics into P&L impacts and payback periods;
-
A prioritized M&A/JV target map with valuation heuristics and integration checklists;
-
Regulatory and funding opportunity trackers that connect project profiles to available grants and green tenders.
Final note — why this is a must‑read for 2026 planners
The high purity lignin sector is moving from technical promise to commercial substance. The market’s compound growth and evolving supplier ecosystem create a narrow window in 2026 for strategic commitments that shape long‑term cost structures and product roadmaps. Firms that align procurement cycles, R&D partnerships and capital allocation to the realities outlined in this briefing will secure advantaged access to both feedstock and market share as the sector expands.
Learn more
This preview outlines strategic priorities and the operational playbooks required for near‑term action. PW Consulting’s full Worldwide High Purity Lignin Market report contains the underlying datasets, segmentation analytics, supplier scorecards and M&A shortlists that support immediate execution. To access full intelligence and client‑only advisory services for 2026 implementation, please consult PW Consulting’s report page or contact our Industrial Bioeconomy practice team.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive FPC Market Poised for Rapid Expansion — 16.0% CAGR Forecast Through 2032
By pmarketresearch, 2026-07-15
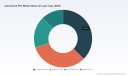
Worldwide Automotive Flexible Printed Circuit (FPC) Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest flagship study on the Worldwide Automotive FPC Market provides the strategic line-of-sight that automotive OEMs, Tier‑1s, semiconductor suppliers and private investors need as they shape 2026 roadmaps. The market has evolved from an emerging systems enabler into a foundational component for electrification, ADAS/autonomy and increasingly complex in-cabin experiences. Our analysis shows that the total market expanded from approximately USD 1.05 billion in 2020 to USD 2.61 billion in 2025, and is projected to exceed USD 3.28 billion in 2026. Over the 2026–2032 forecast window the market is modeled to grow at a compound annual growth rate (CAGR) of roughly 16%, reaching an estimated USD 7.37 billion by 2032.
Worldwide Automotive FPC Market
Why this report matters for 2026 strategic choices
-
Timing capex and capacity: With double‑digit growth and upward cost pressure on key raw materials, 2026 is a pivotal year to decide whether to scale in‑house FPC capabilities, secure long‑term supply contracts, or outsource to qualified partners.
Worldwide Automotive FPC Market -
Product architecture trade‑offs: FPCs are no longer limited to simple interconnects; design choices (rigid‑flex, multilayer vs. double‑sided layouts) materially affect system reliability, EMC behaviour, and manufacturability. Our scenario modeling quantifies the break‑even windows for such trade‑offs under near‑term material cost shocks.
Worldwide Automotive FPC Market -
Compliance, safety and cybersecurity: As functional safety standards and vehicle cybersecurity rules tighten, procurement and quality teams must bake compliance into supplier selection. The report maps ASIL implications and regulatory touchpoints to supplier capabilities so product, compliance and sourcing groups can speak the same language in 2026 negotiations.
-
M&A and partnership prioritization: With a moderately concentrated vendor landscape, selective acquisitions or strategic alliances can accelerate capability capture. Our competitive heat‑maps indicate which technology gaps are most commonly targeted by recent M&A and co‑development activity.
Market dynamics shaping 2026 playbooks
The FPC market sits at the intersection of three structural forces — electrification, sensing/compute proliferation, and in‑cabin digitalization. Each of these creates distinct technical demands (high‑current battery monitoring, high‑speed data lines for sensors, and fine‑pitch designs for displays) that push FPC complexity upward.
Meanwhile, cost dynamics and regulation are exerting outsized influence:
-
Raw material volatility: Global copper foil disruptions and a near‑term 15% YoY rise in copper foil prices have compressed margins for FPC manufacturers. Polyimide film supply tightness and feedstock price swings have added another layer of cost pressure, particularly for high‑temperature and high‑reliability FPC variants.
-
Labor and skills: Quality‑intensive FPC assembly requires skilled operators and advanced process controls. Our field interviews and market cost models show an increased production cost baseline in Asia‑Pacific driven by a skilled labor shortage, prompting multiple suppliers to automate selective production lines in 2025–26.
-
Regulatory lift: ISO 26262 evolutions and EU cybersecurity regulations are raising the bar for component qualification. For safety‑critical applications such as airbag controllers and certain battery management functions, the need for ASIL‑aligned design and documentation is non‑negotiable — and it changes supplier evaluation criteria.
Competitive landscape — what we found
The FPC supplier ecosystem remains clustered around established electronics materials and manufacturing houses, with a top‑three concentration that together command a meaningful share of the market and a top‑five that extends industry control. Our market concentration metrics identify a CR3 of about 42.5% and a CR5 of about 58.8%, a structure that favors established incumbents yet leaves space for focused challengers with specialized technology or cost advantages.
-
Nitto Denko Corporation (Japan) — A leader in automotive FPCs, recognized for high‑reliability solutions for instrument panels, airbags and sensors. Nitto’s October 2025 launch of an AEC‑Q100 compliant FPC series for EV battery monitoring underscores the company’s emphasis on validated, safety‑oriented product families.
-
Sumitomo Electric Industries, Ltd. (Japan) — Strong in high‑density FPCs used across ECUs, infotainment and ADAS. Public supplier nominations in mid‑2025 reflect deep OEM relationships and entrenched design wins for next‑generation ADAS platforms.
-
Nippon Mektron, Ltd. (Japan) — Well‑regarded for multilayer FPCs in cameras, LiDAR and battery management. A joint development agreement with a European automaker announced in early 2025 signals a trend toward regionally co‑developed supplier models for autonomy sensor stacks.
-
Flexium Interconnect, Inc. (Taiwan) — Focused on automotive displays and lighting. Its product portfolio aligns with the growing in‑vehicle display and cockpit requirements for thin, flexible interconnects.
-
Interflex Co., Ltd. (South Korea) — Supplies FPCs for touch panels, sensors and power distribution; proximity to major OEMs in Korea supports rapid integration cycles.
-
Zhen Ding Technology Holding Limited (Taiwan) — Moving into EV battery pack segments and high‑speed data transmission applications; completed validation for solid‑state battery integrations in late 2024.
-
Multi‑Fineline Electronix, Inc. (MFLEX) (USA) — Specialty supplier offering custom FPCs for wearables integration and ADAS-related modules; attractive for North American design teams seeking local support.
-
Fujikura Ltd. (Japan) — Focused on harness replacement and high‑frequency transmission; its strengths sit at the junction of traditional wire harness know‑how and modern printed interconnect requirements.
Recent supplier developments — supplier nominations, product launches and cross‑border co‑development agreements — show two clear industry dynamics: (1) OEMs prefer partners who can simultaneously deliver design support and validated reliability for safety‑critical uses; and (2) suppliers are investing in application‑specific FPC series that meet automotive test standards to accelerate qualification cycles.
Report contents — what you’ll find inside (select highlights)
Our report is structured to be immediately actionable for leadership teams and procurement cells preparing 2026 budgets and sourcing strategies. Key elements include:
-
Market sizing & forecast: An independent base (2025) and detailed 2026–2032 forecasts, including sensitivity scenarios that account for raw‑material and regulatory shocks.
-
Technology taxonomy and roadmaps: Comparative analysis of single‑sided, double‑sided, multi‑layer and rigid‑flex FPCs, and guidance on where each technology yields competitive advantage by application area.
-
Supplier scorecards: Third‑party validated assessments covering quality systems, automotive certifications, manufacturing footprint, innovation pipeline and price competitiveness.
-
Cost‑to‑serve models: Granular factory and logistics modeling that isolates the drivers of unit cost under different procurement modes (make, buy, JV), useful for ROI and capex prioritization.
-
Regulatory & compliance playbook: Practical checklists and timelines for achieving ASIL and cybersecurity readiness in the supplier audit process.
-
Supply chain stress tests: Simulated disruption scenarios (copper, polyimide, labour) and recommended mitigation measures including strategic inventories, dual sourcing and nearshoring thresholds.
-
M&A and partnership decision framework: Criteria and scorecards designed to evaluate target fit given technological, geographic and regulatory considerations.
Actionable recommendations for 2026
-
Lock strategic raw‑material links: Negotiate indexed/volume contracts for copper foil and polyimide film, and layer contingent pricing clauses to protect margins against feedstock volatility.
-
Pursue co‑development with tiered qualification milestones: Shorten time‑to‑production by sharing compliance testing schedules and integrating supplier test results early in vehicle programs.
-
Prioritize modular architectures: Where feasible, standardize on modular FPC subassemblies to reduce qualification cycles and enable supplier interchangeability.
-
Build redundancy into critical nodes: For battery management and safety‑critical sensor lines, deploy dual suppliers or geographic diversification to hedge concentrated capacity risks.
-
Invest in verification and cyber‑hardening: Augment supplier audits with cybersecurity checklists tied to EU regulation expectations and ISO functional safety artefacts.
-
Consider targeted equity plays: If rapid capability capture is required, pursue minority stakes in specialist FPC houses that offer unique materials expertise or proprietary process IP.
How executives should use this study
Use the report as the strategic basis for 2026 procurement negotiations, product architecture reviews, and investment memos. The materials include executive one‑pagers for board briefings, a supplier short‑list engine, and negotiation playbooks that align sourcing levers to forecasted market scenarios. Importantly, while we present comprehensive market sizing and supplier intelligence, detailed segment tables and confidential supplier scoring matrices are reserved for report subscribers — enabling you to base decisions on validated primary data and robust scenario analysis.
Conclusion — the 2026 inflection
The FPC market for automotive is entering a phase where technical differentiation, regulatory readiness and supply resilience will determine winners and losers. With a strong historical expansion to USD 2.61 billion in 2025 and aggressive projected growth into 2032, 2026 should be treated as a decision year: strengthen supplier relationships now, align architectures to safety and cyber standards, and build procurement protections against raw‑material and labour volatility. PW Consulting’s Worldwide Automotive FPC Market report equips decision‑makers with the quantitative forecasts, supplier insights and tactical playbooks to make those choices with confidence.
For executives seeking the full dataset, supplier scorecards and scenario workbooks, please visit the PW Consulting report page to access the complete Worldwide Automotive FPC Market study and our advisory services for tailored implementation plans.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive FPC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com